
Top 7 Lenders for a 520 Credit Score Personal Loan in 2026
Last updated: 2026-11-10
Walking into a bank with a 520 credit score often feels like trying to knock on a heavy iron door that won’t budge. When your score sits in the low 500s, traditional lenders might turn you away before you even finish your sentence. This number usually signals a history of late payments, high credit utilization, or perhaps a recent bankruptcy or collection that has heavily weighted your report.
The financial world in 2026 has changed, offering more pathways for those navigating difficult credit chapters. Finding the right lender requires looking past shiny advertisements and focusing on actual eligibility. What matters most is not just getting the cash today, but understanding the long-term cost of borrowing.
Speed, loan amounts, and the impact on your credit score are the primary metrics used to separate genuine lifelines from predatory traps. For example, a lender offering “instant” cash might charge an APR that effectively triples your debt within a year. Conversely, a specialized installment lender might offer a fixed rate that allows for a predictable exit strategy from your financial crisis.
- Avant
- JetzLoan
- Mint Payday Loans
- Quick Credit
- Time Financing Service
- 50KLoans
- Cash Store
How These Lenders Were Evaluated for Low Credit Scores
The selection process focused on lenders that actively cater to the subprime market. Since a 520 score is significantly below the typical 580 threshold required by many mainstream institutions, the priority was identifying companies that offer high approval odds for those with bruised credit histories. We looked at the distinction between “hard” and “soft” inquiries and the speed of the underwriting process.
We also checked whether the lender uses alternative data, such as banking history or utility payment consistency, to determine eligibility. Each entry was assessed based on the availability of rapid funding, the maximum loan limits provided, and the clarity of their terms. The goal was to provide a hierarchy of options ranging from flexible marketplace connectors to specialized installment lenders designed for immediate emergency needs.
We specifically looked for providers that do not penalize the borrower for the very act of checking their eligibility. This is a critical distinction for someone whose credit score is already in a fragile state. Using a marketplace model can often be safer than a direct application when your score is on the line.
| Lender Name | Max Loan Amount | Funding Speed | Credit Requirements |
|---|---|---|---|
| Avant | See site | See site | Approves scores as low as 550 |
| JetzLoan | $50,000 | As little as 24 hours | No hard credit pull check |
| Mint Payday Loans | $1,000 | Same Day | All credit types welcome |
| Quick Credit | $3,000 | As soon as today | Bad credit welcome |
| Time Financing Service | $12,000 | See site | See site |
| 50KLoans | $50,000 | Next business day | Any credit type welcome |
| Cash Store | See site | See site | See site |
Ranking of Best Lenders for Low Credit Scores
1. Avant
Avant positions itself as a partner for those attempting to move financially forward. They recognize that life is not a straight line and offer various solutions including credit cards and personal loans specifically designed for individuals with non-traditional financial histories. Unlike traditional banks that rely solely on a FICO score, Avant’s algorithm often looks at a broader spectrum of financial health. This can be a lifeline for those with a 520 score who have since stabilized their income.
This lender is a strong choice for borrowers looking to consolidate debt or cover an unexpected expense. For instance, if you are juggling five different high-interest credit card payments, a single Avant loan could consolidate those into one manageable monthly payment. While their standard threshold sits around the 550 mark, they remain a top-tier option for those working to climb out of the low 500s by demonstrating consistent income through their application process.
Pros:
- Offers debt consolidation options.
- Provides tools to help move financially forward.
- Flexible choices for different life stages.
Cons:
- May require a score slightly higher than 520 for the best rates.
2. JetzLoan
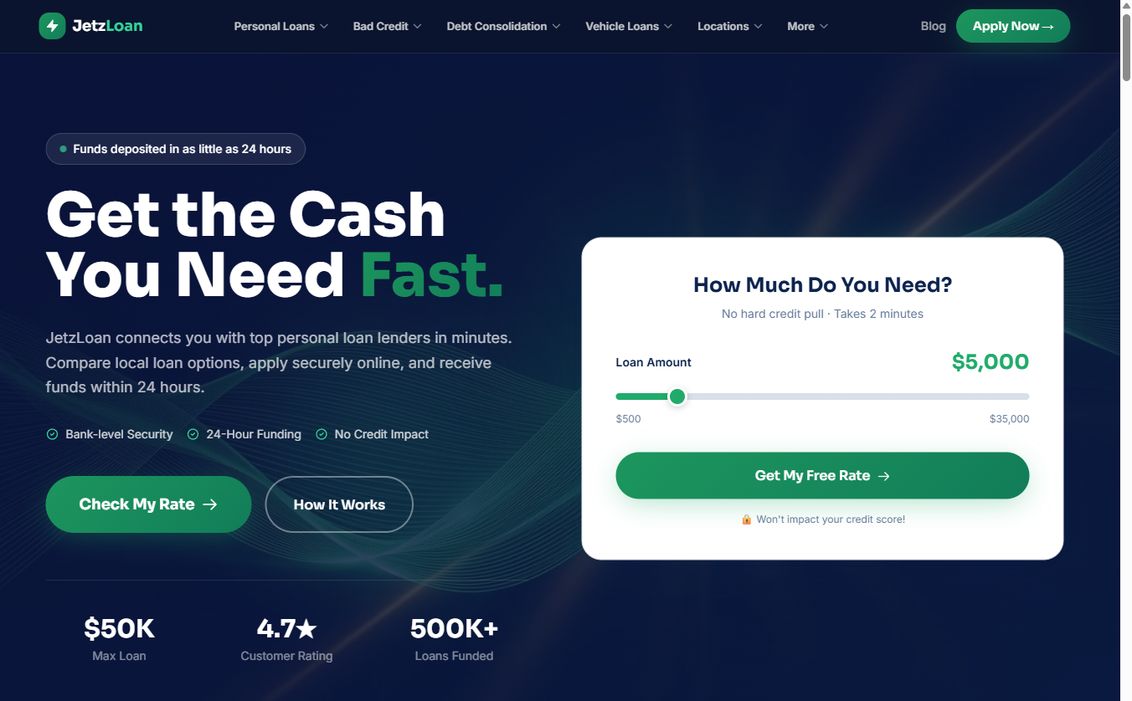
JetzLoan acts as a bridge, connecting borrowers with a wide network of top lenders in a matter of minutes. Their platform is built for speed, making it an ideal choice for someone who needs to see how they stand without risking their score. This “marketplace” model is essential for the subprime borrower because it allows you to cast a wide net across multiple lenders simultaneously. (jetzloan.com)
The standout feature here is the ability to check rates without a hard credit pull. This allows users to shop around for the best deal on a $50,000 maximum loan without leaving a permanent mark on their credit report. If you are shopping for a loan to cover a major car repair or an unexpected medical bill, being able to compare multiple offers without the “inquiry sting” is a massive advantage for maintaining your credit score’s stability.
Pros:
- Fast funding within 24 hours.
- No hard credit pull to check rates.
- High maximum loan limit of $50,000.
Cons:
- Connecting with lenders is a marketplace model, not a direct loan.
3. Mint Payday Loans
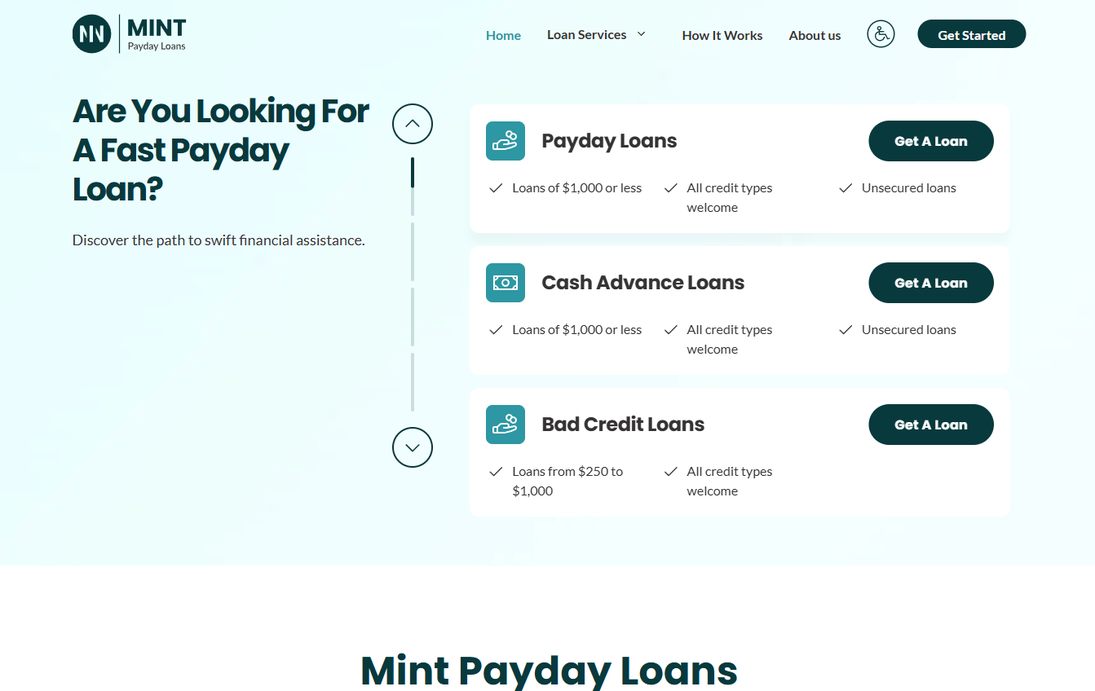
When the situation is urgent and the amount needed is small, Mint Payday Loans steps into the ring. They specialize in smaller, unsecured loans ranging from $250 to $1,000, which are perfect for quick cash advances. These are designed for the “micro-emergencies”—the broken water heater, the sudden transmission issue, or the unexpected utility bill that arrives a week before your next paycheck.
This is a “quick fix” option for those facing immediate bills. They welcome all credit types, meaning a 520 score won’t be an automatic barrier to receiving some form of swift financial assistance. Because the loan amounts are low, the risk to the lender is also lower, which is why they are often willing to work with borrowers who have been rejected elsewhere. However, users must be wary of the total interest paid relative to the small amount borrowed.
Pros:
- Extremely fast same-day approval options.
- Welcomes all credit types.
- Low loan amounts make them accessible.
Cons:
- Loan amounts are capped at a relatively low $1,000.
4. Quick Credit
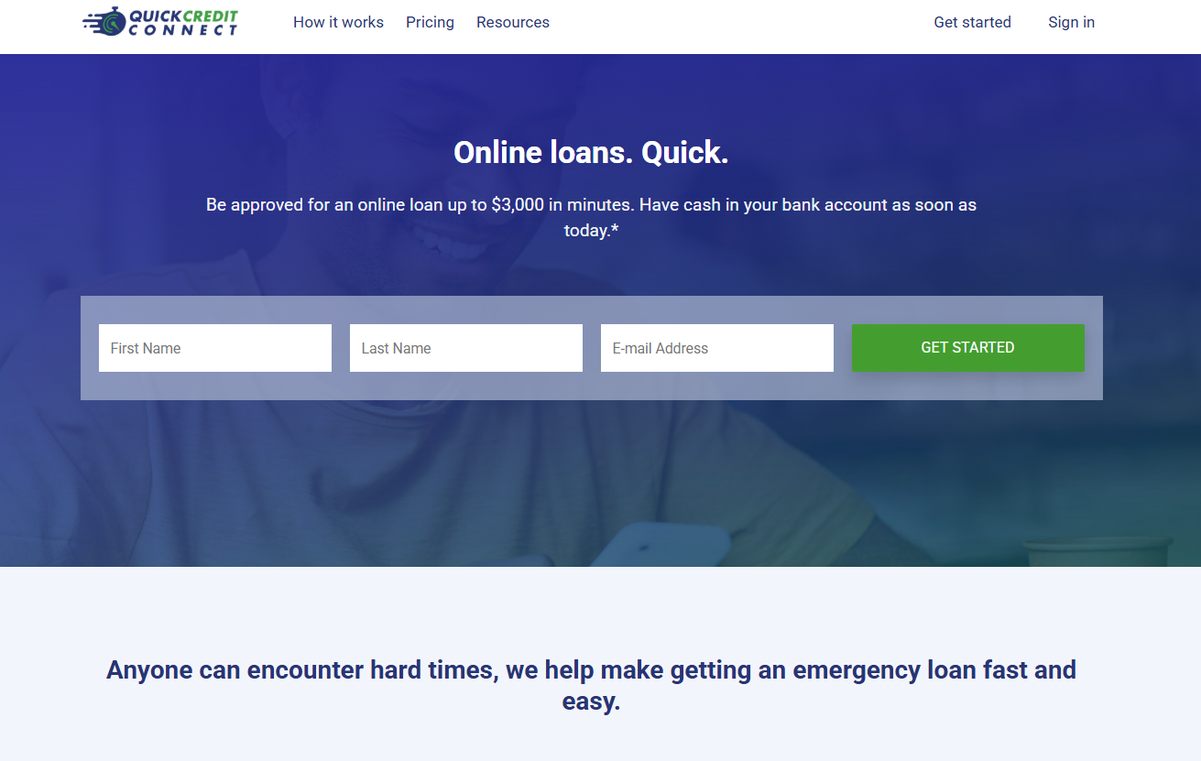
Quick Credit focuses on the “emergency” aspect of borrowing. If you find yourself in a pinch, they offer installment loans up to $3,000 that can potentially land in your bank account as soon as today. This makes them a superior option to a payday loan for someone who can afford to pay the money back over several months rather than all at once on their next payday.
The application is designed to be simple and encrypted, making it easy to use on a mobile phone while you are on the go. The digital-first approach means you don’t have to drive to a physical storefront or wait in line, which is crucial if you are dealing with an emergency that requires immediate action. It is a streamlined solution for those who need to avoid the headache of long paperwork and complicated financial history explanations.
Pros:
- Fast approval in minutes.
- Highly accessible via mobile devices.
- Funds can be available the same day.
Cons:
- Maximum loan amount is limited to $3,000.
5. Time Financing Service
Time Financing Service provides a middle ground for those needing more than a tiny cash advance but less than a massive bank loan. They offer personal loans ranging from $1,500 to $12,000 for those in need of a bit more breathing room. This range is particularly useful for “bridge financing”—covering a gap between two periods of income or paying down a larger debt that is accruing high interest.
They lean heavily into convenience, offering a mobile app that allows you to pay your bills anytime. This flexibility is a godsend for people trying to manage a tight budget while rebuilding their financial standing. By making payments through an app, you can ensure you never miss a deadline, which is the single most important factor in raising that 520 score back into the 600s.
Pros:
- Moderate loan amounts up to $12,000.
- Convenient mobile app for payments.
- Referral incentives available.
Cons:
- Limited loan range compared to larger personal loan providers.
6. 50KLoans
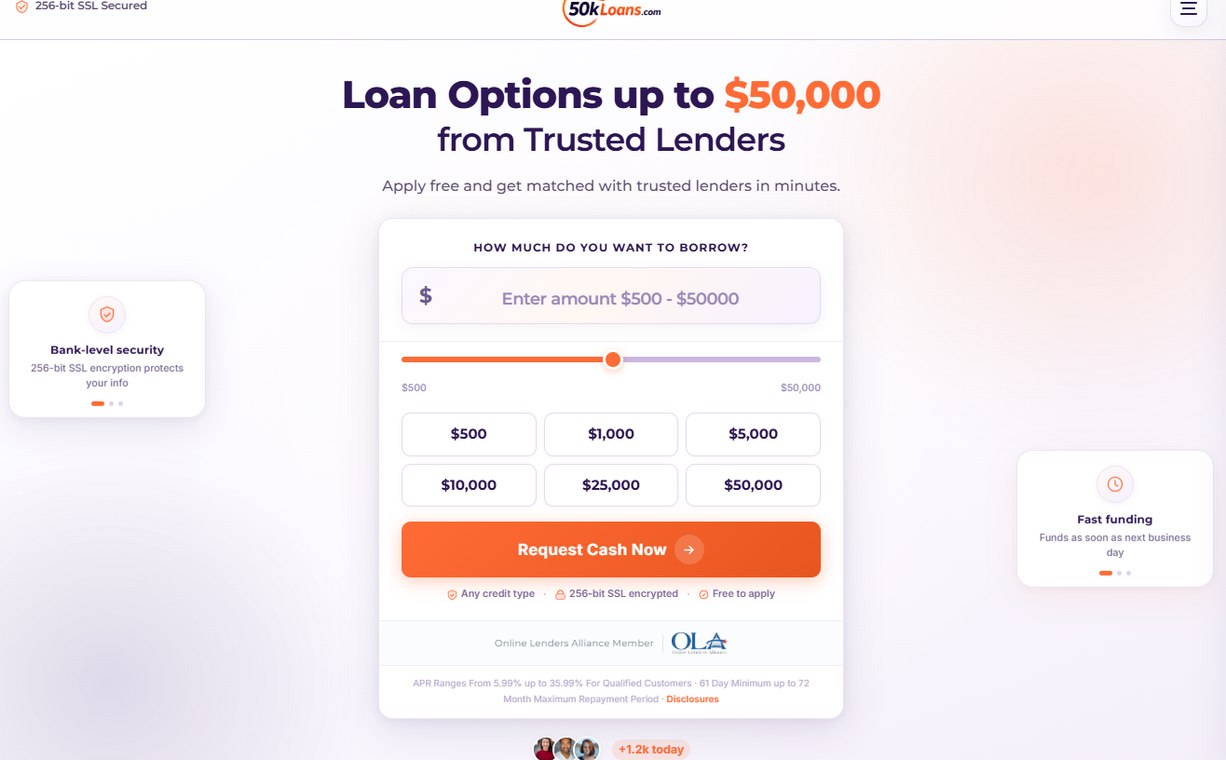
50KLoans is a heavy hitter for those who need significant capital to tackle major life expenses or debt. They offer a wide range of repayment terms, from a 61-day minimum up to a 72-month maximum. This long-term flexibility is essential; a 72-month term significantly lowers the monthly payment, making it much easier to fit into a strict monthly budget, even if the total interest paid over the life of the loan is higher.
The platform is highly secure with 256-bit SSL encryption, ensuring that your sensitive data stays safe while you look for a match. This level of security is comparable to what you would find at a major national bank. They are a great choice for those looking for professional-grade security and high loan caps, especially if you need a lump sum to consolidate multiple high-interest debts into one structured plan.
Pros:
- High loan amounts up to $50,000.
- Flexible repayment periods.
- Fast ACH funding as soon as the next business day.
Cons:
- APR can range as high as 35.99% for some customers.
7. Cash Store
Cash Store offers an alternative to the traditional payday loan cycle through their installment loan products. They serve customers in specific states like Idaho, Texas, and Wisconsin, providing a localized approach to lending. This regional focus often means they are more attuned to state-specific regulations and consumer protection laws, which can be beneficial for the borrower.
With a high customer satisfaction rating, they focus on being a reliable alternative for those who find themselves in a financial squeeze. They are designed for people who want a structured way to borrow cash without the extreme volatility of some payday products. By using an installment structure, you avoid the “debt trap” where you are constantly renewing short-term loans to pay off previous ones.
Pros:
- High customer satisfaction rating.
- Provides installment-based alternatives to payday loans.
- Established presence in several US states.
Cons:
- Availability is restricted to specific geographic locations.
Comparison of Borrowing Scenarios
To better understand which lender fits your specific need, consider the following three common scenarios a borrower with a 520 score might face:
| Scenario | Typical Need | Best Lender Type | Primary Consideration |
|---|---|---|---|
| Emergency Repair | $500 – $1,000 | Payday/Quick Installment | Speed of funding (Same day) |
| Debt Consolidation | $5,000 – $25,000 | Personal Loan/Marketplace | Lower APR and fixed terms |
| Major Life Event | $30,000+ | High-Limit Specialty | Maximum loan ceiling |
The Hidden Costs: APR vs. Monthly Payment
When you are struggling with a 520 score, the temptation is to look only at the “Monthly Payment” amount. If a lender offers you $2,000 with a payment of only $50 a month, it sounds incredibly manageable. However, you must perform the “Total Cost Math.” If that $50 payment lasts for 60 months, you will have paid back $3,000 for a $2,000 loan. That is a 50% increase in the cost of the money you borrowed.
Always ask for the Annual Percentage Rate (APR) and the total repayment amount. The APR includes not just the interest, but also any origination fees, processing costs, or administrative charges. In the subprime market, these “junk fees” can sometimes be as expensive as the interest itself. By calculating the total cost upfront, you can determine if the loan is a temporary bridge or a long-term financial anchor.
Navigating Low Credit Borrowing Without Losing Your Way
Taking out a loan with a 520 score is a double-edged sword. While it can provide the oxygen needed to keep your finances breathing, it can also become a weight that pulls you under if you aren’t careful. Always look at the total cost of the loan, not just the monthly payment. A low monthly payment might hide an APR that makes the loan incredibly expensive over time.
Avoid the temptation to take out multiple loans at once just because you see the “instant approval” signs. Each inquiry can impact your score, and stacking debt is a fast track to a financial spiral. Instead, use these tools strategically to consolidate high-interest debt or cover a specific, necessary expense that will help you get back on your feet. For example, using a high-limit loan to pay off five different late-fee-heavy credit cards might actually result in a net gain for your credit score within three to six months by improving your credit utilization ratio.