
Top 5 Lenders for Emergency Loans for Bad Credit in 2026
Last updated: 2026-11-10
Life has a funny way of throwing curveballs when you least expect them. A sudden transmission failure on the highway or a leaking roof threatening your living room ceiling can blow a hole in a monthly budget overnight. These aren’t planned expenses. They are disruptions that demand immediate cash. When your credit score isn’t exactly stellar—maybe due to an old medical bill or a period of unemployment—finding quick money feels like searching for a needle in a haystack.
Traditional banks often see anyone with a subprime score as a liability. This leads to automatic denials or weeks of paperwork that you simply don’t have time for. This ranking is for people facing urgent hurdles who need to bypass that red tape. When you are staring at an eviction notice or a mechanic’s estimate that exceeds your savings, you don’t need a lecture on credit management. You need capital.
Finding the right lender means balancing speed against the actual cost. It is about finding a lifeline that won’t turn into a heavy anchor for your future finances. Every decision you make during an emergency—from the interest rate you accept to the repayment term you choose—will impact your ability to rebuild your financial standing in the months to follow. You have to pick your battles carefully.
- Acorn Finance
- Max Cash
- FastLendGo
- Jora Credit
- King of Kash
How These Lenders Were Evaluated
Evaluating lenders in the high-risk space requires looking past flashy marketing and “instant approval” banners. The focus stays on accessibility and how fast the money actually hits your hands. When an emergency strikes, waiting ten business days for a decision is simply not an option. A delay in funding can result in late fees on utility bills or higher interest on overdue medical costs, making your problem even bigger.
The comparison looks at how quickly funds hit a bank account and what the application process actually entails. We analyzed the friction points in the digital application journey. How many steps are required before a decision is rendered? Which forms of income are accepted? We also look at specific loan types, like installment options that provide a predictable schedule, or specialized financing for home and auto repairs that might offer more tailored terms.
Our goal was to identify lenders that provide liquidity without requiring an impossible amount of documentation during a crisis. You shouldn’t have to hunt through filing cabinets for every receipt while your car is sitting on a tow truck. We wanted to see who makes the process straightforward for people who are already under significant stress.
| Lender Name | Loan Amounts | Credit Requirements | Funding Speed | Key Feature |
|---|---|---|---|---|
| Acorn Finance | see site | Good & Bad Credit | see site | $0 Dealer Fees |
| Max Cash | $250 – $10,000+ | Bad Credit Loans | Minutes | Multiple Loan Types |
| FastLendGo | $500 – $5,000+ | Bad Credit Friendly | Quick Access | Various Loan Uses |
| Jora Credit | see site | Bad Credit Options | Minutes | Check Disbursement |
| King of Kash | see site | No Credit Check | Lightning Fast | No Collateral |
Ranked Options for Urgent Financing
1. Acorn Finance
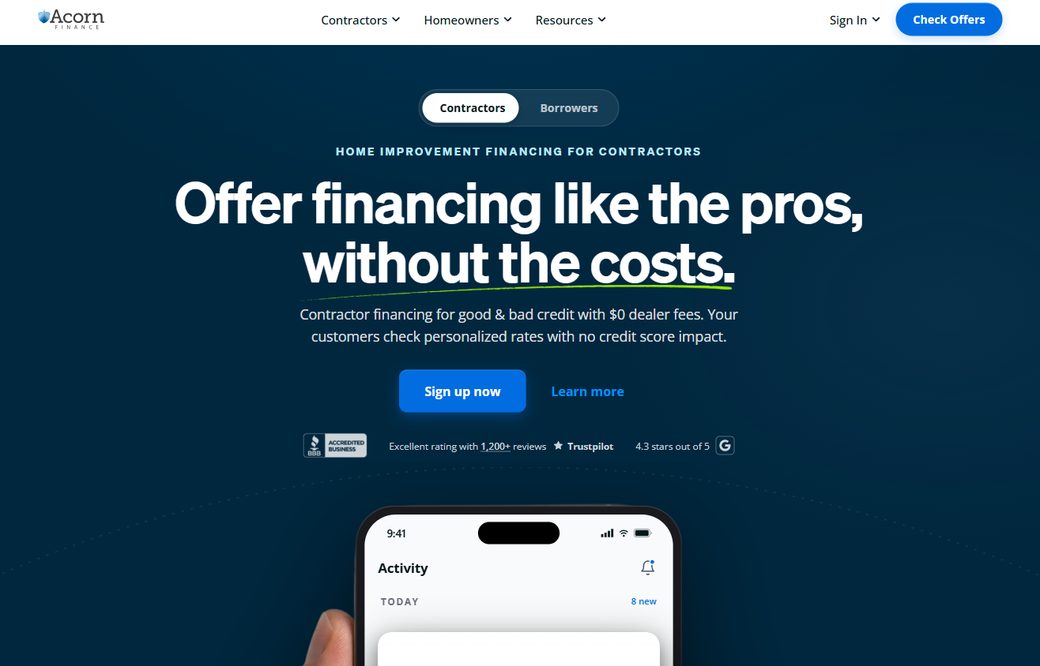
Acorn Finance works as a specialized bridge for those needing to fund significant home projects. They focus heavily on contractor financing. This makes them a standout for anyone facing expensive repairs like pool installations, roof replacements, or kitchen remodels. Unlike a standard personal loan that arrives as a lump sum in your bank account, Acorn often facilitates direct payment to the service provider.
This approach can streamline the renovation process and ensure the funds are used specifically for the intended purpose. The platform is particularly useful because it offers $0 dealer fees for contractors. This is a massive advantage for the consumer. It prevents the “markup” often added to financing to cover the lender’s risk. It keeps more money in your pocket where it belongs.
You can check personalized rates without a hard inquiry, which means your credit score won’t take a hit just for looking at your options. This “soft pull” approach is essential for those who are shopping around for the best possible rate in a high-interest environment. It gives you the freedom to browse without any penalty.
Pros:
- No impact to credit score when checking rates
- $0 dealer fees for contractor financing
- High user ratings on Trustpilot
Cons:
- Focus is heavily weighted toward home improvement
2. Max Cash
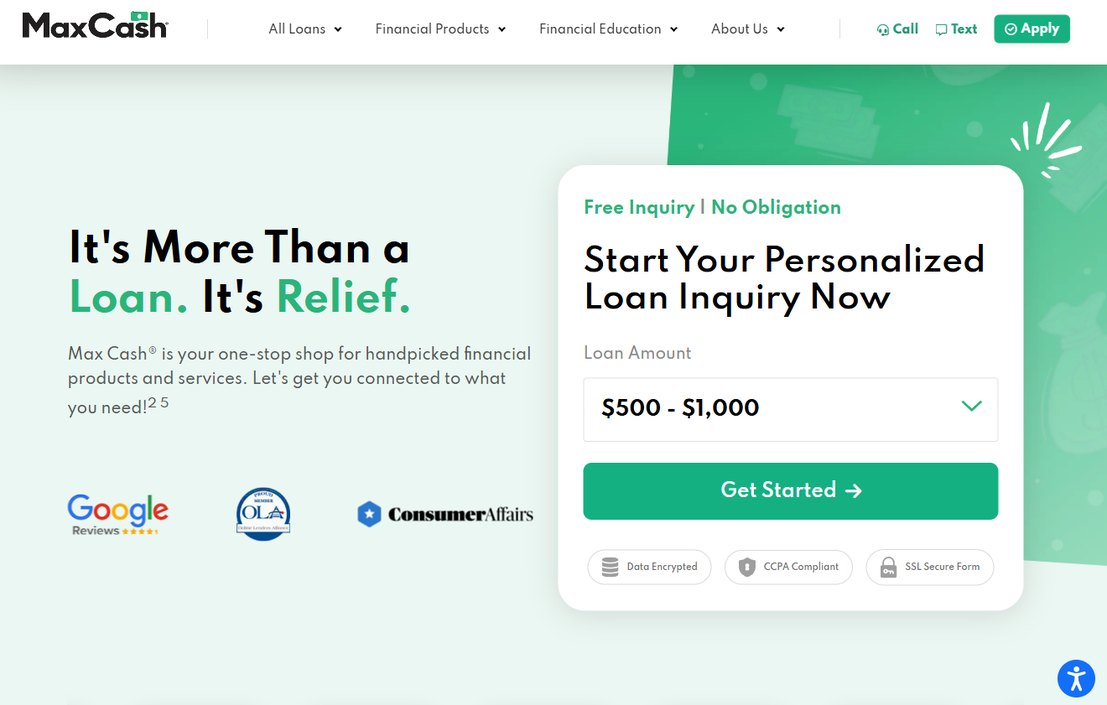
Max Cash acts as a versatile one-stop shop for various financial needs. Whether you need a small cash advance to cover a grocery bill or a larger installment loan to fix a vehicle, they offer a wide spectrum of products. You can find amounts ranging from $250 up to $10,000 or more. This flexibility works well for households with fluctuating incomes.
This lender is built for speed and variety. They provide options for title loans, personal loans, and even car insurance financing. For example, if your car insurance premium is due and you cannot pay it in full, a specialized financing option might be more manageable than a standard high-interest personal loan. It’s a solid choice for someone who isn’t sure exactly which tool they need yet.
If you know you need capital immediately but haven’t decided on the exact amount or type, Max Cash covers the bases. They offer a range of solutions that can help you manage different types of emergencies without jumping between multiple different lenders.
Pros:
- Extremely wide range of loan amounts
- Available 24/7 for inquiries
- Covers diverse needs like car and title loans
Cons:
- The variety of products can be overwhelming
3. FastLendGo
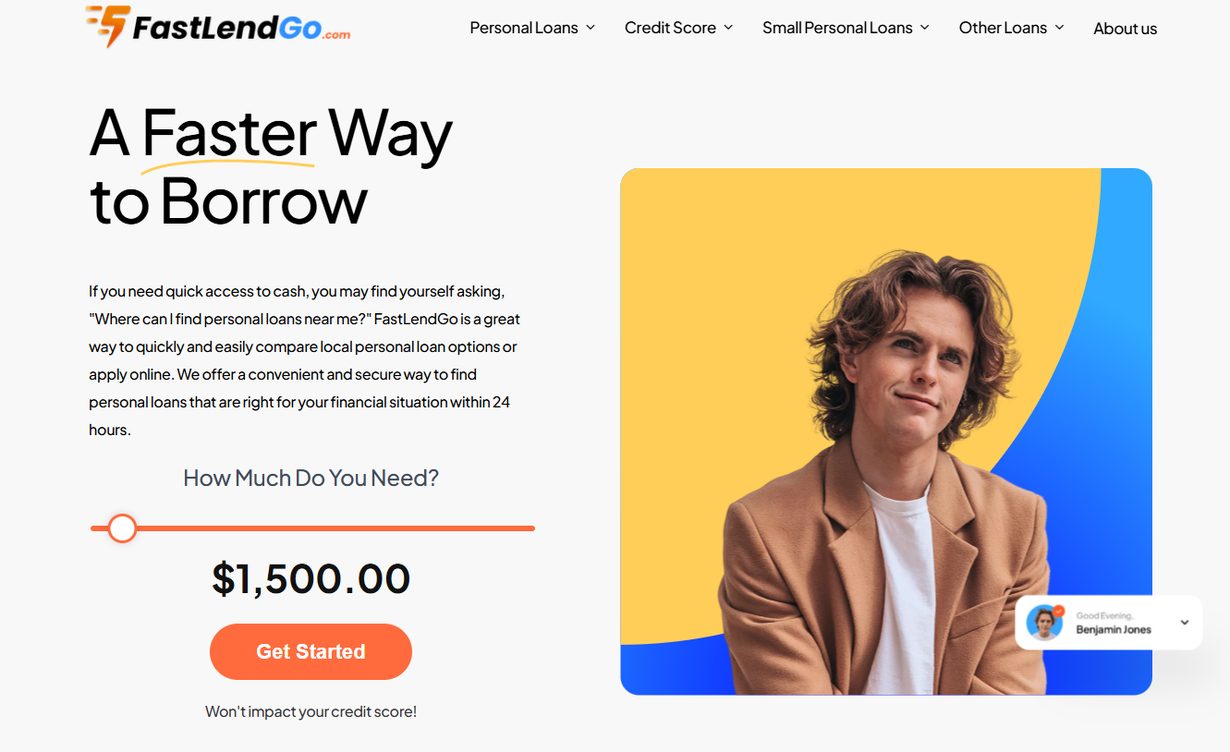
FastLendGo is a nimble player in the personal financing market. They specialize in getting people through tight spots, offering everything from $500 small loans to larger personal loans for high-income individuals. Their product suite is designed to bridge the gap between micro-loans and traditional long-term debt. They are ideal for “mid-tier” emergencies where a payday loan is too small and a bank loan is too slow.
If you are staring at a broken car or an urgent dental bill, this lender is designed for that exact scenario. They cater to various credit tiers, including those with bad credit or those looking for loans with no credit history. They understand that life doesn’t wait for your credit score to improve.
For instance, if you need an immediate $1,200 to fix a transmission to get to work, FastLendGo’s streamlined application process is built to address that specific urgency. You won’t have to deal with the bureaucratic hurdles that usually come with a major institution. It is built for the moment when you just need things to work.
Pros:
- Specific options for auto and dental repairs
- Supports various credit scores
- User-friendly online comparison
Cons:
- Requires a specific state-by-state availability
4. Jora Credit
Jora Credit focuses on simplicity and directness. They are a state-licensed direct lender that specializes in installment loans for those with less-than-perfect credit histories. Unlike many “marketplace” lenders that simply pass your information to a third party, Jora Credit operates with a direct lender structure. This can lead to faster decision-making and clearer terms from the start.
Their application process is stripped down to the bare essentials. They focus on your income and your ability to repay, rather than dwelling solely on your FICO score. One unique aspect of their service is the ability to receive funds via check. This is a helpful alternative if you prefer physical cash or need to deposit a check directly into a bank account.
This is particularly useful for those who don’t have a modern digital banking setup or who simply prefer the tangible nature of a check. It removes a layer of digital complexity that can be frustrating when you are already dealing with a financial crisis. It is a straightforward way to get the money you need.
Pros:
- Fast decision-making within minutes
- Option to receive funds by check
- Direct lender structure
Cons:
- Check disbursement may be slower than digital transfers
5. King of Kash
King of Kash targets the most urgent, “need it now” scenarios. Their main selling point is a loan process based on your ability to repay rather than a traditional credit score check. This makes them a last resort for many. However, for those who have been denied by every other source, they offer a path to liquidity when all other doors have closed.
They focus on cash flow and income stability rather than your history with debt. They emphasize lightning-fast approval and no requirement for collateral. This distinguishes them from title loans, where you must hand over the deed to your car. With King of Kash, you are not putting your physical assets at immediate risk of repossession in the same way.
If you need cash deposited into your account within one business day to prevent a catastrophic utility shut-off, they are designed to move at the speed of an emergency. It is about getting through the immediate crisis so you can breathe again. They are the go-to when the clock is ticking loudly.
Pros:
- No traditional credit check required
- No collateral needed to secure loans
- Rapid one-day funding after approval
Cons:
- No credit checks often come with higher costs
Understanding the True Cost of High-Risk Loans
Before you sign any agreement, it is vital to look at the fine print. High-risk lending is a trade-off. You are paying for the speed and the lack of stringent requirements. When a lender offers “no credit check,” they are often shifting the risk onto the interest rate. This means the cost of borrowing can be significantly higher than a standard bank loan.
You must calculate the Total Cost of Borrowing (TCB), which includes the principal amount plus all interest and fees. This shows you if the loan is truly affordable or if it will trap you. Don’t just look at the number you receive in your bank account; look at what you have to pay back to get it.
Consider these three specific metrics when reviewing a loan offer:
- APR (Annual Percentage Rate): This is the most important number. It includes not just the interest, but also any origination fees or service charges. A 30% interest rate is very different from a 30% APR.
- Repayment Term: A shorter term means higher monthly payments but less total interest paid. A longer term makes monthly payments easier but can lead to you paying back double or triple what you borrowed.
- Origination Fees: Some lenders deduct a fee directly from your loan amount. If you borrow $1,000 but a $100 fee is deducted, you only receive $900, but you still owe interest on the full $1,000.
Strategies for Responsible Emergency Borrowing
While these lenders provide a vital lifeline, using them requires a disciplined approach to prevent a cycle of debt. The goal is to use the loan to solve the emergency, not to fund a lifestyle that exceeds your means. Follow these steps to manage your emergency funds effectively and keep your finances on track.
- Define the Minimum Requirement: Before applying, determine the absolute minimum amount you need to solve the crisis. If a car repair costs $850, do not take out a $1,200 loan “just in case.” That extra $350 is money you will be paying interest on for months.
- Compare the “Total Cost” Not the “Monthly Payment”: Lenders will often try to win you over with a low monthly payment. However, a low payment usually means a much longer loan term. Always ask, “How much will I have paid back in total by the end of this loan?”
- Verify State Licensing: Always ensure the lender is licensed in your specific state. Regulations regarding interest rate caps and collection practices vary wildly. Using an unlicensed lender can leave you with very little legal recourse if something goes wrong.
- Create a Repayment Buffer: Once the emergency has passed and you have received your funds, immediately adjust your budget to accommodate the new loan payment. Treat the loan payment as a non-negotiable utility bill.
Finally, remember that an emergency loan should be a temporary bridge, not a permanent solution. Use this liquidity to stabilize your situation, but once the immediate threat has passed—be it the leaky roof or the broken car—shift your focus toward building an emergency fund. This will prevent you from needing high-risk lenders in the future. Take a breath, compare the options, and choose the path that is most sustainable for your budget.