
Top 5 Lenders for Bad Credit Loans in California: 2026 Rankings
Last updated: 2026-11-10
Managing money in California often feels like swimming against a heavy tide. If your credit score isn’t a glowing beacon of stability, the struggle is real. Many residents find themselves staring at unexpected medical bills or sudden car repairs, wondering if any lender will even look their way without a perfect history.
In a state where the cost of living hits some of the highest levels in the nation, a single broken transmission or an urgent dental procedure can throw a household budget into a tailspin. When these emergencies arise, the standard banking system often feels like a fortress designed to keep people out rather than a service meant to help them in.
Finding a lifeline shouldn’t be a game of chance or a series of closed doors. This list focuses on lenders that prioritize actual eligibility over just looking at a number. These platforms help Californians find the liquidity they need to keep their lives moving forward without unnecessary stress.
We aim to highlight the difference between immediate financial necessity and long-term stability. By identifying platforms that understand the nuances of modern credit profiles, you can make a more informed choice for your specific situation.
- CreditNinja
- GreendayOnline
- FastLoans CA
- Addition Financial
- OppLoans
Evaluating California’s Alternative Lending Options
To compile this list, we weighed several factors to determine which lenders actually provide relief versus those that just offer high-interest traps. We looked at how quickly a person could see money in their bank account after hitting the submit button on an application.
In the fast-paced economy of cities like Los Angeles or San Francisco, waiting five to seven business days for a wire transfer is rarely an option. You need funds when the bill is due, not when the bank’s processing cycle eventually catches up. Speed is often the name of the game when an emergency strikes.
We also scrutinized whether applying for these loans would leave a permanent scar on a credit report. Many people in a pinch cannot afford to lower their scores even further during the search. A “hard inquiry” can drop a score by several points instantly. This can be devastating if you are simultaneously trying to refinance a mortgage or apply for a new apartment lease.
Because of this, we prioritized lenders that utilize “soft pulls” for the initial qualification phase. This allows you to shop around without penalty. Furthermore, we evaluated the transparency of the terms. Many predatory lenders hide their true Annual Percentage Rate (APR) behind complex fee structures or “origination costs” that are deducted from the principal before you even see the money.
We focused on lenders that provide clear, upfront information regarding the total cost of borrowing. This way, you aren’t surprised by the final amount you have to pay back.
| Lender Name | Loan Amounts | Funding Speed | Credit Impact | Key Feature |
|---|---|---|---|---|
| CreditNinja | Up to $5,000 | Same Day* | Score not the only factor | Quick online application |
| GreendayOnline | $100 – $5,000 | As soon as same day | No hard credit checks | No credit check options |
| FastLoans CA | $1,000 – $35,000 | As soon as 24 hours | No hard credit pull | Rates as low as 3.5% |
| Addition Financial | Up to $5,000 | See site | See site | Credit Union benefits |
| OppLoans | See site | Same-day funding available | Does not affect FICO score | Installment loan options |
Top Ranked Lenders for California Residents
1. CreditNinja
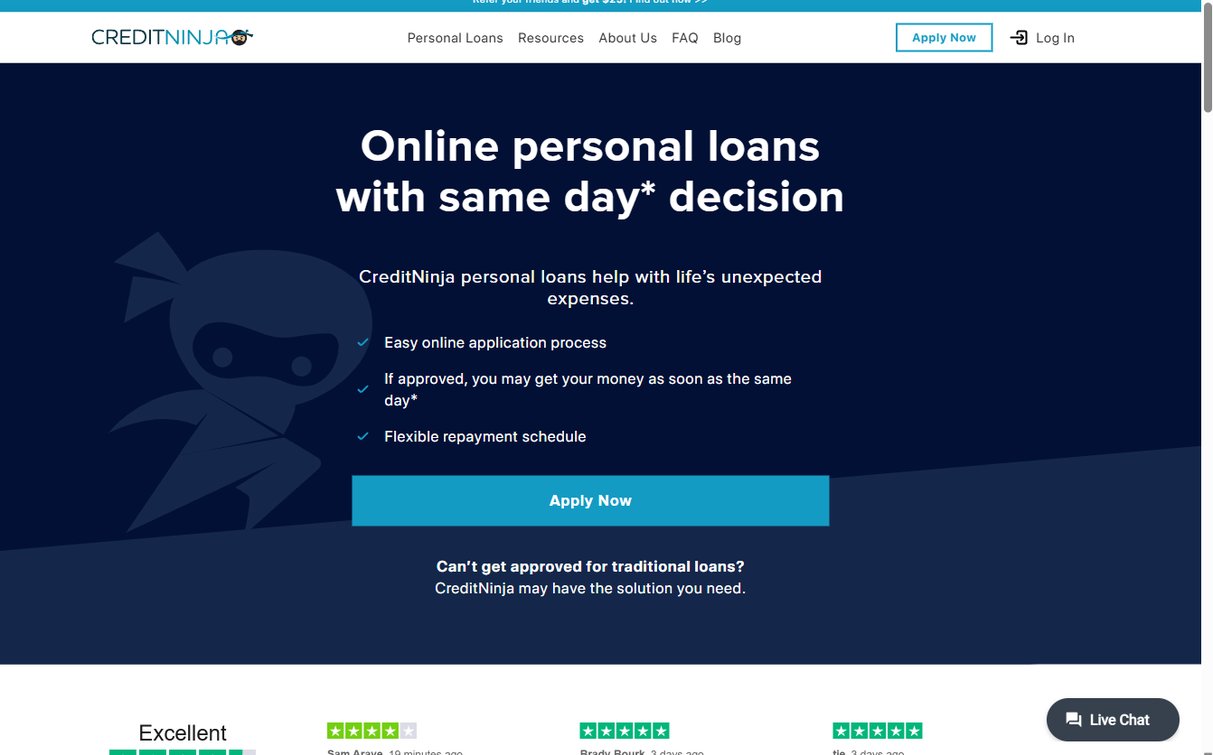
CreditNinja operates as a streamlined bridge for those who might find traditional bank doors firmly shut. Their system is designed to look beyond a single numerical score. This is a breath of fresh air for anyone struggling with a rocky financial past.
Instead of relying solely on a FICO number, their algorithm often looks at alternative data points. They might check your steady employment history or your recent banking activity to determine your ability to repay a loan. The application process is incredibly lean, requiring only basic information to get the gears turning.
You typically won’t need to dig up years of tax returns just to see if you qualify. A simple digital form handles the heavy lifting. If you find yourself in a tight spot where a quick decision is the difference between peace and panic, this platform’s speed is a significant advantage.
Because they act as a marketplace, they can quickly scan multiple lenders to find the one most likely to approve your specific profile.
Pros:
- Fast, simple online application process.
- Potential for same-day money deposit.
- Considers more than just your credit score.
Cons:
- Approval is not guaranteed.
2. GreendayOnline
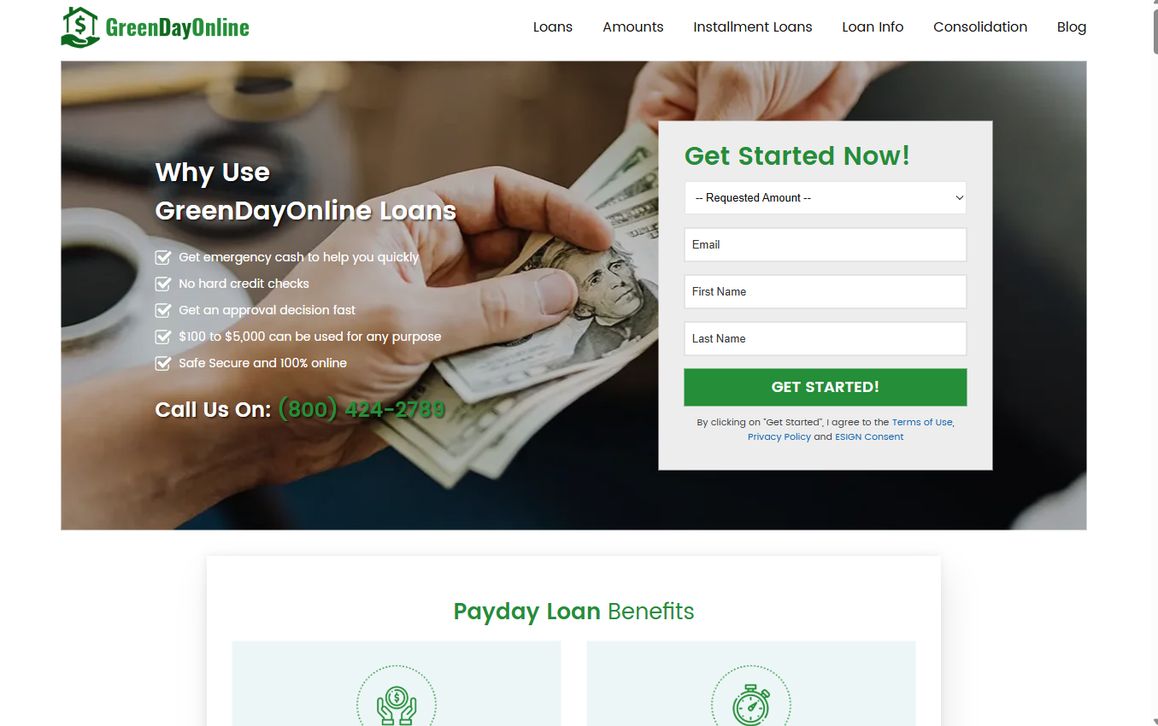
When you need a small amount of cash to cover an immediate gap, GreendayOnline steps up to the plate. They specialize in smaller, manageable amounts that can be used for just about anything. This makes them a versatile tool for sudden emergencies.
Whether it’s a quick grocery run to bridge the gap until payday or a minor utility bill that is past due, their micro-loan approach is built for these specific moments. They remove the heavy barrier of the hard credit check, which is a massive relief for those trying to protect their standing.
This means you can check your eligibility without any risk to your credit score. With a wide range of amounts available, you can tailor the request to exactly what your situation demands. You can avoid the mistake of over-borrowing by choosing only what you need.
This flexibility is key for maintaining a tight budget in high-cost areas like San Diego or Sacramento.
Pros:
- No hard credit checks for approval.
- Loan amounts range from $100 to $5,000.
- Extremely fast approval decisions.
Cons:
- Primarily focuses on smaller, short-term amounts.
3. FastLoans CA
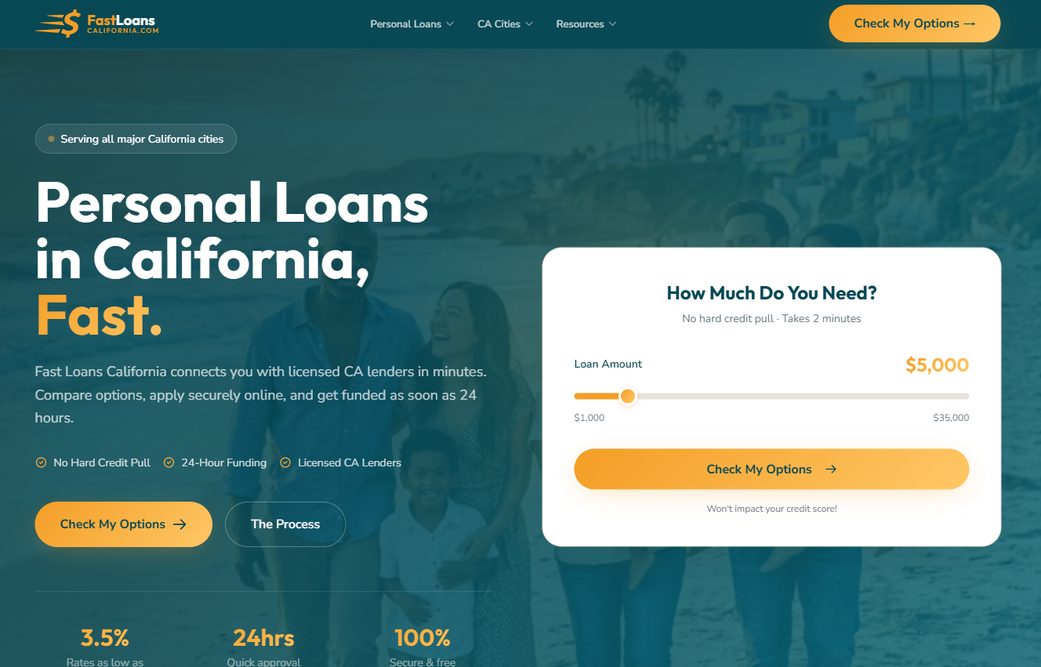
FastLoans CA is a powerhouse for Californians who need significant capital without the traditional headache. They connect users with licensed lenders across the state. This ensures the process remains legal and secure for every single applicant.
This is particularly important in California, where lending regulations are strict and consumer protection is paramount. By working with a network of providers, they can offer a variety of terms that a single local bank might not be able to match. (fastloanscalifornia.com)
What sets them apart is the ability to access much larger sums, reaching up to $35,000 in some cases. This makes them a viable option for major life expenses rather than just minor monthly gaps. Imagine needing to repair a roof before the rainy season starts.
Or perhaps you need to pay for an unexpected tuition increase for a child. For these larger hurdles, a $500 micro-loan won’t cut it. You need the heavy-duty support that a high-limit lender provides.
Pros:
- High maximum loan amounts up to $35,000.
- No hard credit pull during the initial check.
- Serves a vast network of California families.
Cons:
- Higher amount loans may require more documentation.
4. Addition Financial
Addition Financial offers a different flavor of lending through the credit union model. This approach often feels more like a partnership than a transaction. It provides a sense of community that many traditional banks lack entirely.
Because credit unions are member-owned cooperatives, their primary motivation is to serve the members rather than maximizing shareholder profits. This often translates to better interest rates and more personalized service. They offer various products, from checking accounts to savings.
This allows for a more holistic approach to managing your money. If you are looking to move away from the “paycheck-to-paycheck” cycle, building a relationship with a credit union can provide you with more tools. You might find automated savings features or low-cost overdraft protection.
It is a great choice for those looking to build a long-term financial relationship. Eventually, you might graduate to traditional, low-interest personal loans or mortgages.
Pros:
- Competitive rates for various banking needs.
- Access to diverse financial products.
- Credit union membership benefits.
Cons:
- May require membership or specific eligibility.
5. OppLoans
OppLoans focuses on the concept of the installment loan, which can be a much more manageable way to repay debt. Unlike a payday loan, where you might owe a massive lump sum in two weeks, an installment loan spreads the repayment over several months.
By breaking the total amount into scheduled payments, the immediate burden on your wallet is significantly lessened. This makes it much easier to incorporate the debt into your monthly budget. Their platform is built to be user-friendly, often providing decisions in a matter of minutes.
It is a reliable fallback for those who have been turned down elsewhere but still need to move forward with their lives. For many, the primary concern is the predictability of the repayment schedule.
OppLoans provides that structure. You won’t be constantly guessing how much cash you’ll need for the next installment.
Pros:
- Applying does not affect your FICO score.
- Same-day funding is often available.
- No hidden fees in the process.
Cons:
- Terms may be more expensive than traditional loans.
Comparing Loan Types: Installment vs. Revolving Credit
Understanding the mechanics of how you are paying back your money is just as important as knowing how much you are borrowing. Most people encounter two main types of lending: installment loans and revolving credit. Knowing which is which can prevent a lot of confusion.
An installment loan, like those offered by OppLoans, gives you a lump sum upfront. You pay it back in fixed amounts over a set period. This is ideal for a specific expense, like a car repair, because you know exactly when the debt will be gone.
On the other hand, revolving credit—like a credit card—gives you a limit you can use repeatedly. While flexible, revolving credit can be dangerous if you only pay the “minimum amount due.” Interest compounds against the balance, often leading to a cycle of debt that lasts years.
| Feature | Installment Loan | Revolving Credit |
|---|---|---|
| Repayment Structure | Fixed monthly payments | Variable payments based on balance |
| Total Interest Cost | Predictable and set at start | Fluctuates based on usage and APR |
| Best Use Case | One-time emergency expenses | Ongoing monthly expenses |
Navigating the Borrowing Process Wisely
Before signing any digital paperwork, it is vital to look at the fine print. Every loan comes with a cost, usually expressed as an interest rate. You must ensure you can meet the repayment schedule without falling into a cycle of debt.
A common tactic used by lenders is to emphasize the “monthly payment” amount because it looks small and affordable. However, you must always look at the total sum of all payments over the life of the loan. A small monthly payment can mask a very high total cost if the term is extended too long.
Avoid the trap of borrowing more than you absolutely need just because a lender offers it. It might feel like extra cushion today, but that extra cash is essentially a weight around your neck in the months to come. If you need $400 to fix a tire, do not take out a $1,000 loan just because the approval was easy.
That extra $600 is money you will be paying interest on for months. You are effectively turning a small problem into a long-term financial burden. Another common mistake is ignoring the impact of different types of inquiries.
While some lenders offer “soft pulls” that won’t hurt your score, others might use “hard pulls” that can cause a temporary dip. Know which one you are dealing with before you hit that “apply” button. Additionally, always confirm the method of repayment.
In California, many lenders require automatic ACH withdrawals from your bank account. Ensure your income arrives in that account at least two days before the loan payment is scheduled. This prevents overdraft fees, which can quickly double the cost of your loan.