
The 5 Best Personal Loans in Connecticut for 2026
Last updated: 2026-11-10
Managing money in Connecticut often feels like driving through a thick fog on I-95. When an unexpected car repair or a medical bill lands on your kitchen table, the need for quick cash becomes an immediate priority. Whether you are dealing with a sudden HVAC failure in a drafty New Haven apartment or an urgent dental procedure in Hartford, the stress of finding reliable capital can be overwhelming.
Finding the right lender involves more than just looking at the lowest interest rate. It requires a careful look at speed, accessibility for various credit tiers, and the flexibility of terms to ensure the repayment schedule doesn’t become a heavy burden later on. In a state with a diverse economy, from high-tech corridors to manufacturing hubs, your financial needs can vary wildly, and your lending options should be just as versatile.
- NetCredit
- JetzLoan
- Max Cash
- OppLoans
- OneMain Financial
Evaluating Financial Lenders Across Connecticut
To create this ranking, we weighed several factors to ensure the results remain practical for everyday Connecticutans. Speed of funding was a primary metric because emergencies rarely wait for a standard five-day processing window. We looked at how quickly cash hits a bank account, specifically looking for lenders that utilize ACH transfers or debit card funding to bypass the slower mail-in or check-based methods.
Accessibility for those with less-than-perfect credit was also a crucial pillar. Since many people seek loans specifically to bridge a gap caused by previous financial hurdles, the ability to qualify without a devastating credit pull was vital. We prioritized transparency and ease of use, ensuring that the comparison process itself doesn’t cause more financial anxiety.
We also analyzed the “Total Cost of Credit.” This involves looking beyond the monthly payment to understand the impact of the Annual Percentage Rate (APR) over the entire life of the loan. A low monthly payment might look attractive on the surface, but if the term is extended to 72 months, the total interest paid could eclipse the original principal. Our evaluation focused on lenders that offer clear, upfront disclosure of these costs before you commit to a hard inquiry.
| Lender Name | Loan Amount | Funding Speed | Credit Impact |
|---|---|---|---|
| NetCredit | Up to $10,000 | Same-day available | No impact to check |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Max Cash | $250 – $10,000+ | In minutes | See site |
| OppLoans | See site | Same-day available | No impact to check |
| OneMain Financial | $1,500 – $35,000 | As soon as 1 hour | No obligation to check |
Top-Rated Personal Loan Options in Connecticut
1. NetCredit
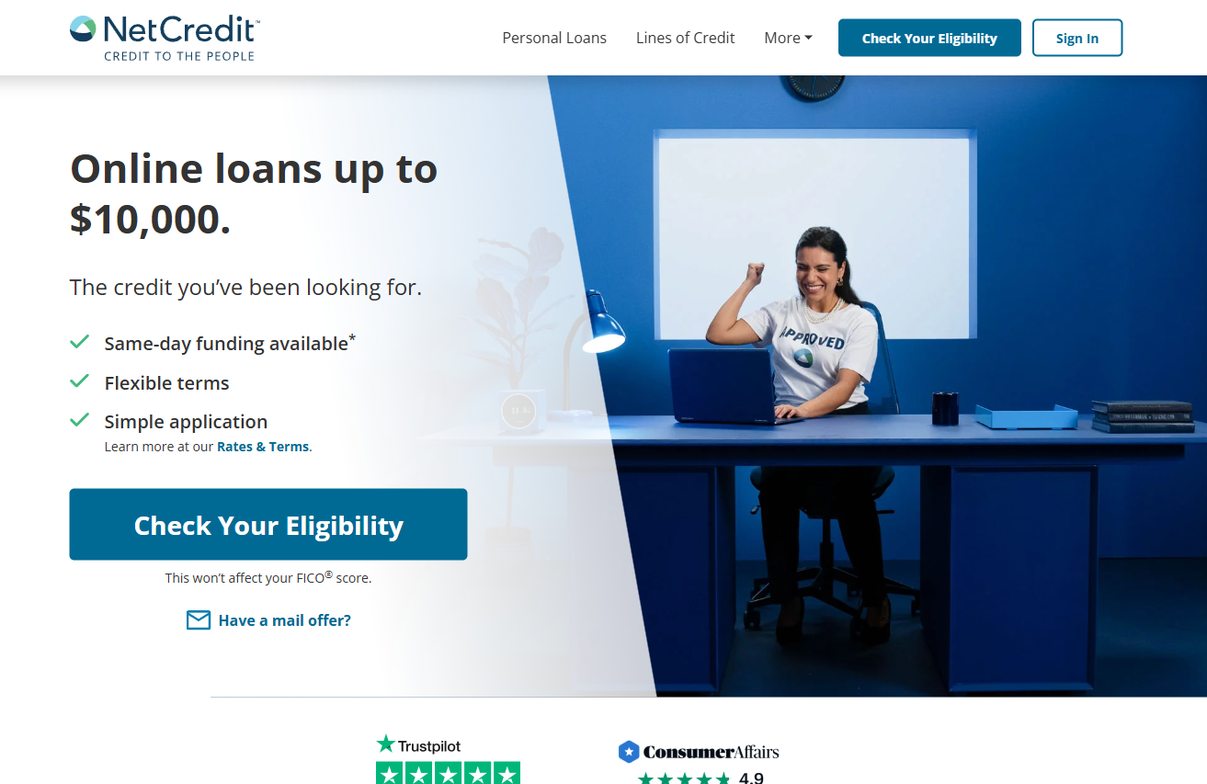
NetCredit approaches lending with a philosophy that a person is much more than a single number in a database. By using advanced algorithms, they look beyond a basic credit score to find a financing solution that actually fits an individual’s specific financial profile. This often includes looking at alternative data such as employment stability, income consistency, and even banking history, which provides a more holistic view of your ability to repay.
This lender is an excellent choice for those who need a moderate amount of capital, such as up to $10,000, to handle various expenses. They offer flexible terms and the possibility of same-day funding, which is a lifesaver when the timing is critical. For example, if you are facing a sudden $4,000 repair on your vehicle, NetCredit’s ability to assess your profile without a hard credit pull allows you to shop around without fear of dropping your score just before a major purchase like a mortgage or car loan.
Pros:- Advanced algorithms consider more than just a credit score.
- Same-day funding is available for many applicants.
- Checking eligibility does not affect your FICO score.
- Maximum loan amounts are capped at $10,000.
2. JetzLoan
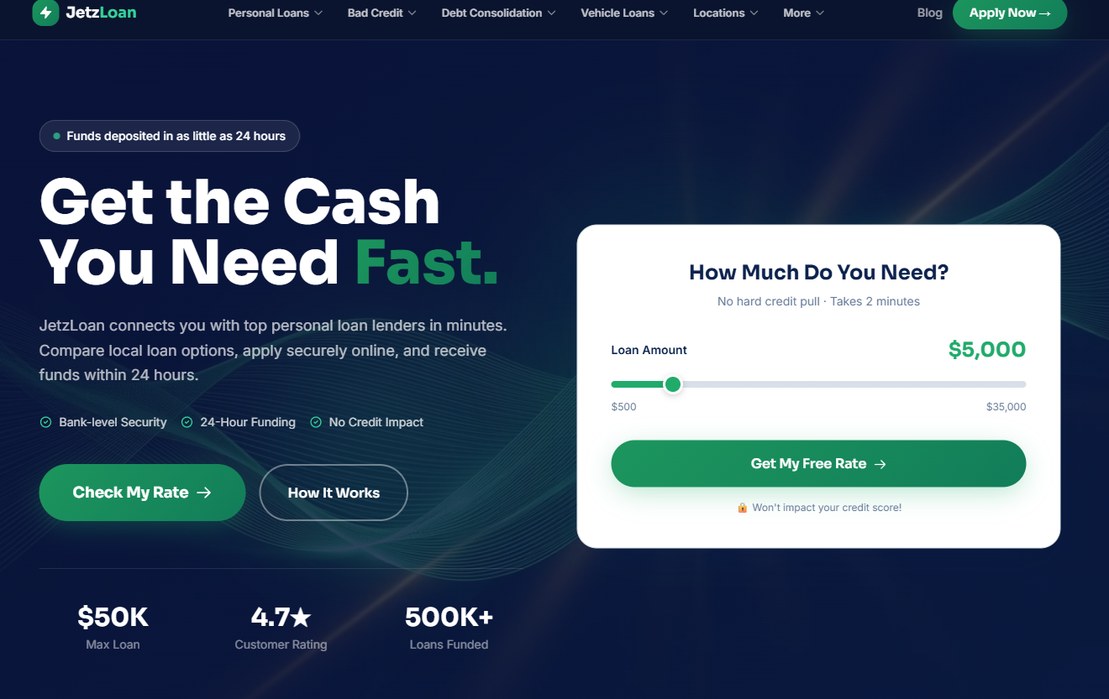
JetzLoan acts as a high-speed bridge between borrowers and top personal loan lenders. Their process is designed for efficiency, allowing users to compare local options and apply securely in just a couple of minutes without any immediate impact on their credit. This marketplace-style approach is ideal for Connecticut residents who are time-constrained and want to see a wide array of competitive offers in one sitting.
With a maximum loan amount reaching $35,000, this option serves a wide variety of needs, from small cash injections to larger debt consolidation efforts. If you are looking to consolidate high-interest credit card debt from several different banks into a single, manageable monthly payment, a $30,000 loan from a provider through JetzLoan could significantly lower your interest burden and simplify your financial life.
Pros:- High maximum loan amount of $35,000.
- Very fast 24-hour funding window.
- No hard credit pull during the initial check.
- The application process requires a simple form that may require several minutes of focus.
3. Max Cash
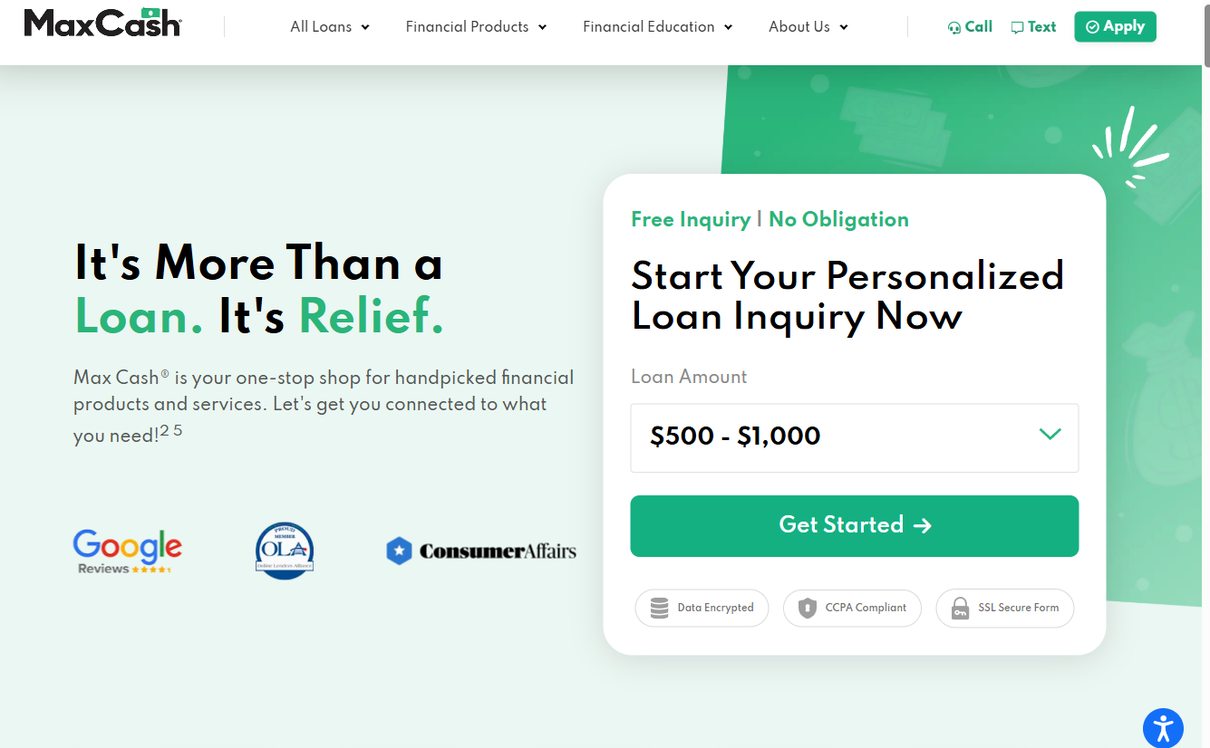
Max Cash positions itself as a versatile one-stop shop for a wide array of financial products. Whether you are looking for a small installment loan or a larger personal loan, they aim to connect users with the specific relief they need. Their platform is built to cater to the “micro-loan” market as well as those seeking more traditional personal financing.
They are particularly useful for those needing very small amounts, starting as low as $250. This makes them a practical option for quick, short-term needs where a massive loan isn’t necessary, but immediate access to cash is paramount. For instance, if a utility bill is due and you are waiting for your next paycheck in three days, a small cash advance can prevent late fees and service interruptions without the commitment of a long-term loan.
Pros:- Very low minimum loan amount of $250.
- Offers a variety of products including title loans and cash advances.
- Fast processing designed to happen in minutes.
- The range of products can be overwhelming and may lead to higher costs.
4. OppLoans
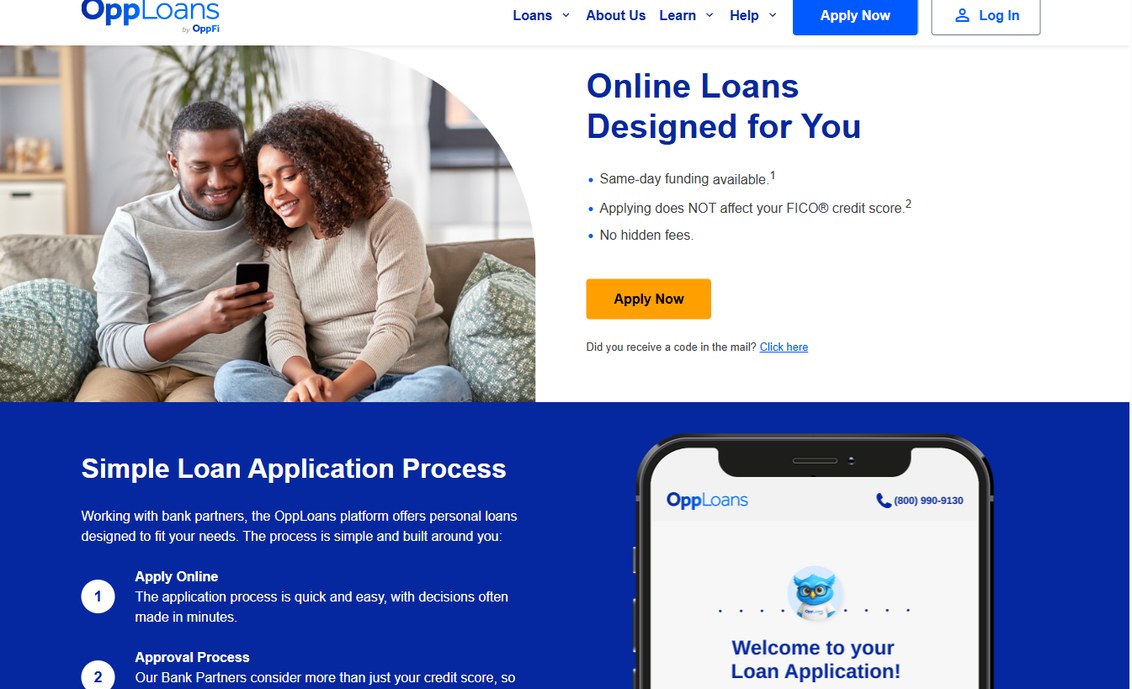
OppLoans is a specialized option for those who might have been turned down by traditional banks. They work with bank partners to look at the whole person, making them a strong contender for people with poor credit seeking same-day funding. While traditional institutions might see a low FICO score as a total disqualifier, OppLoans looks at your current ability to manage cash flow.
The platform is built for simplicity, with a quick application process where decisions are often made within minutes. If approved, the money can arrive in your account as quickly as the same business day, providing immediate breathing room. This is particularly useful during “life happens” moments—such as an emergency medical bill that cannot wait for a bank’s standard underwriting period.
Pros:- Designed specifically for people with poor credit.
- Decisions are often made within minutes.
- Same-day funding is a strong possibility.
- The platform focuses on high-risk lending which can be more expensive.
5. OneMain Financial
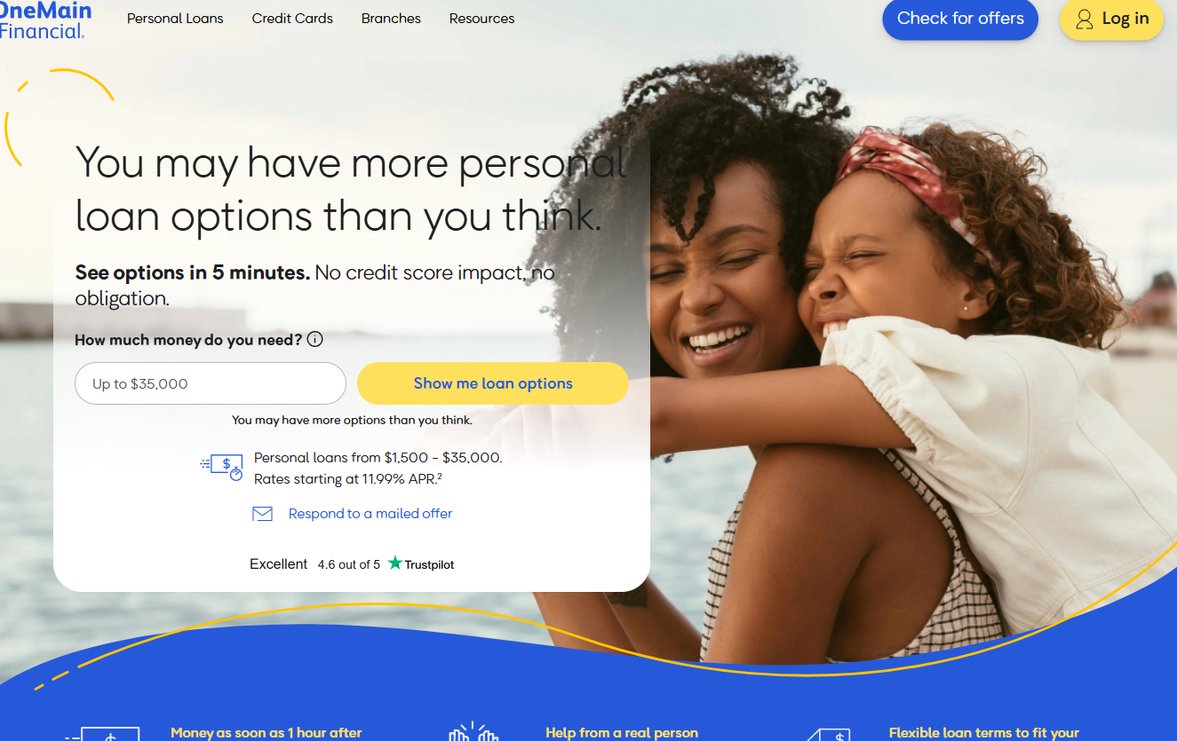
OneMain Financial offers a more traditional, high-touch experience. They provide the convenience of online applications alongside the stability of having over 1,300 physical branches where you can speak to a real person about your financial needs. For many residents, having the option to walk into a local office in cities like Stamford or Waterbury provides a sense of security and personalized service that purely digital lenders cannot match.
With loan amounts reaching up to $35,000 and rates starting at 11.99% APR, they offer a robust middle ground. They are particularly effective for those who have a steady job and can provide proof of income, such as recent pay stubs, which can help secure more favorable terms. For those who need funds quickly, money can be available as soon as one hour after the loan is signed.
Pros:- Access to physical branches for in-person help.
- Fast funding, potentially within one hour of signing.
- Flexible terms from 24 to 60 months.
- Interest rates may vary significantly based on creditworthiness.
How to Choose the Best Loan for Your Specific Need
Not every loan is created equal, and choosing the wrong one can lead to a cycle of debt. To make an informed decision, you must first categorize your need. Are you looking for debt consolidation, home improvement, or emergency liquidity? Each of these has a different optimal structure.
- Debt Consolidation: If your goal is to combine multiple high-interest debts, look for the largest possible loan amount with the lowest possible APR. A higher principal might seem daunting, but if it replaces five different credit cards with 22% interest with a single loan at 12% interest, your monthly cash flow improves significantly.
- Home Improvement: For projects like a new roof or kitchen renovation, consider longer-term loans. You want a lender that offers a fixed interest rate so your payments don’t fluctuate with the market.
- Emergency Liquidity: For a sudden car repair, speed is the priority. In this case, you might sacrifice a slightly higher interest rate for the guarantee that the funds will be in your account within 24 hours.
When comparing lenders, create a simple comparison sheet. Note the APR, the total interest you will pay over the life of the loan, and the presence of any “hidden” fees. A lender might advertise a “low monthly payment,” but if that payment is spread over 60 months instead of 36, you could end up paying nearly double the cost of the original loan. Always prioritize the Total Cost of Borrowing over the Monthly Payment Amount.
Navigating the Loan Process Wisely
Before signing any agreement, it is vital to look at the total cost of borrowing. While a quick loan sounds tempting, always check the annual percentage rate to ensure the monthly payments are sustainable for your budget long-term. A common mistake is calculating your budget based only on what you can afford *today*, without accounting for future inflation or changes in your household expenses.
One common mistake is rushing into a loan to cover a debt that will only grow if the interest is too high. For example, using a high-interest payday-style loan to pay off a credit card might provide temporary relief, but if the interest rate on the new loan is 30% or higher, you are simply moving the debt from one bucket to a more expensive one. Always compare different options and check your eligibility with multiple lenders to see who offers the best terms for your specific situation.
Another pitfall is ignoring the fine print regarding late fees or prepayment penalties. Some lenders actually penalize you for being responsible—if you come into a tax refund and try to pay the loan off early, they may charge a “prepayment penalty” to make up for the interest they are losing. Ensure the lender doesn’t charge you extra for being responsible; look for “no prepayment penalty” clauses in your contract.
Finally, remember that your credit score is a living thing. Using loans to consolidate debt and then paying them off systematically can be a powerful tool to boost your credit score over time, making future borrowing (like a mortgage) much cheaper. However, this only works if the repayment schedule is handled with discipline and consistency. Set up autopayments if possible to ensure you never miss a due date, as a single late payment can negate all the benefits of the loan.