
Top 5 Lenders for Roof Financing: 2026 Rankings
Last updated: 2026-11-10
A leaking roof is more than a minor nuisance; it is a countdown for your home’s structural health. When storms roll in, the last thing a homeowner wants to face is a massive, unexpected bill that drains their monthly savings. Water infiltration often leads to much more expensive problems, like mold in your insulation, warped drywall, or rotting wooden trusses.
Finding a way to pay for these urgent repairs can feel like searching for a needle in a haystack. This selection focuses on lenders providing the liquidity needed to secure a new roof without breaking the bank. Whether you have a stellar credit history or a lower score, a path forward exists. The right choice depends on your timeline, the total project cost, and the interest you can stomach.
A simple shingle repair might only require $2,000. Conversely, a full slate or metal roof replacement for a large estate can easily exceed $40,000. Your choice of lender must align with the scale of your architectural needs. You need to match the loan amount to the reality of the job at hand.
- 50KLoans
- Lower
- FastLendGo
- OppLoans
- LoanStart
How These Roof Financing Lenders Were Evaluated
The selection process involved looking closely at how quickly funds reach a bank account. When a roof is compromised, time is of the essence. A lender that takes weeks to process an application might be useless if the rain is already coming through the ceiling. Slow approval processes can lead to “emergency” pricing from contractors who know you are desperate.
We prioritized lenders that offer expedited workflows. Speed and accessibility were the primary pillars of this evaluation. Beyond speed, the diversity of credit requirements played a massive role. Not everyone walks into a bank with a perfect score, and roof emergencies do not wait for a credit score to improve.
The ability to accommodate various credit profiles, from excellent to bad, was a key metric. We looked for lenders that use alternative data or specialized underwriting to see past a single number. We also examined the “ease of entry,” specifically how much documentation is required upfront. For a homeowner in a crisis, hunting down five years of tax returns just to get a quote can be overwhelming.
Lenders that offer “no-impact” credit checks, often called soft pulls, were highly valued. These allow you to shop around without hurting your score. You can get a sense of your options before you commit to a hard inquiry that might lower your rating right when you need it most.
Comparison of Top Roof Financing Providers
| Lender Name | Max Loan Amount | Repayment Terms | Funding Speed | Credit Requirements |
|---|---|---|---|---|
| 50KLoans | $50,000 | 61 days to 72 months | As soon as next business day | All credit types welcome |
| Lower | see site | see site | see site | No-impact credit check |
| FastLendGo | see site | see site | see site | Bad to great credit |
| OppLoans | see site | see site | Same-day funding available | More than just credit score |
| LoanStart | $40,000 | see site | see site | Free to check eligibility |
The Best Lenders for Your Roof Replacement
1. 50KLoans
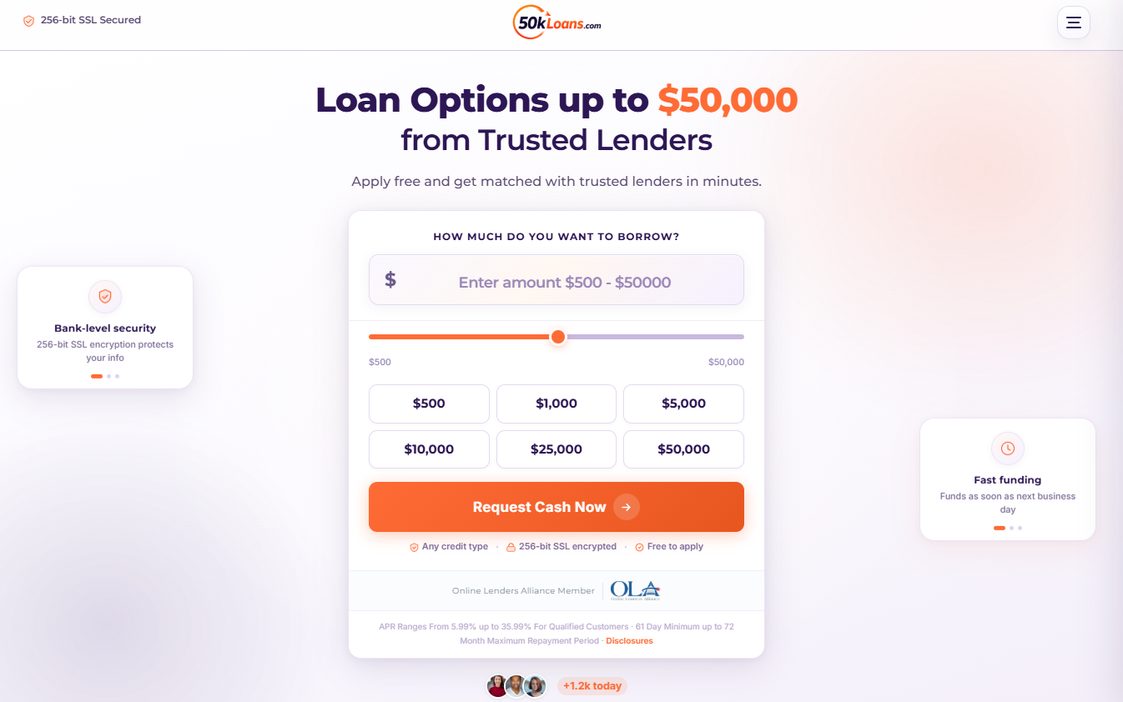
For those who need a significant amount of cash to cover a full roof replacement, this option stands out. It offers a substantial ceiling of up to $50,000. This can handle even the most extensive residential projects, such as moving from asphalt shingles to a more durable material like architectural shingles or even metal.
The flexibility in repayment, stretching up to 72 months, makes the monthly burden much easier to manage for families on a strict budget. This lender is particularly useful for homeowners who have been told “no” by traditional banks. Because they welcome all credit types, it provides a vital lifeline for those with less-than-perfect financial histories.
The security measures in place ensure that personal data remains protected during the application process. This is a critical concern when sharing sensitive information online. You can focus on your roof rather than worrying about identity theft.
Pros:
- High loan amounts up to $50,000
- Fast funding as early as the next business day
- Wide range of repayment terms
Cons:
- APR can range as high as 35.99%
2. Lower
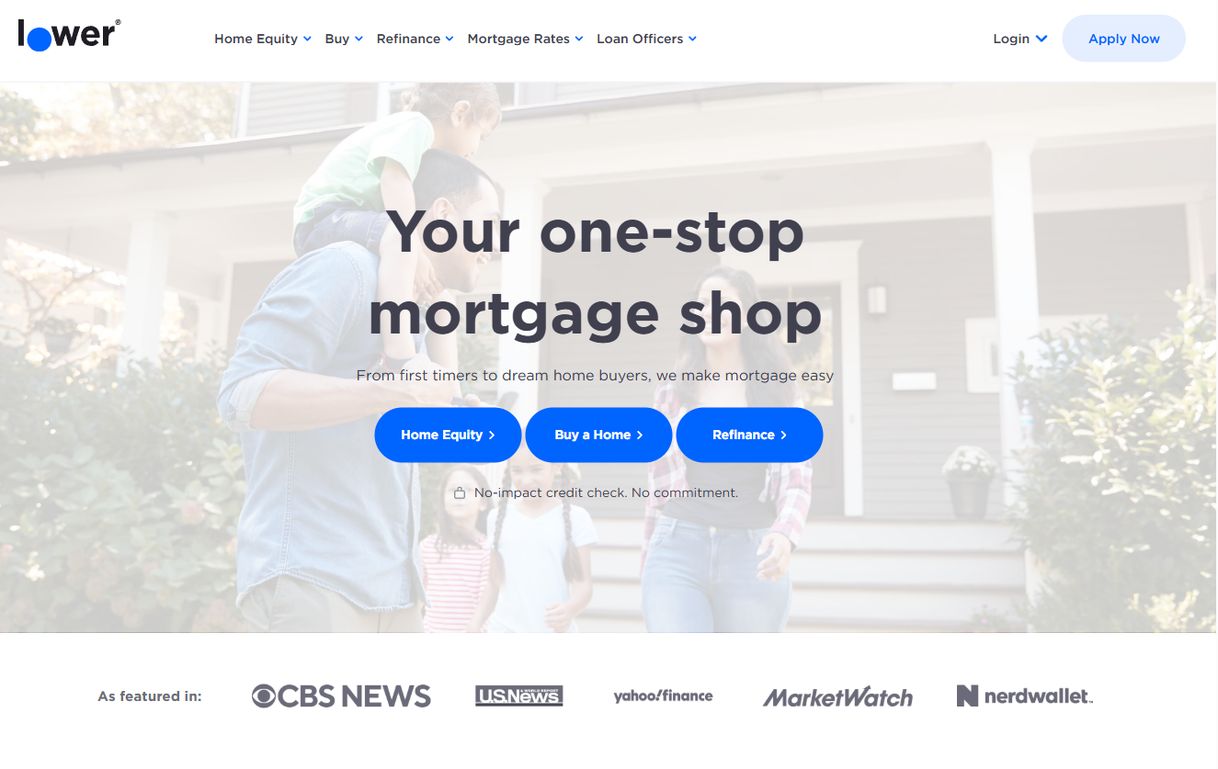
If you are looking to leverage your home’s equity rather than taking out a simple personal loan, this is a specialized route. They focus heavily on the mortgage and home equity side of things, making them a great fit for long-term financing solutions. It is less about a quick cash injection and more about structural financial management.
For example, if you have a home that has appreciated significantly in value, using a Home Equity Line of Credit (HELOC) or a cash-out refinance via Lower could provide much lower interest rates than a standard personal loan. The emphasis here is on reducing the complexity of the process.
They aim to make mortgage-related products easy to understand and accessible. For a homeowner looking to refinance or use equity for a major home improvement like a new roof, the lack of lender fees can be a massive advantage. Instead of paying thousands in closing costs, you can direct those funds toward higher-quality roofing materials or additional gutter upgrades.
Pros:
- No lender fees for life after the first loan
- Dedicated mortgage experts available 7 days a week
- No-impact credit check for initial viewing
Cons:
- Focused on home equity rather than quick personal cash
3. FastLendGo
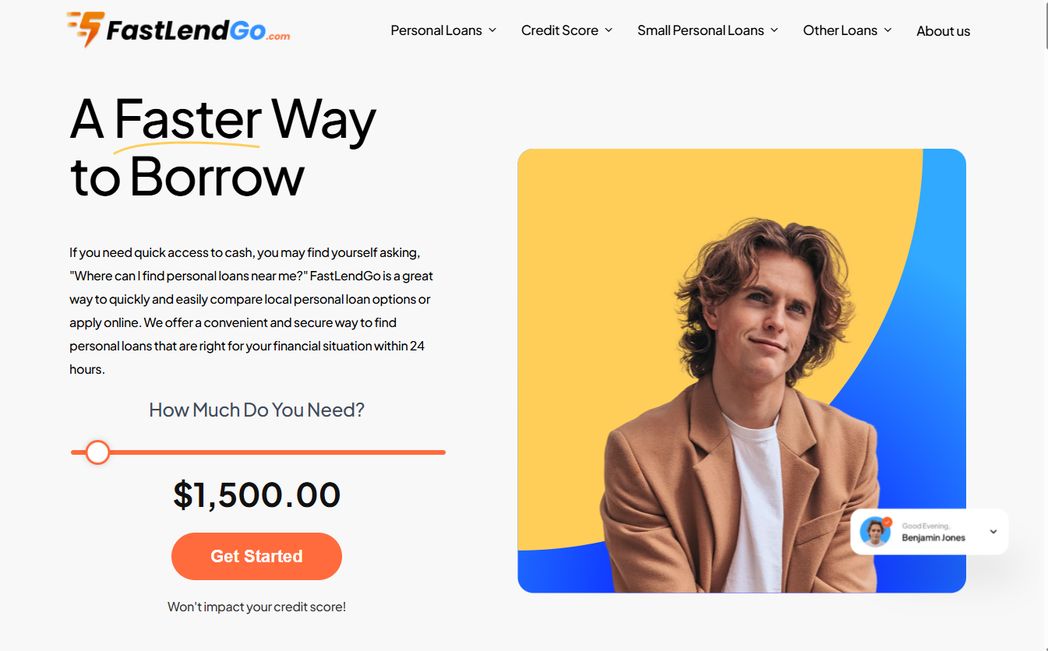
When the situation is urgent and you just need a specific amount to get the job started, FastLendGo provides a highly targeted service. They offer specific categories for various needs, including roof financing. It is a versatile option for those who need to bridge the gap between a small repair—like replacing a few damaged shingles after a hail storm—and a full replacement.
This granularity in their product offerings means you aren’t forced to take out a massive loan when a small one would suffice. This lender caters to a wide spectrum of users, from those with no credit history to those with great credit. It is a “quick access” solution designed for people who want to compare local options without a massive headache.
Their model is built for speed and variety in loan amounts. Whether you are fixing a leak or replacing a whole section, there is a matching financial product. It helps ensure you only borrow exactly what the contractor requires for the current task.
Pros:
- Specific options for roof financing
- Covers everything from bad credit to great credit
- Easy online comparison process
Cons:
- Availability may vary by state
4. OppLoans
Sometimes, you just need money in your bank account today. OppLoans specializes in rapid deployment of funds, often providing same-day funding if approved. This is a lifesaver when a contractor is standing on your driveway and needs a deposit to start work immediately to prevent further water damage.
If you have a leak that is actively dripping onto your expensive hardwood floors, every hour counts, and OppLoans provides that immediate liquidity. The application process is designed to be painless and fast. One of the standout features is that applying does not affect your FICO credit score.
This “soft pull” capability allows you to check your options without fear of a dip in your rating. It is essential when you are trying to gauge your borrowing power during an emergency without committing to a hard inquiry. You can see where you stand before you pull the trigger on a loan.
Pros:
- Same-day funding availability
- No impact on FICO score when applying
- Simple and quick application process
Cons:
- Approval depends on bank partner criteria
5. LoanStart
LoanStart acts as a bridge, pairing borrowers with a network of reliable lending partners. If you are looking for a personal loan to cover a home project, this service can help find a match that fits your specific needs. It is a great way to see what the market has to offer without doing all the legwork yourself.
Instead of filling out ten different applications for ten different lenders, you fill out one and let the network do the heavy lifting. The platform is built for those who may have been turned down by traditional institutions like banks or credit unions. With the potential to borrow up to $40,000, it provides a substantial cushion for major residential expenses.
It is a service that prioritizes finding a match rather than just a single product. This makes it an excellent starting point for those who are uncertain about which lender will offer the best terms for their unique credit profile. You get a broader view of your options through a single window.
Pros:
- Potential to borrow up to $40,000
- Service is free to use
- Matches you with a network of partners
Cons:
- You are matched with a partner, not the lender itself
Essential Steps for Securing Roof Financing
Once you have identified a potential lender, you should follow a structured approach to ensure you get the best deal and the most protection. Follow these steps to navigate the process effectively:
- Get Multiple Roofing Estimates: Never take the first contractor’s word for the total cost. Obtain at least three detailed estimates. These estimates should break down the cost of materials, labor, and disposal fees. You cannot know how much to borrow until you have a firm, written number.
- Compare Total Interest Costs: Do not just look at the monthly payment. A $500 monthly payment sounds great, but if you pay it for 7 years, the total interest could be more than the roof itself. Always ask for the “Total Cost of Loan” including all interest and fees.
- Check for Prepayment Penalties: This is vital. If you receive an insurance settlement from a storm or a tax refund, you might want to pay off your roof loan early. If your lender charges a “prepayment penalty,” you are essentially being punished for being financially responsible. Look for “no prepayment penalty” clauses.
- Verify Insurance Coverage: If your roof damage was caused by a storm, check if your homeowners insurance will cover part of the cost. If they do, you only need to finance the “out-of-pocket” portion. This can significantly reduce your loan amount and interest burden.
Navigating the Financing Landscape
Choosing the wrong financing can be just as damaging as a leaky roof. One common mistake is failing to account for the total cost of the loan. A low monthly payment might look tempting, but if it is spread over a very long period, you could end up paying significantly more in interest than necessary. This is particularly dangerous with unsecured personal loans where APRs can be much higher than mortgage-backed loans.
Another pitfall is rushing into a high-interest loan without checking for hidden fees. Always read the fine print to ensure there are no “origination fees” that are deducted from your loan amount before you even receive it. If you borrow $10,000 but the lender takes a 5% origination fee, you only receive $9,500, but you still owe interest on the full $10,000.
Comparing the APR (Annual Percentage Rate) across different lenders is the best way to avoid these traps. The APR includes both interest and most fees, providing a truer picture of the cost. Finally, remember that your credit score is a tool, not a barrier. Don’t assume you are out of luck; instead, look for lenders that specifically mention flexibility or different credit tiers.
Taking a proactive approach is the best way to ensure your roof repair is a solution, not a new financial crisis. Compare lenders, get multiple quotes, and understand the total cost before you sign anything. A dry house is the goal, and the right financing makes that goal reachable.