
The 5 Best Lenders for Plastic Surgery Loans for Bad Credit in 2026
Last updated: 2026-11-10
Walking into a surgeon’s office should feel like a step toward a new you, not a descent into financial dread. Many patients find themselves staring at a quote that feels like a mountain they simply cannot climb. When your credit score isn’t exactly a masterpiece, finding the right way to pay can feel like searching for a needle in a haystack.
The psychological weight of a medical bill can often overshadow the excitement of a transformative procedure, leading to “buyer’s remorse” before the surgery even begins. This tension is particularly high in elective cosmetic surgery. Costs are significant, and insurance providers often view these procedures through a very different lens than essential medical needs.
This list is for the individuals who need cosmetic or reconstructive procedures but face hurdles with traditional banking. Choosing a lender isn’t just about the interest rate. It is about finding a partner that understands the urgency of medical needs. We focus on speed, approval likelihood, and how much these lenders respect your existing credit history.
Whether you are undergoing a rhinoplasty, a tummy tuck, or even complex dental reconstruction, the method of payment you choose will dictate your financial health for years to come. You need a plan that fits your life, not one that consumes it.
- Cherry
- Discover
- FastLendGo
- SoFi
- CareCredit
How These Financing Options Were Evaluated
Comparing lenders is a bit like comparing different types of surgical tools. Some are precise and specialized, while others are broad and multipurpose. To make this list useful, we focused on how easily a person with less-than-perfect credit can secure funds. We looked at the speed of the application process and whether checking your status would hurt your score.
A “hard inquiry” can temporarily drop your credit score by several points. That is the last thing a patient needs when they are trying to secure optimal terms for a high-ticket procedure. We wanted to ensure the path to funding was as painless as the procedure itself.
The criteria also included the breadth of acceptance. A lender is only as good as the number of doctors who actually take their payment method. We prioritized options that offer quick decisions, as medical procedures often require timely scheduling. If a surgeon has a cancellation for next month, you want to know within minutes—not days—if you have the funding to take that slot.
The goal was to find a balance between accessibility for bad credit and the actual usability of the funds. We analyzed lenders based on their “soft pull” capabilities, their transparency regarding APR (Annual Percentage Rate), and their historical reputation in the healthcare sector.
We also considered the “hidden costs” of financing. This includes origination fees, which some personal loan providers charge upfront, and prepayment penalties, which can make paying off your debt early more expensive. The repayment schedule can be complex, too. A lender might offer a low monthly payment, but if that period stretches to 60 months with compounding interest, the total cost of your procedure could effectively double. Our evaluation sought to highlight lenders that provide clarity over complexity.
| Lender | Funding Speed | Credit Requirements | Key Benefit |
|---|---|---|---|
| Cherry | Fast (35 seconds) | High approval rates | Trusted by 60,000 providers |
| Discover | See if pre-approved | Credit card based | 99% acceptance rate |
| FastLendGo | Quick access | Bad/Fair credit options | Small personal loans available |
| SoFi | See site | Good credit preferred | Banking and investing tools |
| CareCredit | Instant decisions | Subject to approval | 285,000+ locations |
Top Ranked Lenders for Cosmetic Procedures
1. Cherry
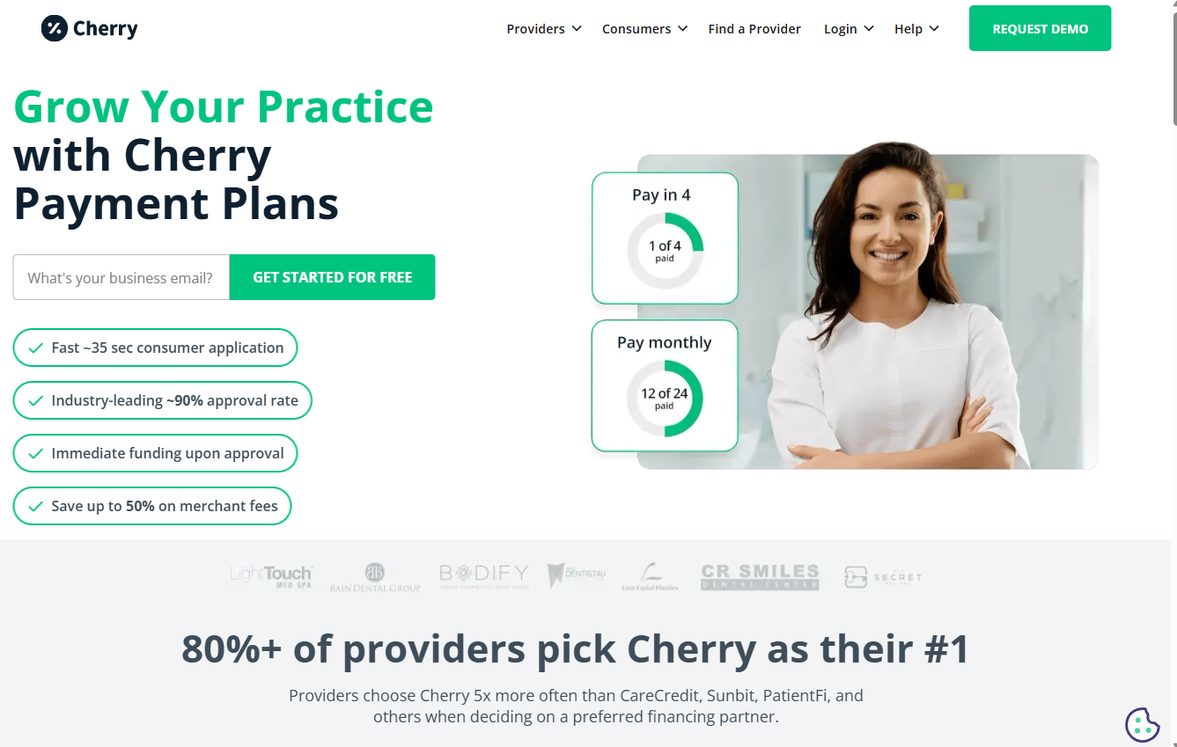
If you are looking for a seamless experience, Cherry often feels like the gold standard for medical financing. The application process is incredibly fast, often taking about 35 seconds to complete. This speed is vital when you are trying to lock in a specific surgical date before your surgeon’s schedule fills up.
In the world of elective surgery, timing is everything. Waiting a week for a loan approval could mean losing your preferred surgeon’s availability and pushing your procedure back by several months. You don’t want to be left playing phone tag with the scheduler because your bank is moving at a snail’s pace.
This provider is widely recognized, with 80% of providers choosing them as their primary financing partner. It is a heavy hitter in the industry, favored over many competitors because it is built specifically for the healthcare space. Unlike a standard personal loan that sits in your bank account, Cherry is often integrated directly into the provider’s checkout process.
This means the doctor gets paid immediately, and you get a structured, predictable repayment plan. This direct-to-provider model reduces the friction that often occurs when a patient has to manually transfer large sums of money from a personal loan account to a medical practice. It just works.
The flexibility of Cherry is a major draw. They offer various terms that can be tailored to your monthly budget, which is crucial when you are also accounting for post-operative care costs like medications, compression garments, or follow-up visits. They specialize in “point-of-sale” financing, meaning the approval happens right at the desk, making it feel less like a loan and more like a payment plan.
Pros:
- Extremely fast application process.
- High approval rate of approximately 90%.
- Immediate funding upon approval.
- Trusted by 60,000 healthcare providers.
Cons:
- Approval is subject to provider participation.
2. Discover
Discover is a household name that operates with the massive weight of an established financial institution. Because they are FDIC-insured and backed by the full faith and credit of the U.S. Government, there is a sense of security that comes with their brand. They are accepted almost everywhere that takes credit cards.
This makes them a “utility” option. If you have the credit capacity, it is a reliable way to manage medical costs without needing a specialized medical lender. It is a straightforward approach for those who prefer the familiarity of a major bank.
For those worried about their credit score, Discover offers a way to check for pre-approval without any impact on your score. This is a massive relief for anyone who is afraid of a “hard inquiry” ruining their chances of getting a loan later. This “soft pull” feature is a vital tool for surgical planning.
It allows you to walk into a consultation knowing exactly what kind of credit limit you might be granted. You can select a procedure that fits your actual budget rather than a hypothetical one. It takes the guesswork out of the consultation room.
Furthermore, Discover’s rewards programs can be leveraged for medical expenses. If you are paying for a high-cost procedure like a facelift or body contouring, using a card that offers significant cash back or travel points can effectively provide a small “rebate” on your surgery. However, this strategy only works if you can pay the balance in full. Carrying a high-interest credit card balance is the fastest way to turn a cosmetic enhancement into a long-term financial liability.
Pros:
- No impact to credit score when checking pre-approval.
- Accepted nationwide by 99% of card-accepting merchants.
- Significant cash back benefits on certain card types.
Cons:
- Traditional credit card requirements may be strict for bad credit.
3. FastLendGo
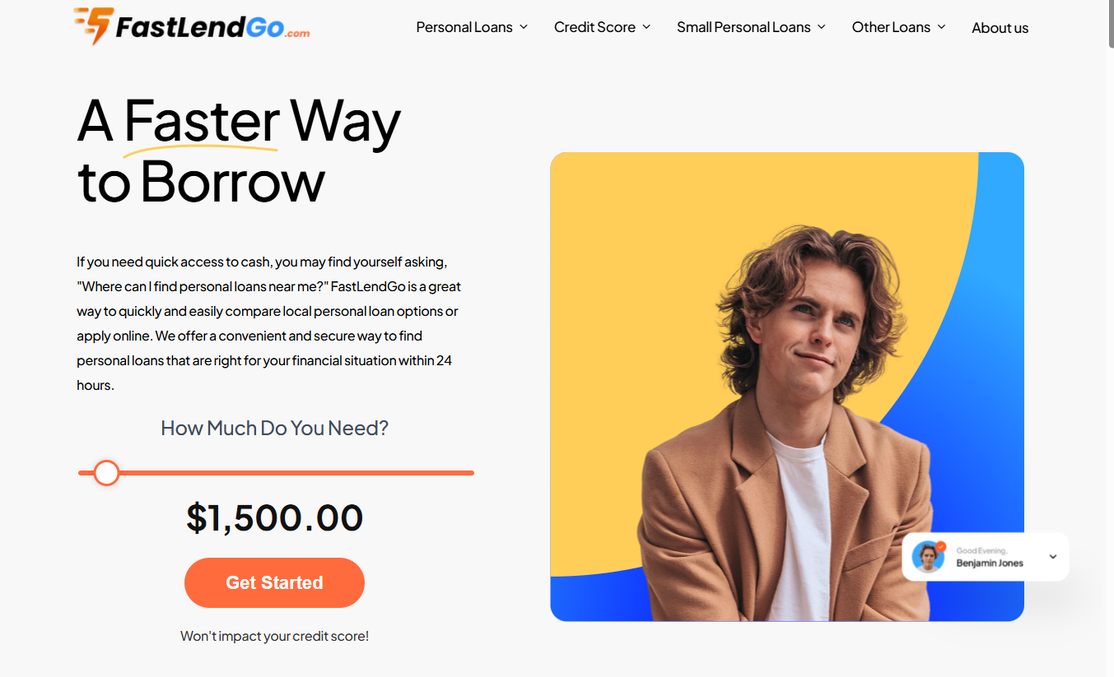
FastLendGo acts as a versatile partner for those who might not fit into the “perfect credit” mold. They offer a range of solutions from small $500 loans up to larger personal loans. It is a practical choice for someone who needs quick access to cash for immediate medical or personal needs.
Consider an unexpected dental emergency or a necessary dermatological procedure that isn’t covered by insurance. These situations don’t wait for a perfect credit score. FastLendGo provides a way to bridge that gap quickly.
The platform is designed to help people compare local personal loan options quickly. This is particularly helpful if you are looking for something specific, like dental or even auto repair financing. Instead of visiting five different banks and submitting five separate applications, FastLendGo streamlines the comparison process.
This is a massive time-saver for patients who are juggling multiple life responsibilities while trying to manage their health and finances. It cuts through the red tape that usually comes with traditional banking. Their model is built around the “bridge” concept.
If you have a gap in your savings or a temporary dip in your credit due to other life events, FastLendGo helps you find the shortest, most efficient path to liquidity. This can be life-changing for reconstructive surgeries that are necessary for quality of life but aren’t considered “essential” by traditional lenders.
Pros:
- Offers loans for various credit tiers, including bad credit.
- Flexible loan amounts from $500 upwards.
- Simple online comparison of local options.
Cons:
- Interest rates can vary significantly based on credit.
4. SoFi
SoFi is a comprehensive financial ecosystem that goes far beyond simple lending. They offer everything from high-yield savings accounts to stock trading and retirement accounts. This makes them a great choice for someone who wants to consolidate their entire financial life in one place.
If you are a high-earner looking to finance a major cosmetic transformation, SoFi’s streamlined digital experience is often the most efficient way to handle the transaction. It is built for the modern, digital-first lifestyle.
When it comes to surgery, they tend to favor those with good credit to secure the most favorable terms. They are the “all-in-one” option for the person who is looking to manage their medical debt alongside their long-term investments and daily banking needs. Many users find that by moving their direct deposit to SoFi, they can unlock even better interest rates on personal loans.
This makes the cost of their surgery lower than if they had gone to a traditional brick-and-mortar bank. Their mobile app is particularly robust, allowing you to track your loan balance, monitor your interest accrual, and even set up automated payments with a few taps.
For the tech-savvy patient, this level of control is invaluable for maintaining a strict budget during the recovery period. You might not be able to work immediately after surgery, or you might have extra expenses for post-op care. Having that control in your pocket helps you stay on track.
Pros:
- Comprehensive suite of banking and investment tools.
- High-yield savings and automated investing features.
- Robust digital tools and calculators for budgeting.
Cons:
- Typically requires good credit for the best terms.
5. CareCredit
CareCredit is a specialized health and wellness credit card that is widely used in medical offices. It is designed specifically for the healthcare industry, meaning it is accepted at over 285,000 locations. It is a dedicated tool for anyone looking to manage medical expenses through flexible financing.
Because it is a specialized product, the underwriting often focuses more on your ability to manage medical debt than a standard retail credit card might. This focus can make it easier to qualify for the specific type of spending you need.
The application is designed to be easy, providing instant credit decisions so you aren’t left waiting. They offer promotional financing options for larger purchases, which can be a lifesaver when facing a high-cost cosmetic procedure. For example, many providers offer “6 months interest-free” or “12 months interest-free” promotions.
This is an incredible tool if you are disciplined enough to pay off the balance within that window. However, be warned: if you fail to pay the full amount by the end of the promotional period, many lenders charge “deferred interest.” You are back-billed for all the interest that would have accrued from day one. Don’t let a missed deadline turn your dream procedure into a nightmare.
Pros:
- Widely accepted at a vast number of medical locations.
- Instant credit decisions through online application.
- Promotional financing available for purchases of $200 or more.
Cons:
- Subject to credit approval and specific terms.
Understanding the Total Cost of Ownership (TCO) of a Loan
Many patients make the mistake of looking only at the “monthly payment” when they sit down with a surgeon. This is a psychological trap. A monthly payment of $200 sounds much more manageable than a $5,000 lump sum. However, the math tells a different story.
If that $200 payment is spread over 48 months at an 18% interest rate, you will end up paying nearly $2,000 in interest alone. That is money that could have been used for your recovery, or better yet, saved for your future. Always look at the big picture, not just the monthly chunk.
To avoid this, you must calculate the “Total Cost of Ownership” for your medical debt. Before you sign, ask your surgeon’s billing department or your lender for a “Truth in Lending” disclosure. This document is legally required in many jurisdictions and will clearly state:
- The Total Finance Charge (the total amount of interest you will pay).
- The Total of Payments (the sum of every single payment you will make).
- The APR (the actual yearly rate you are paying, including fees).
Comparing these numbers across different lenders is the only way to ensure you are getting a fair deal. A lender might have a lower interest rate but a high “origination fee” that effectively makes the loan more expensive than a higher-rate loan with no fees. Always do the math before you commit.
How to Navigate Your Financing Journey
Before you sign any paperwork, you should always look at the fine print. It is easy to get caught up in the excitement of a new look, but the math needs to work in your favor. Always ask about the total cost of the loan, not just the monthly payment. A low monthly payment can hide a very high interest rate that will haunt you for years.
Additionally, ask if the loan is “unsecured.” Most personal and medical loans are, which means you aren’t putting your car or home up as collateral, but it also means the interest rates are higher to compensate for the lender’s risk. It is a trade-off between your assets and your interest rate.
Avoid the mistake of applying for multiple loans at once. Every time you submit a formal application, it can ding your credit score. This is known as “rate shopping.” While some lenders group multiple inquiries for the same type of loan into a single “pull” within a short window, it is still best to be strategic.
Instead, use the “soft pull” or pre-approval tools offered by companies like Discover or Cherry. This allows you to shop around for the best deal without damaging your financial standing. A good strategy is to get a pre-approval from 2-3 different lenders, then take those numbers to your surgeon’s office to see if they have any in-house financing incentives that could beat the external offers.
Finally, remember that communication is key. If you find yourself struggling to make a payment, reach out to the lender immediately. If you have an unexpected medical emergency or a period of unemployment, many lenders have “hardship programs” that can temporarily lower your payments or pause them for a month.
Being proactive is much better than waiting until you are in default, which can make your surgery feel like a permanent financial burden. Financial health and physical health are both journeys—one requires a careful budget, and the other requires a careful surgeon. Approach both with the same level of scrutiny.