
Top 5 Lenders for a 500 Credit Score Personal Loan in 2026
Last updated: 2026-11-10
Walking into a bank with a 500 credit score feels like trying to enter an exclusive club with a fake ID. The doors stay shut, the lights dim, and the tellers politely point you toward the exit. It is a frustrating reality for many Americans facing unexpected medical bills, urgent car repairs, or a sudden gap in employment.
When your credit score dips into the 500s, you aren’t just a number on a spreadsheet. You are a person navigating a financial system that often feels rigged against you. It is a tough spot to be in, especially when life throws a curveball that you didn’t see coming.
However, the financial world in 2026 has changed quite a bit. While a low score might keep you away from the best interest rates offered by major national banks, it does not mean you are out of the game. Fintech companies and specialized lending models have created a middle ground for those in the “fair” to “poor” credit categories.
Finding the right lender requires looking past the big national banks. You need to find specialists who see more than just a number. These are lenders who look at your income stability, your employment history, and your ability to repay, rather than just focusing on your past mistakes.
- Avant
- Upgrade
- JetzLoan
- Western Shamrock
- CreditNinja
How These Lenders Were Evaluated for Low Credit Scores
When evaluating lenders for individuals in the “very poor” credit category, accessibility is the primary goal. A score of 500 is a tough mountain to climb. It suggests a history of late payments, high credit utilization, or perhaps a recent bankruptcy or collection. Because the risk profile is higher, getting an approval without a mountain of paperwork is vital.
We prioritized lenders that offer clear paths to funding even when the credit history is less than stellar. We didn’t just look at approval rates; we looked at the entire lifecycle of the loan. Getting approved is only the first step in the process.
Beyond just getting approved, the speed of funding and the transparency of the terms were critical. Borrowers in this situation often need cash immediately to stop a downward spiral of late fees or to prevent a utility shut-off. Therefore, we looked for providers that offer quick decisions and don’t hide their true costs behind a curtain of complex fine print.
A lender that promises a low rate but takes three weeks to fund is useless to someone facing an eviction notice or a mechanic’s bill. We also assessed the “soft” vs. “hard” credit inquiry models. For someone with a 500 score, every single point matters. A series of hard inquiries can trigger a further drop in your score, potentially pushing you from “poor” into “subprime” territory.
This changes your eligibility entirely. Consequently, we prioritized lenders that allow you to “shop around” using soft inquiries. This allows you to compare rates without any risk to your credit profile.
| Lender Name | Max Loan Amount | Funding Speed | Credit Impact of Inquiry | Best For |
|---|---|---|---|---|
| Avant | see site | see site | see site | Debt Consolidation |
| Upgrade | $50,000 | Fast funding | No impact to check rate | Flexible terms |
| JetzLoan | $35,000 | As little as 24 hours | No credit impact | Speed and ease |
| Western Shamrock | $3,750 | see site | see site | Small installment loans |
| CreditNinja | see site | Same day decision | see site | Unexpected expenses |
Top Rated Lenders for Challenging Credit Situations
1. Avant
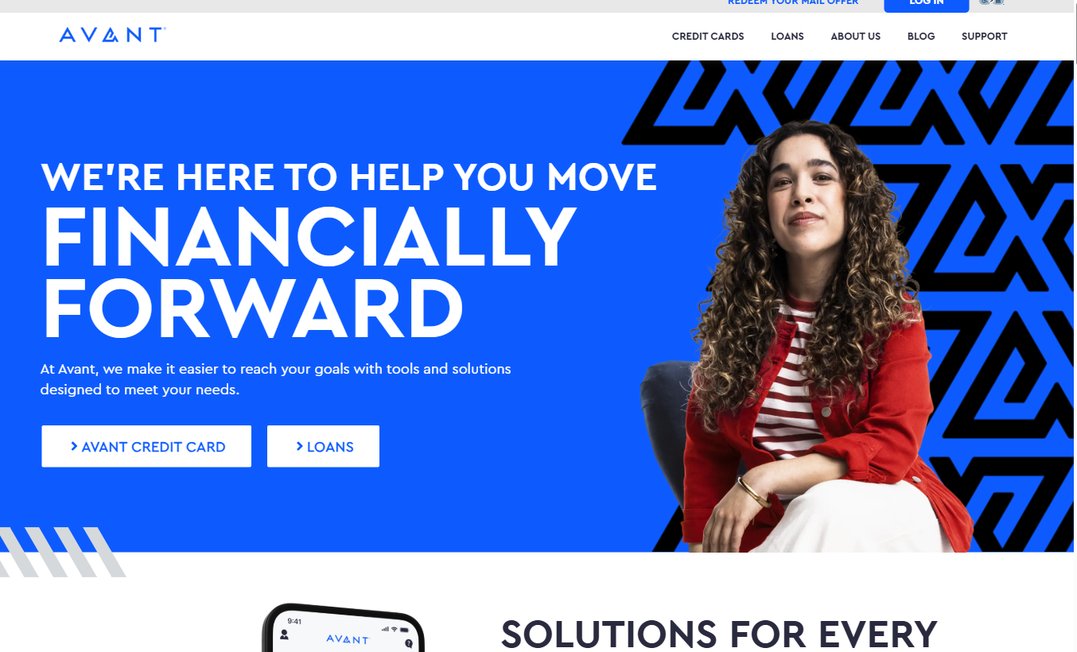
Navigating a financial recovery can feel like walking through a thick fog. Avant positions itself as a guide for those trying to move forward. They offer a variety of solutions, including credit cards and loans, specifically designed to help users manage their money more effectively through different stages of their journey.
They understand that a 500 score is often a snapshot of a difficult time, not a permanent identity. This lender is particularly useful for those looking to consolidate existing debt into a single, manageable monthly payment. If you are currently juggling four different high-interest credit cards with varying due dates, an Avant consolidation loan can roll those into one fixed monthly payment.
This simplifies your mental load and can prevent the “death spiral” of missing a payment because you simply lost track of a due date. By focusing on tools that help you move financially forward, they aim to provide more than just a lump sum of cash. They offer a structural way to handle debt.
Pros:
- Offers debt consolidation solutions.
- Flexible choices for different financial goals.
- Provides both credit cards and installment loans.
Cons:
- May have stricter requirements than specialized bad credit lenders.
2. Upgrade
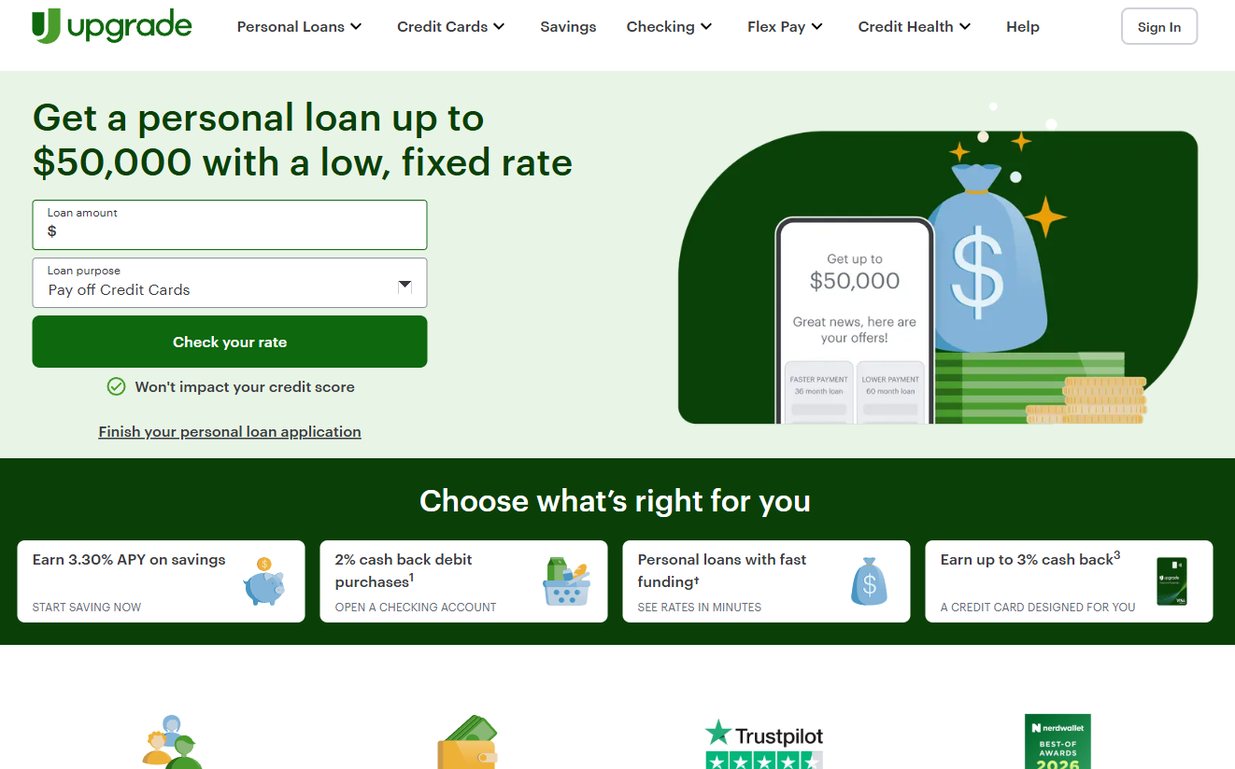
Sometimes you just need a boost to get back on your feet. Upgrade offers personal loans with a focus on speed and flexibility. They cater to a massive customer base, providing options that can help with everything from home improvements to paying off high-interest credit cards. They have become a mainstay in the fintech space because they bridge the gap between traditional banking and high-risk lending.
One of the standout features is their ability to let you check your rate without a hard credit pull. This is a lifesaver for someone with a 500 score, as it allows you to see your options without risking further damage to an already fragile credit report.
Imagine you are comparing five different lenders. With Upgrade, you can see if their rate is competitive without any “damage” to your score. A traditional bank would hit your score every time you hit “apply.”
Pros:
- No impact on credit score to check rates.
- Large loan amounts up to $50,000.
- Fast funding options available.
Cons:
- Interest rates may vary significantly based on credit profile.
3. JetzLoan
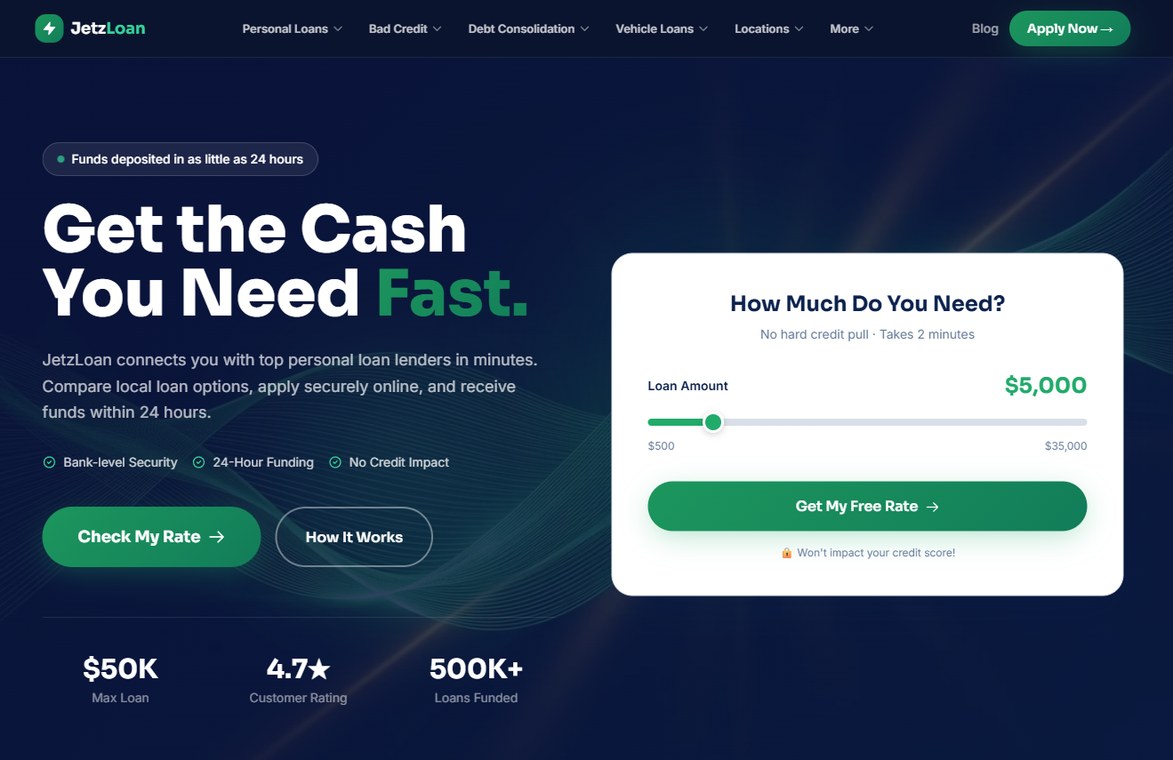
When the clock is ticking and an emergency strikes, waiting a week for a bank’s decision is simply not an option. JetzLoan is built for speed, connecting borrowers with top lenders in a matter of minutes. It is a streamlined process designed for those who need cash yesterday.
This is ideal for the “emergency” scenario—such as a transmission failure in your car that prevents you from getting to work. Such a breakdown would create an even larger financial crisis if left unaddressed. The platform is remarkably user-friendly, requiring only about two minutes to fill out a simple form.
They utilize modern API integrations to pull necessary data quickly, reducing the manual entry that often leads to errors and delays. With the potential to receive funds in as little as 24 hours, it serves as a high-speed bridge for those facing urgent financial hurdles like vehicle repairs or sudden bills.
Pros:
- Funding as fast as 24 hours.
- No hard credit pull to see rates.
- Simple, two-minute application process.
Cons:
- Maximum loan amount is capped at $35,000.
4. Western Shamrock
Not everyone needs a massive lump sum of cash. Sometimes, you just need a small cushion to get through the month. Western Shamrock specializes in smaller installment loans, ranging from $150 up to $3,750. This makes them an excellent choice for minor financial gaps.
If you are only a few hundred dollars short on your rent or need to replace a broken refrigerator, a $15,000 loan from a major lender would be overkill. It could potentially lead to a long-term debt trap. Western Shamrock allows for more surgical, precise borrowing.
They offer a highly personalized experience with multiple ways to apply. You can choose the digital route or a face-to-face conversation at a branch. This traditional touch can be comforting for those who find purely online lenders a bit too impersonal. In an era of automated chatbots, having the option to speak with a human being can provide peace of mind when you are stressed about your finances.
Pros:
- Very low minimum loan amounts starting at $150.
- No prepayment penalties on loans.
- Options to apply in-person at a branch.
Cons:
- Loan amounts are significantly lower than competitors.
5. CreditNinja
If you find yourself getting rejected by traditional banks, CreditNinja might be the safety net you need. They specialize in finding solutions for those who cannot get approved through standard channels. Their process is designed to be quick, aiming for same-day decisions to help with life’s sudden expenses.
They act as a marketplace, matching you with the specific lender most likely to approve your specific credit profile. The platform is built on the idea that your credit score isn’t the only thing that matters. By looking at a broader range of factors—such as your monthly income, your debt-to-income ratio, and even your banking history—they attempt to provide personalized loan amounts and repayment schedules.
This fits into your current life situation. This holistic view is essential for someone with a 500 score, as a single low score doesn’t tell the whole story of their financial reliability.
Pros:
- Potential for same-day decisions and funding.
- Considers factors beyond just a credit score.
- Flexible repayment schedules.
Cons:
- Approval is not guaranteed and depends on various factors.
Understanding the True Cost of Borrowing
Before you sign any agreement, you must understand that “low credit” often translates to “high interest.” While these lenders are more accessible, they are not “free money.” It is vital to distinguish between a helpful tool and a predatory trap. To do this, you must become an expert at reading the Truth in Lending Act (TILA) disclosures that every legitimate lender is required to provide.
First, look at the APR (Annual Percentage Rate), not just the monthly interest rate. The APR includes both the interest and any mandatory fees, giving you the most accurate picture of what the loan actually costs you per year. Second, examine the “Total of Payments” figure. This number tells you exactly how much you will have paid back to the lender by the end of the term.
If you borrow $1,000 and the total of payments is $1,800, you are paying $800 for the privilege of using that money. If that $800 is the cost of preventing a car repossession, it may be worth it; if it’s just for a new television, it’s a bad financial move.
Third, pay close attention to origination fees. Many personal loans for bad credit charge an upfront fee that is deducted from your loan proceeds. For example, if you are approved for a $2,000 loan with a 5% origination fee, you will only receive $1,900 in your bank account. However, you will still owe interest on the full $2,000. Always calculate your budget based on the amount you actually receive.
Strategies to Improve Your Score While Repaying Your Loan
The ultimate goal of taking a loan with a 500 credit score should be to ensure that you never need one again at that interest rate. You should view this loan as a bridge to a better financial future, not a permanent lifestyle. The most effective way to use a loan to improve your credit is through strategic debt management and consistent, on-time payments.
If you use a loan for debt consolidation, you have a golden opportunity to reset your credit utilization ratio. If you use the loan to pay off four credit cards that were all at 90% capacity, your credit score will likely see a significant boost even before you make your first payment. This happens simply because your revolving credit utilization has plummeted.
However, this only works if you do not run those credit card balances back up. If you pay off the cards with a loan and then immediately charge them up again, you will end up with the loan payment *and* the new credit card debt. That is a recipe for bankruptcy. Additionally, consider the “payment history” aspect of your score. Payment history is the single most important factor in your FICO score.
Setting up autopay for your new loan is one of the simplest and most effective ways to protect your progress. Even one late payment on a new loan can negate all the progress you’ve made in repairing your credit. Treat your new loan payment as your most important monthly bill. Prioritize it above dining out, streaming services, or non-essential shopping.
Finally, consider the length of your credit history. As you pay down your installment loans, you are building a history of successful, on-time repayments. This builds a “repayment track record” that lenders look for when you eventually apply for a mortgage or a car loan. By being disciplined now, you are essentially “buying” a better credit score for your future self.
How to Choose the Right Loan and Avoid Costly Pitfalls
Selecting a lender is not just about finding the first person who says “yes.” It is about finding the “yes” that won’t haunt you later. Always look closely at the total cost of borrowing. A low monthly payment might look attractive on paper, but if it stretches out over five years, you might end up paying double the original amount in interest.
A $200 monthly payment sounds manageable, but over 60 months, that’s $12,000 spent to borrow a $5,000 loan. Always ask yourself: “Can I afford the total cost, not just the monthly payment?” Avoid the temptation to jump at the first offer just because you are desperate. While speed is important, taking a moment to compare the actual terms can save you thousands.
Check for hidden fees, such as origination fees that are taken out of your loan amount before you even see the money. Also, be wary of “prepayment penalties.” While many modern lenders have eliminated these, some still include clauses that charge you a fee if you try to pay the loan off early. If you find yourself with extra cash from a tax refund, you want to be able to pay off that debt immediately without being penalized.
Another common mistake is ignoring the impact of interest rates on your long-term budget. If you are using a loan to consolidate debt, ensure the new interest rate is actually lower than what you are currently paying. If it isn’t, you are simply moving the furniture around in a burning house. Use these tools to build a foundation, not just to patch a leak. A loan should be a strategic move toward stability.