
The 6 Best Furniture Financing Options for 2026: A Comprehensive Ranking
Last updated: 2026-11-10
Walking into a showroom and falling in love with a velvet sofa can be a bittersweet moment when the price tag hits reality. You might find yourself staring at a dining set that looks perfect in your head but feels impossible for your current bank balance to swallow in one lump sum. The emotional high of finding the right aesthetic often clashes with the logistical reality of immediate expenditure.
Choosing the right way to pay is just as vital as choosing the right fabric. Whether you want zero-interest promotional offers or quick personal loans to cover a complete room makeover, the terms of your agreement will dictate your financial peace of mind for months. A decision made in the heat of a showroom visit can lead to long-term debt if the interest structures are misunderstood.
On the other hand, smart financing can act as a strategic tool to preserve your liquid savings for other household needs. Instead of draining your emergency fund for a new rug, you can spread the cost out. This keeps your cash accessible for life’s unexpected turns while still letting you enjoy a beautiful home today.
- Furniture Row
- JetzLoan
- Diamond Modern Furniture
- Makwa Finance
- Country Bank
- Best Egg
How These Financing Providers Were Evaluated
To determine which lenders stand out in the 2026 market, we analyzed several key performance indicators. We looked closely at how quickly a person could actually get their money or their furniture. Speed is often the difference between a beautiful home and a delivery truck that never shows up, especially during seasonal sales that require immediate funding to lock in a price.
The evaluation also weighed how accessible funds are for different credit profiles. Some lenders focus on those with stellar credit, offering the lowest possible APRs. Others act as a lifeline for those with less-than-perfect scores, prioritizing accessibility over premium rates. We prioritized transparency regarding interest rates, prepayment penalties, and the total amount of capital available to the consumer.
We specifically looked for lenders that do not penalize proactive borrowers who wish to settle their debts ahead of schedule. We also analyzed the “friction level” of the application process. In a digital-first economy, the number of steps required to move from interest to approval is a critical metric for busy shoppers.
We looked for providers that offer soft credit pulls. These allow you to see your potential terms without impacting your credit score, unlike those that require a hard inquiry immediately upon submission. Knowing your options without a hit to your score is a massive advantage when you are still just browsing.
| Lender | Max Loan/Credit | Funding Speed | Credit Impact | Key Feature |
|---|---|---|---|---|
| Furniture Row | See site | See site | See site | 0% Interest Options |
| JetzLoan | $50,000 | 24 Hours | No Hard Pull | Fast Personal Loans |
| Diamond Modern Furniture | $5,000 | Minutes | No Credit Impact Check | $1 Down Payment |
| Makwa Finance | $2,500 | Real-Time | See site | No Prepayment Penalties |
| Country Bank | See site | See site | See site | FDIC-Insured Stability |
| Best Egg | $50,000 | See site | See site | Fixed Interest Rates |
Top-Rated Furniture Financing Lenders for 2026
1. Furniture Row
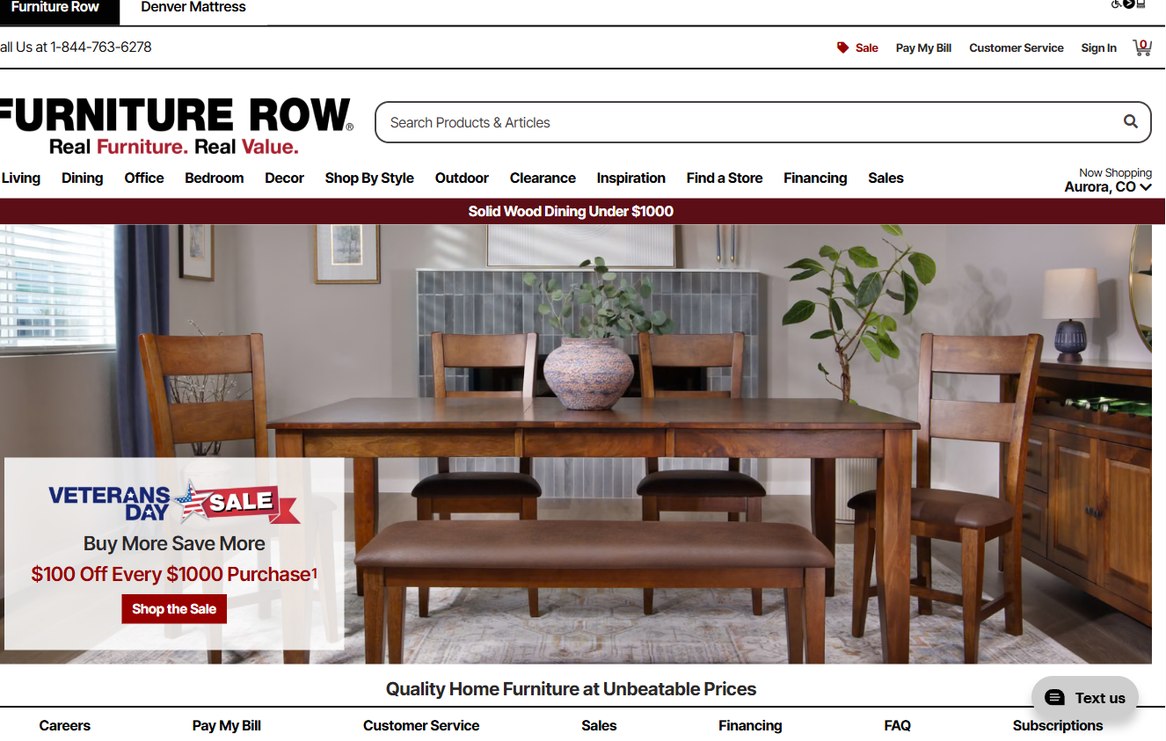
Furniture Row operates through partnerships with various financial institutions to provide a variety of ways to pay. This approach allows shoppers to find specialized terms that match their specific budget and timeline. It is a great option for those who want to shop for high-quality items without immediate financial strain.
By working with multiple banks, they can offer everything from traditional installment loans to more modern credit lines. The most significant draw here is the availability of 0% interest financing. For many shoppers, this is the golden ticket that makes a luxury sectional or a complete bedroom set suddenly very attainable.
It turns a massive upfront cost into a manageable monthly habit. However, users must be extremely disciplined. If a single payment is missed, many 0% offers are revoked, and interest may be backdated to the original purchase date. It is a double-edged sword that requires careful attention to your calendar.
Pros:
- Special 0% interest financing options available.
- Partners with multiple financial institutions for variety.
- Available for both in-store and online shopping.
Cons:
- Terms are dependent on specific institutional partnerships.
- Interest-free periods may have strict repayment requirements.
2. JetzLoan
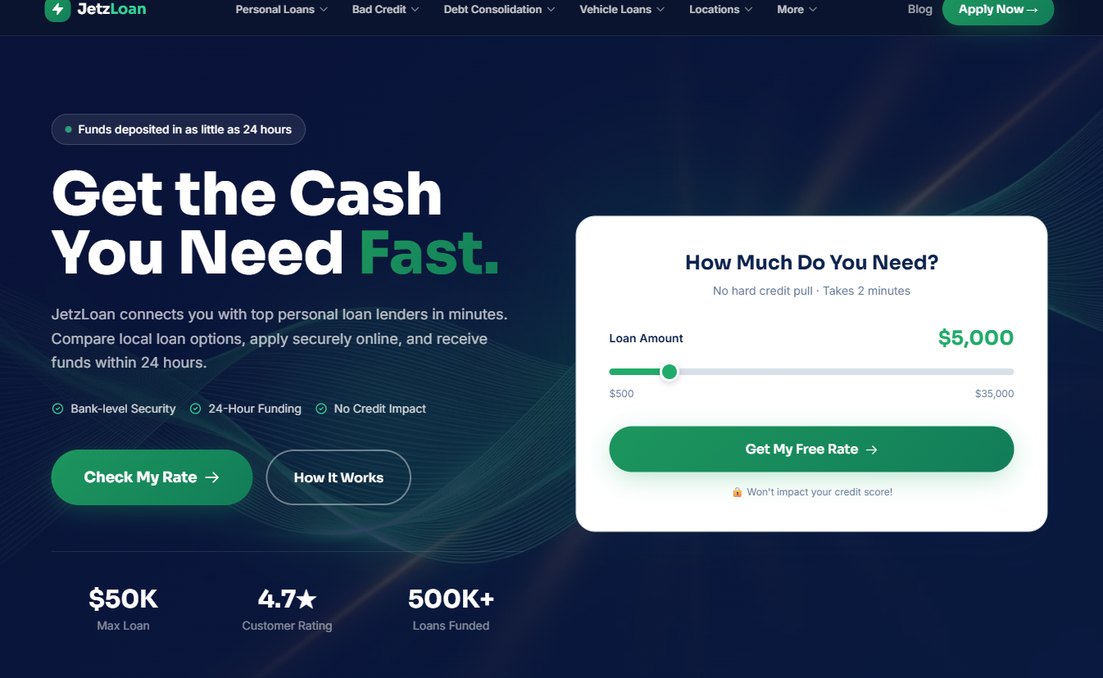
JetzLoan functions as a bridge between the consumer and top personal loan lenders. It is designed for the person who needs cash quickly to complete a home project, such as a sudden renovation or a full room replacement. The platform focuses on speed and transparency, making the application process feel incredibly streamlined and modern.
Instead of visiting a single bank, you are essentially tapping into a network of lenders through one interface. (jetzloan.com) This is an excellent choice for those who need to know their options without risking their credit score. Because there is no hard credit pull during the initial check, you can explore your rates with total peace of mind.
You can see if you qualify for a $10,000 loan before you ever commit to a single application that shows up on your report. Funds can land in your account in as little as 24 hours. This makes it ideal for time-sensitive sales where you need to act before the items are gone.
Pros:
- No hard credit pull to check rates.
- Funds can be deposited within 24 hours.
- High maximum loan amount of $50,000.
Cons:
- It is a marketplace, not a direct lender.
- Speed depends on the specific lender selected.
3. Diamond Modern Furniture
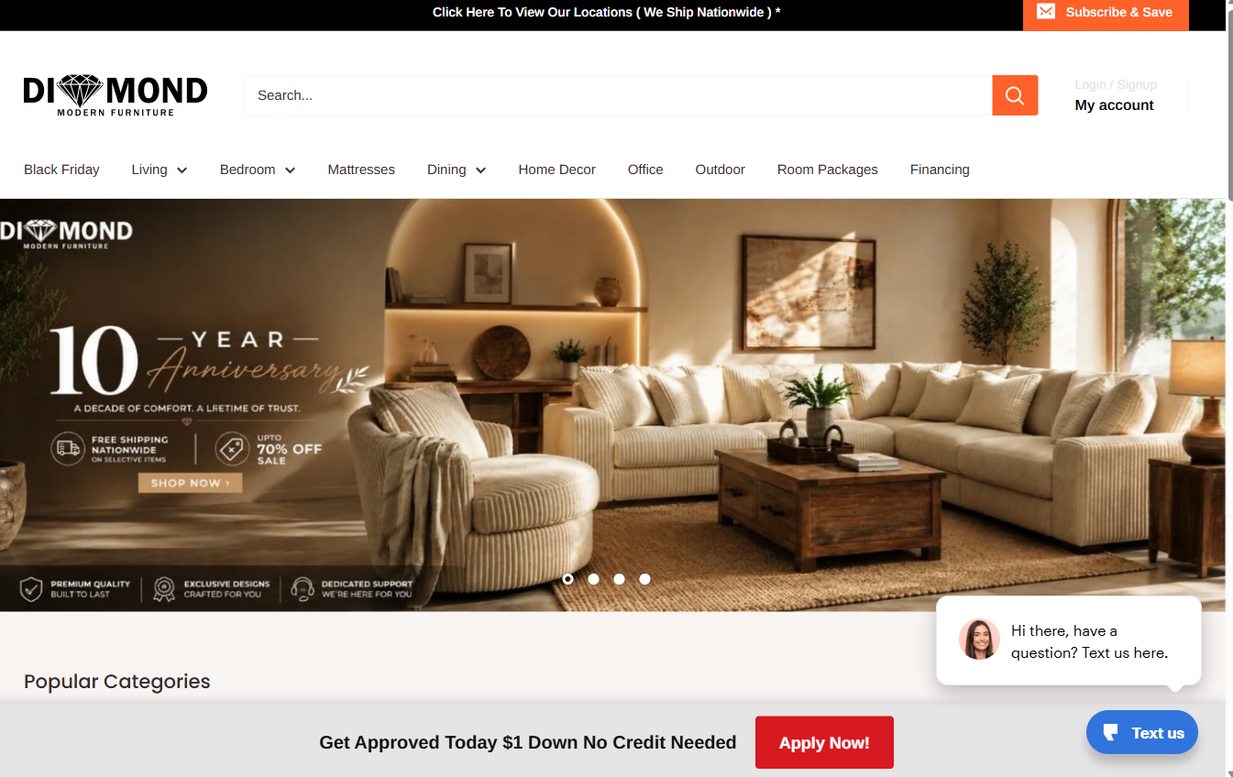
Diamond Modern Furniture offers a very low barrier to entry for those looking to furnish a space immediately. With a $1 down payment option, the dream of a new living room set is practically within reach for almost anyone. This is particularly useful for younger renters or those with unexpected expenses.
It is a practical solution for anyone who needs to maintain a standard of home comfort without a massive initial outlay. The approval process is remarkably fast, often providing a decision in just a few minutes. This is ideal for the spontaneous decorator who wants to walk into a showroom and leave with a plan.
It removes the friction from the purchasing process entirely. You can focus on the color of the cushions rather than the paperwork of the transaction. It is a fast track to getting your home looking exactly how you envisioned it.
Pros:
- Extremely low $1 down payment option.
- Decisions are made in minutes.
- No credit impact for checking approval.
Cons:
- Approval amounts are capped at $5,000.
- Terms may be specific to certain showroom locations.
4. Makwa Finance
Makwa Finance caters to those who value flexibility above all else. They offer real-time funding, meaning the money can arrive in your account in minutes rather than days. This is a lifesaver for urgent home repairs or last-minute furniture needs, such as when an old sofa is damaged or a sudden clearance sale occurs.
One of their standout features is the complete absence of prepayment penalties. If you find yourself with extra cash—perhaps from a tax refund or a holiday bonus—you can pay off the loan early to save on interest. This makes managing your debt much more intuitive and rewarding.
You are never “locked in” to a specific term if your financial situation improves. This freedom is a breath of fresh air in an industry that often tries to trap borrowers in long-term contracts. It is a simple, honest way to handle small-scale borrowing.
Pros:
- Real-time funding for immediate use.
- No prepayment penalties for early payoff.
- Small, manageable loan amounts up to $2,500.
Cons:
- Lower loan limits compared to personal loan providers.
- Strict application and verification steps required.
5. Country Bank
For those who prefer the stability of a traditional institution, Country Bank provides a sense of security. Being FDIC-insured, this is a place for people who want to manage their furniture financing alongside their long-term savings and mortgage goals. There is a psychological comfort in knowing your financial relationship is with a brick-and-mortar institution.
They offer a suite of personal banking solutions tailored to individual needs. While they might not have the flashy “instant” tech of some fintech apps, the reliability and community-focused service provide a foundation of trust. This is often the best route for those who want to sit down with a loan officer.
Discussing a larger, multi-room furnishing project that spans several months can be much easier in person. If you want to look someone in the eye while discussing your financial future, this is the place. It is about building a relationship, not just completing a transaction.
Pros:
- FDIC-insured and highly regulated.
- Comprehensive banking ecosystem for all life stages.
- Personalized banking solutions for various lifestyles.
Cons:
- May lack the instant gratification of fintech lenders.
- Typically requires more traditional documentation.
6. Best Egg
Best Egg is a heavyweight in the personal loan space, specifically for those looking to consolidate debt or fund significant lifestyle changes. They are highly rated by consumers and offer a very polished, digital-first experience that feels professional and secure. This is a sophisticated option for high-limit needs.
The platform is particularly useful for people looking for fixed interest rates and flexible terms. If you are using furniture as a way to upgrade your living space while managing other expenses, the ability to set a fixed payment schedule is a major advantage. You won’t have to worry about fluctuating market rates.
This allows for much more accurate long-term budgeting. You know exactly what is going out each month, which takes the guesswork out of your household finances. It is a clean, efficient way to handle larger purchases without the headache of traditional bank mortgages.
Pros:
- High loan limits up to $50,000.
- Fixed interest rates for predictable budgeting.
- Excellent reputation and customer ratings.
Cons:
- Requires more information for the application process.
- Not specifically specialized for furniture retailers.
Smart Strategies for Furniture Financing
Before committing to a loan, it is wise to perform a “cost-of-ownership” calculation. Many shoppers look only at the monthly payment, but the real metric is the total interest paid over the life of the loan. For example, a $3,000 sofa with a $50 monthly payment sounds inexpensive, but if that term lasts for five years due to high interest, you may end up paying $4,500.
Always request a breakdown of the total repayment amount before signing. Another effective strategy is to use financing as a temporary tool rather than a long-term obligation. If you qualify for 0% interest financing, use it—but only if you have the cash reserves to pay it off before the promotional period ends.
This allows you to keep your cash in a high-yield savings account, earning interest for yourself, while using the retailer’s money for free. This “arbitrage” strategy is a hallmark of savvy consumerism. It is about making your money work for you, even while you are buying new decor.
Common Mistakes to Avoid
The most common mistake is the “lifestyle creep” error. This happens when a consumer uses easy financing to buy a complete set of furniture—dining table, sofa, beds, and decor—all at once. This can lead to a sudden spike in monthly debt obligations that can overwhelm a budget. It is often better to finance one room at a time.
Allowing your income or savings to catch up before tackling the next area of the home is a much safer path. Additionally, be wary of “interest-only” periods or deferred payment options. While they sound attractive because they lower your immediate monthly burden, they often result in a massive “balloon payment” at the end of the term.
They can also cause interest to accrue aggressively in the background. Always prioritize loans with a standard, amortizing schedule where you can see your principal balance decreasing with every payment. This ensures you are actually making progress toward owning your furniture outright.
How to Navigate Your Financing Journey
Before you sign on the dotted line, take a moment to breathe and look at the fine print. It is easy to get swept up in the excitement of a new sofa, but the total cost of ownership is what matters. Always ask about the total amount payable over the life of the loan.
A common pitfall is ignoring the impact of interest rates. A “low monthly payment” often hides a much longer term that results in you paying significantly more than the sticker price. Always check if there are any hidden fees for late payments or if there are penalties for paying the loan off early.
Finally, match the lender to your specific situation. If you have great credit, look for 0% interest promotions. If you are in a pinch, look for real-time funding. If you are on a tight budget, look for low down payment options. Choosing the wrong tool for the job can turn a beautiful home into a financial headache.