
Top 5 Lenders for Motorcycle Loans with Bad Credit in 2026
Last updated: 2026-11-10
Trying to fund a new ride when your credit score is struggling feels like riding into a heavy thunderstorm without a helmet. You want to hit the open road, but traditional banks often slam the door shut before you even get your boots on. It is a frustrating spot to be in for many enthusiasts. You might have spent years building a garage, only to find that the bank views your financial history as a bumpy, unpaved trail rather than a smooth highway. For those of us who live for the roar of an engine and the freedom of the wind, being denied a loan because of a past mistake or a lack of long-term credit history feels like a personal setback.
When you are hunting for financing, the most important factors are how fast you get the money, how flexible the lender is, and how much the application impacts your current score. You need a path that gets you on two wheels without burying you in predatory terms that keep you stuck in the mud for years. It is a fine line to walk between finding a lender that is accessible and finding one that is predatory. A lender might offer a low monthly payment to get you in the saddle, but if that comes with a balloon payment or an astronomical APR (Annual Percentage Rate), you might find yourself working just to pay for the bike instead of enjoying it.
- Synchrony
- LendingPoint
- JetzLoan
- Speedy Funds Now
- Time Financing Service
How These Lenders Were Evaluated for Riders
The selection process focused on accessibility for those with non-traditional or damaged credit histories. A lender that only looks at a FICO score is useless to someone trying to rebuild their financial life while chasing a dream bike. We prioritized companies that offer quick decisions and clear, transparent terms for various personal needs. We didn’t just look at the interest rates; we looked at the user experience, the speed of the digital interface, and the “soft pull” vs. “hard pull” mechanics that protect your credit score during the discovery phase.
We also looked at the breadth of the loan amounts available. A rider looking for a vintage cafe racer might need a different amount than someone looking for a heavy touring machine. A used Honda CB750 might only require a small personal loan of $3,000, whereas a brand new Harley-Davidson Fat Boy or a high-performance Ducati could require $15,000 to $25,000. The goal was to find a range of options that covers everything from small quick fixes to larger, significant purchases. We examined how these lenders handle various scenarios, such as using the funds for a down payment on a dealer-financed bike or using a personal loan to pay for a private party sale where traditional dealer financing isn’t an option.
| Lender Name | Loan Amounts | Funding Speed | Credit Impact |
|---|---|---|---|
| Synchrony | see site | see site | see site |
| LendingPoint | $1,000 – $36,500 | see site | Does not impact credit score |
| JetzLoan | Up to $50,000 | As little as 24 hours | No hard credit pull |
| Speedy Funds Now | $100 – $35,000 | see site | see site |
| Time Financing Service | $1,500 – $12,000 | see site | see site |
Top Lenders for Motorcycle Financing in 2026
1. Synchrony
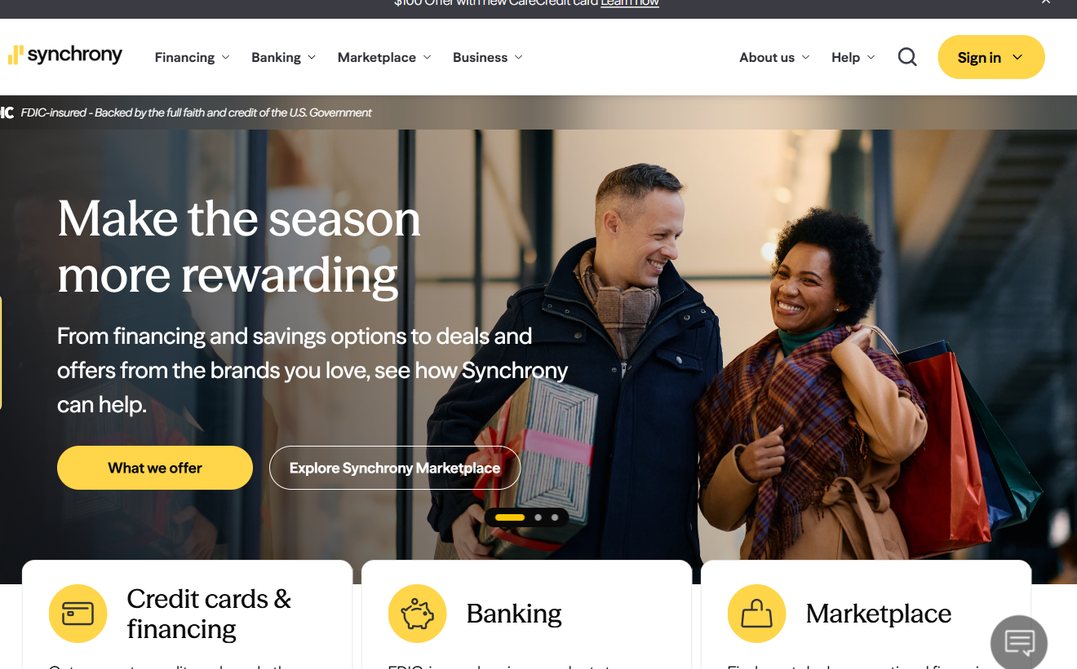
Synchrony operates through a vast marketplace that connects users to various financing options and banking services. It is a massive ecosystem designed to provide flexibility, making it a heavy hitter in the consumer finance space. They offer a wide variety of products that extend far beyond just a single type of loan. Because they are a major player in retail financing, many motorcycle gear shops and even some boutique dealerships utilize their systems to offer branded credit lines.
This lender is ideal for those who want a broad range of financial tools under one roof. While they focus heavily on credit cards and marketplace options, their presence in the financing world is undeniable. It is a solid choice for those looking for established, reliable financial structures. If you are looking to finance not just the bike, but also your riding gear—the helmets, the leather jackets, and the high-end intercoms—Synchrony’s ecosystem can often be integrated into a larger lifestyle credit strategy.
Pros:
- Extensive marketplace of financial products.
- Offers a wide range of banking and savings options.
- Backed by the full faith and credit of the U.S. Government.
Cons:
- May require specific cardholder status for certain sweepstakes or offers.
2. LendingPoint
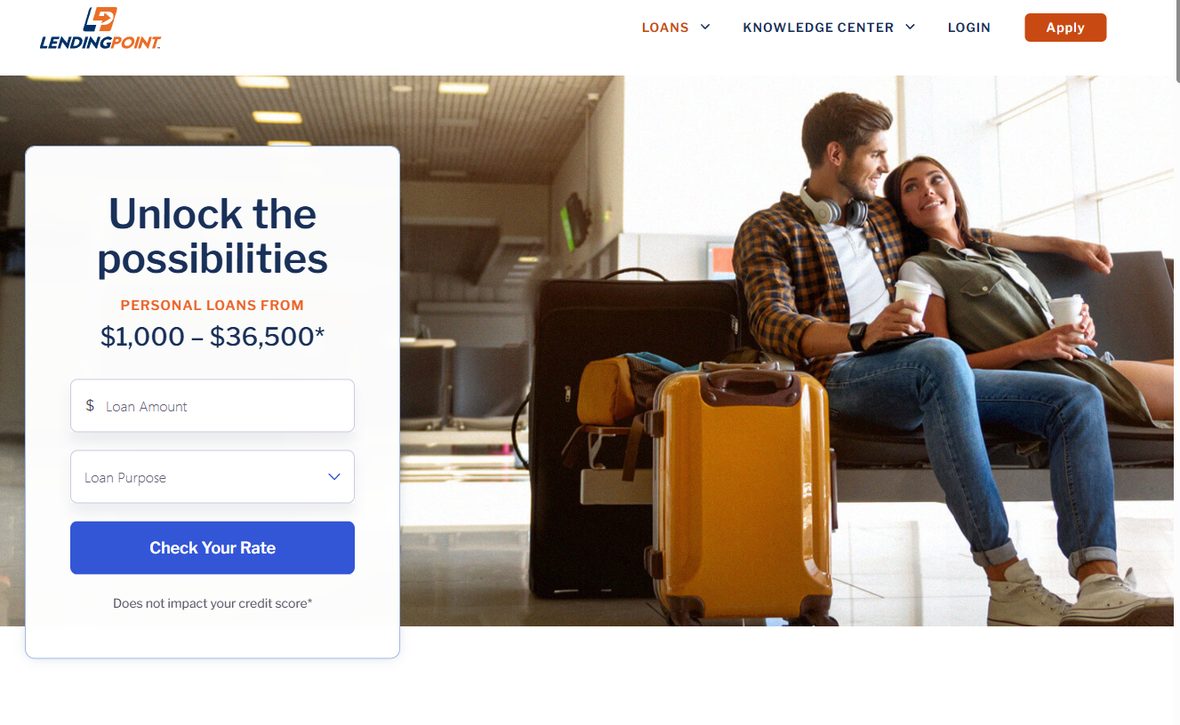
LendingPoint steps into the ring with a focus on personal loans that can handle anything from unexpected medical bills to a new motorcycle. Their loan amounts are quite substantial, ranging from $1,000 all the way up to $36,500. This makes them a versatile option for various types of riders and needs. Whether you are a teenager looking for your first used 250cc commuter or a seasoned rider upgrading to a mid-sized adventure bike, their limits accommodate a wide spectrum of the market.
One of the most refreshing aspects of their process is the ability to check your rate without affecting your credit score. This allows you to shop around without the fear of dropping your score even lower. For example, if you are currently in the middle of repairing your credit, every single “hard inquiry” from different lenders can look like a sign of desperation to other creditors. LendingPoint avoids this by using a soft pull for the initial quote, giving you a “what-if” scenario that is completely safe to explore. It is a low-risk way to see if you qualify before committing to a path.
Pros:
- High loan limits up to $36,500.
- Check rates without credit score impact.
- Versatile loan purposes including debt consolidation.
Cons:
- Specific requirements for identification and verification are mandatory.
3. JetzLoan
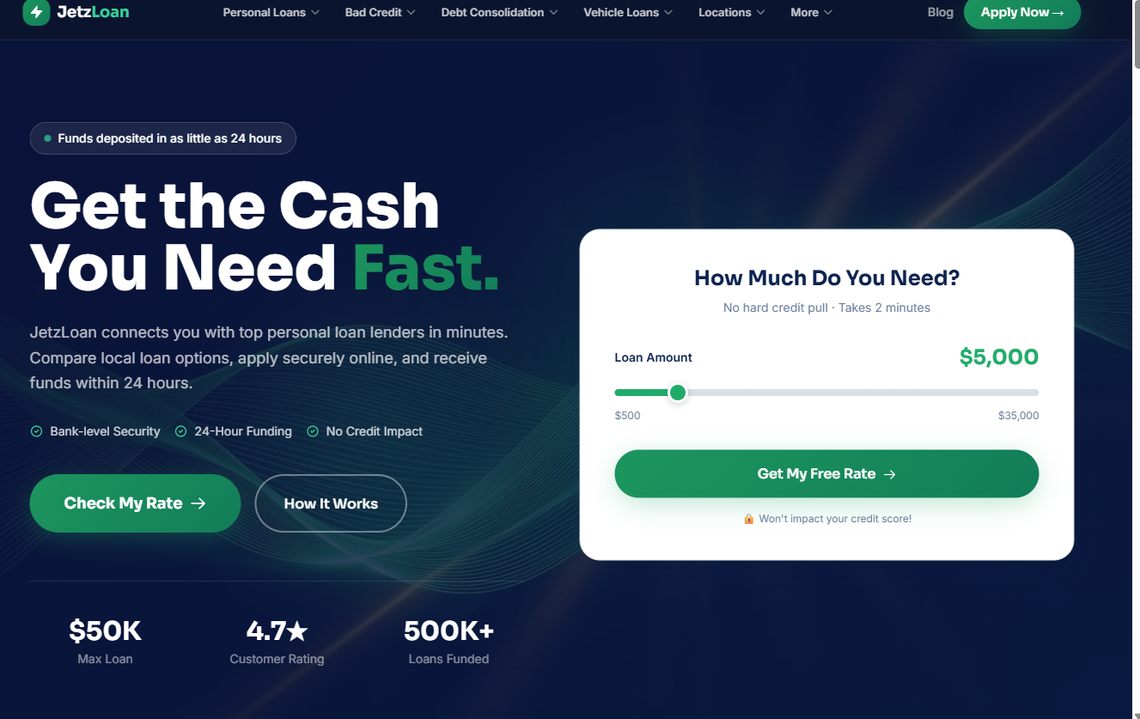
If you are itching to get on the road immediately, JetzLoan is built for speed. They promise to connect you with top personal loan lenders in just minutes. For those who need cash fast, they offer funding that can land in your account in as little as 24 hours. This is particularly useful when you find a “steal” of a deal on a Craigslist or Facebook Marketplace listing—a bike that won’t still be there by the time a traditional bank processes your paperwork.
They cater specifically to those with bad credit and offer loans up to $50,000. This high ceiling is perfect for high-end motorcycles or even a multi-bike purchase if you are a collector. The process is remarkably streamlined, taking less than two minutes to fill out a simple form. It is a highly efficient choice for the impatient rider who needs to act quickly, though you should always ensure you’ve read the terms to ensure the speed doesn’t come at the cost of an unnecessarily high interest rate.
Pros:
- Extremely fast 24-hour funding.
- No hard credit pull during the initial check.
- High maximum loan amount of $50,000.
Cons:
- The speed of the process might be overwhelming for those who prefer more deliberation.
4. Speedy Funds Now
Speedy Funds Now acts as a bridge, connecting you with a vetted network of lenders across the USA. They aren’t a direct lender themselves, but they act as a matchmaker to help you find the right terms. This can be incredibly helpful for someone who isn’t sure where to start. Instead of you spending hours calling individual banks, this service does the legwork of scanning various options to find matches for your specific credit profile.
Their loan amounts are quite flexible, starting as low as $100 and going up to $35,000. This makes them a great option for small repairs—like a new set of tires, a chain kit, or a replacement exhaust—or for larger motorcycle purchases. If you just need $500 to fix a leak so you can ride to a sale next week, this is a viable route. They focus on getting matched quickly so you can review real offers without any pressure.
Pros:
- Connects you to a wide network of vetted lenders.
- Low entry point for loan amounts starting at $100.
- Secure 256-bit SSL encryption for data safety.
Cons:
- You are dealing with a network of lenders rather than one single entity.
5. Time Financing Service
Time Financing Service offers a more targeted approach with personal loans ranging from $1,500 to $12,000. While the amount might be smaller than some others, it is a perfect sweet spot for many used motorcycle purchases. Most high-quality used bikes in the $2,000 to $8,000 range fit perfectly within this lending bracket. They provide a straightforward way to access cash when you need it, specifically tailored toward those mid-range needs.
They have modernized their experience with mobile apps for both Android and iOS, allowing you to manage your bills and payments on the go. This convenience is vital for busy riders who want to handle their finances from their smartphone while out at a bike meet or sitting in the pit lane. You can check your remaining balance, view your next payment date, or even make a quick payment between rides without ever having to sit down at a desktop computer.
Pros:
- Convenient mobile apps for Android and iOS.
- Specific loan range suitable for many motorcycle needs.
- Easy referral program for extra cash.
Cons:
- Lower maximum loan amount compared to other lenders in this list.
The Hidden Costs: Understanding APR vs. Interest Rate
One of the biggest mistakes riders make is looking only at the interest rate when comparing loans. While the interest rate is important, it only tells you the cost of borrowing the principal amount. The Annual Percentage Rate (APR) is a much more accurate reflection of what the loan will actually cost you. The APR includes the interest rate plus any origination fees, processing fees, or other mandatory costs required to get the loan.
For example, imagine you are choosing between two loans for a $5,000 used Kawasaki Ninja:
- Loan A: 8% interest rate, but with a $500 origination fee.
- Loan B: 9% interest rate, but with zero fees.
At first glance, Loan A looks cheaper. However, once you factor in that $500 upfront fee (which is often added to the loan balance), the APR on Loan A will be significantly higher than Loan B. When you are looking at motorcycle financing, always ask the lender: “What is the total cost of credit, including all fees?” This question can save you hundreds, if not thousands, over the life of the loan.
Preparing Your Paperwork for a Faster Approval
To get that bike in your garage as quickly as possible, you need to be organized. Lenders, especially those that offer 24-hour funding like JetzLoan or Speedy Funds Now, rely on automated verification systems. If your documentation is messy, you will get stuck in “manual review” hell, which can take days or even weeks to resolve. Follow these steps to ensure a smooth ride through the application process:
- Proof of Identity: Have a clear, unexpired color scan of your Driver’s License or Passport ready. Avoid using blurry photos taken in low light; they are often rejected by automated systems.
- Income Verification: Most lenders want to see how you pay for your life. Have your last two pay stubs or your most recent W-2 handy. If you are self-employed or a gig worker, have your last three months of bank statements ready to prove your regular deposits.
- Proof of Residence: A recent utility bill (water, electric, or gas) in your name is the standard. Make sure the address on the bill matches the address on your ID exactly.
- Bank Account Details: Since many of these lenders use ACH transfers for rapid funding, have your routing and account numbers ready. You will need a checking account to receive the funds directly.
By having these items prepared in a single folder on your computer or a dedicated folder in your phone, you can move from “just looking” to “loan approved” in a fraction of the time it takes the average applicant.
Avoiding Pitfalls in the Search for Financing
Before you sign on the dotted line, always look closely at the fine print. It is easy to get caught up in the excitement of a new machine, but ignoring the details can lead to a long-term headache. Make sure you understand every single fee associated with the loan. Ask specifically about:
- Prepayment Penalties: Can you pay the loan off early to save on interest without being charged a fee? This is crucial if you plan to get a raise or a tax refund and want to clear the debt quickly.
- Late Fees: What happens if you miss a payment by one day? Some lenders have very aggressive late fee structures.
- Origination Fees: Is the fee taken out of the loan amount (meaning you get less cash) or added to the total debt?
Avoid lenders that make you feel rushed or pressured into accepting an offer that doesn’t feel right. A good lender will be transparent about their terms and won’t hide the true cost of borrowing behind complex jargon. Always compare the total cost of the loan, not just the monthly payment. A $100 monthly payment sounds great, but if it’s spread over 72 months, you are paying a massive premium for that motorcycle.
Finally, remember that your credit score is a living thing. Using lenders that offer “no hard credit pull” checks is a smart way to explore your options while you work on boosting your score. This strategy keeps your options open and your financial health a top priority. Treat your credit score like you treat your bike: keep it clean, maintain it regularly, and don’t ignore the warning lights when they start flashing. A healthy credit score is the best ticket to the open road.