
The 5 Best Lenders for Bad Credit Loans in Pennsylvania for 2026
Last updated: 2026-11-10
Managing money in Pennsylvania can often feel like trying to walk through a thick fog. For many residents, a low credit score acts like a heavy anchor, pulling you away from the cash you need for urgent car repairs or mounting medical bills. It makes getting a simple loan feel like an uphill battle.
Finding a lender that looks past a single number is often the line between staying afloat and sinking deeper into debt. Whether you are dealing with a sudden repair in Philadelphia or a utility spike in Harrisburg, quick access to cash can stop a small hiccup from becoming a total disaster.
When you need emergency funds, you aren’t looking for a lecture; you want speed and honesty. You need to know exactly how much cash is coming your way and how quickly it will land in your bank account. We have focused this list on lenders that prioritize people with fair or poor credit while keeping their terms clear and upfront.
We specifically looked at the Pennsylvania market to ensure these options follow state laws and consumer protections. We wanted to find real alternatives to the high-interest payday loan cycles that many people try to avoid.
- OppLoans
- JetzLoan
- Prosper
- Experian
- LendingPoint
How We Picked These Pennsylvania Options
Our selection process focused heavily on whether a borrower with a less-than-perfect credit history could actually get approved. Since Pennsylvania has banned high-interest payday loans, finding legitimate installment loan alternatives is a necessity. You want to avoid the “debt trap” cycles that some predatory lenders use to keep people paying forever.
We looked for reputable lenders that offer structured repayment schedules. It was important that each lender could provide money quickly without a hard inquiry immediately tanking your FICO score. We wanted to make sure the process didn’t hurt your credit before you even knew if you were approved.
Transparency about loan amounts and speed was our next big metric. A lender that gives you a decision in minutes is worth much more to someone facing a medical emergency than a company that takes three days to think about it. We tested the application workflows to see if they were actually easy to use.
Every name on this list was vetted for the Pennsylvania market. We prioritized lenders that offer digital-first solutions, perfect for a busy person who doesn’t have time to sit in a bank office during business hours.
| Lender Name | Loan Amount Range | Funding Speed | Credit Impact for Quotes |
|---|---|---|---|
| OppLoans | see site | Same-day funding available | No impact on FICO score |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Prosper | $2,000 – $50,000 | Fast funding | No impact to credit |
| Experian | see site | see site | see site |
| LendingPoint | $1,000 – $36,500 | see site | Does not impact credit score |
Top Lenders for Bad Credit in Pennsylvania
1. OppLoans
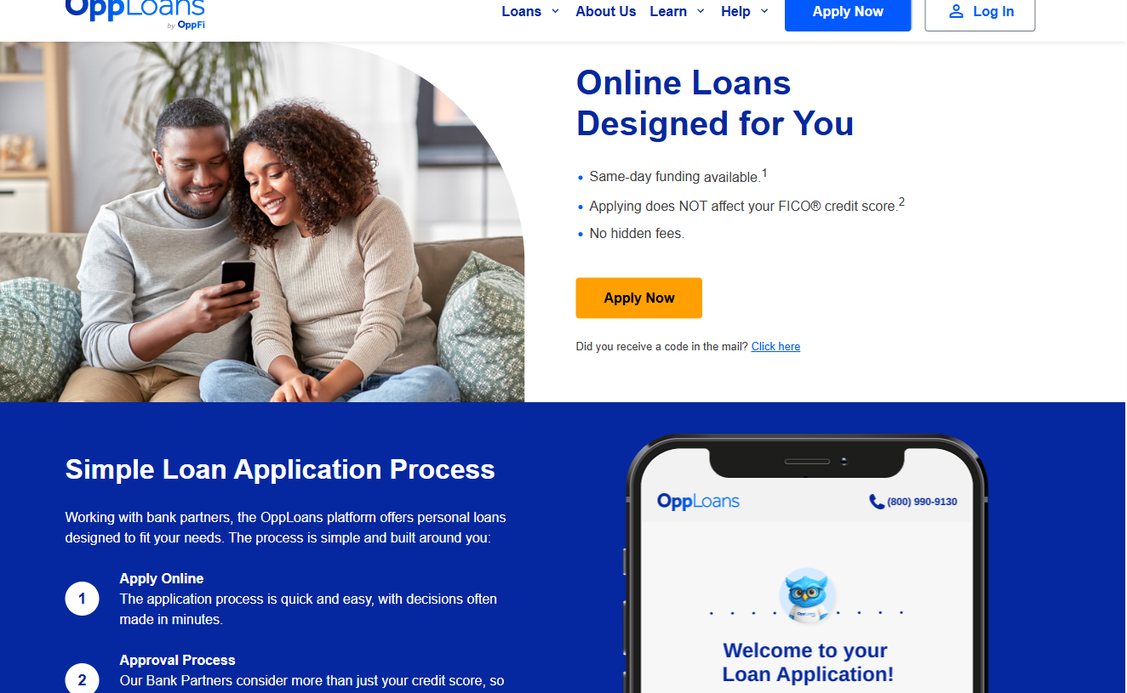
OppLoans is a specialized platform for people who often get a “no” from traditional banks. They work through bank partners to provide installment loans and lines of credit specifically for those with bad or no credit. It is a vital tool for anyone needing to bridge a financial gap without jumping through endless hoops.
Instead of relying solely on a high FICO score, OppLoans looks at a broader view of your financial stability. This helps people who are responsible but might have had a rough patch in the past. It is a way to get cash without the usual gatekeeping found at big-name banks.
The application is built for speed, often giving you a decision in just minutes. If you get the green light, they can facilitate same-day funding. This is a lifesaver for Pennsylvanians trying to settle an urgent bill before a service gets disconnected or a debt goes to collections.
It is a straightforward way to get capital without the headache of endless paperwork or long, awkward interviews. You can get back to your life much faster this way.
Pros:- Decisions are made in minutes.
- Same-day funding availability.
- Applying does not affect your FICO score.
- Specific interest rates are not disclosed upfront.
2. JetzLoan
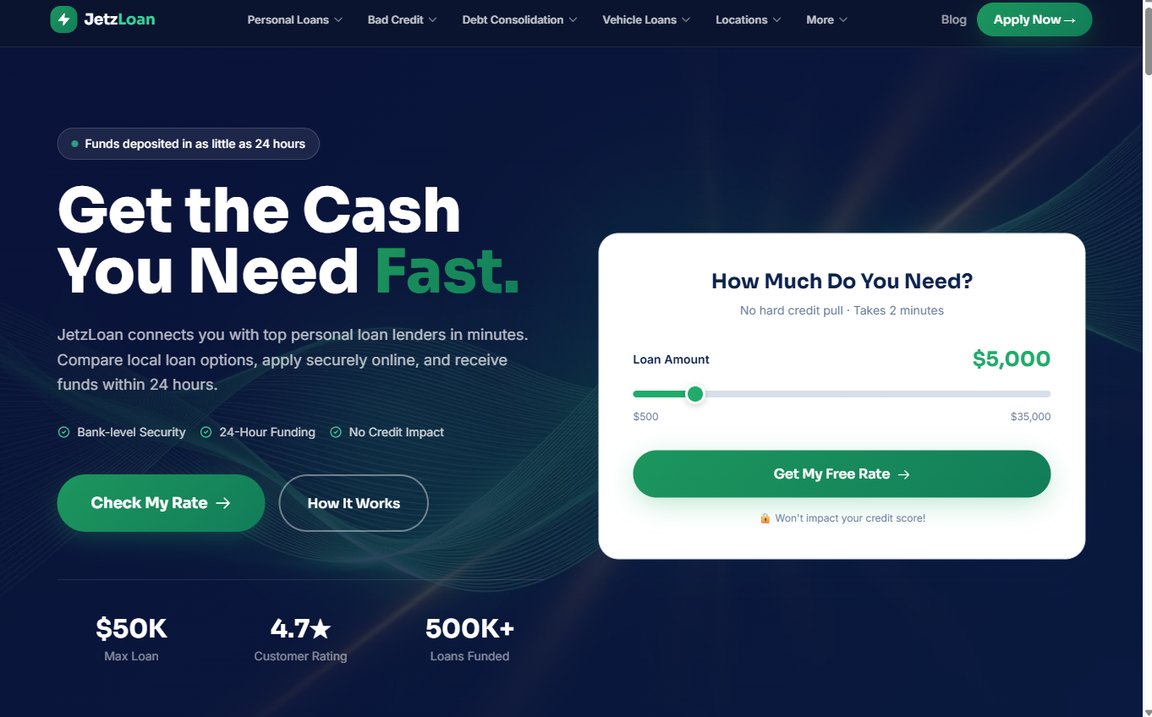
JetzLoan works like a matchmaking service. It connects you with various personal loan lenders in just a few minutes. This is perfect if you want to compare several different options without having to commit to one specific company right away. It is a high-speed way to see what is out there. (jetzloan.com)
The platform has a 4.7-star customer rating and has handled over 500,000 loans. With limits going up to $50,000, you have plenty of room to tackle anything from debt consolidation to fixing a car. The whole process is incredibly thin, usually taking less than two minutes to finish a form.
When you are already stressed about money, the last thing you want is a long, redundant application. This efficiency is vital. You can get the information you need without wasting your afternoon on a website that feels like it was built in the 90s.
Pros:- Funds deposited in as little as 24 hours.
- No hard credit pull required to check rates.
- High customer satisfaction rating.
- Maximum loan amounts may be limited by individual lender requirements.
3. Prosper
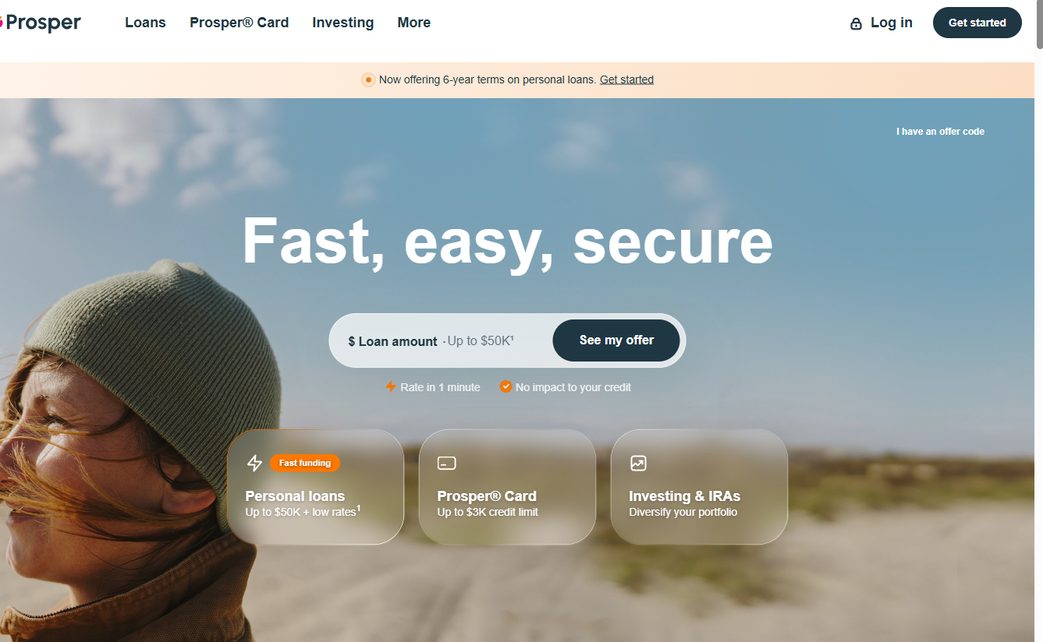
Prosper is a big name in the peer-to-peer (P2P) lending world. They offer personal loans with terms that can last up to six years. This makes it a great choice if you are trying to manage a large sum of money over a longer period. It is ideal for restructuring debt, like paying off several high-interest credit cards at once.
You can typically borrow anywhere from $2,000 to $50,000. Their platform is fast and secure, often showing you your rate in about a minute. Because this is P2P lending, you aren’t borrowing from a bank’s vault. Instead, you are borrowing from individual investors. This often leads to more flexible approval criteria.
It is a solid option for those who might not meet the rigid, old-school standards of a massive commercial bank. You get a different set of eyes on your application, which can work in your favor.
Pros:- Long-term 6-year options available.
- High loan limits up to $50,000.
- Excellent industry reputation and ratings.
- Peer-to-peer models may have different approval criteria than traditional banks.
4. Experian
Most people know Experian for credit reporting, but they also offer very useful loan matching services. They help you find offers that actually fit your specific financial profile. This is a huge time-saver if you are trying to rebuild your credit and don’t want to spend hours clicking through random websites.
They don’t just match you with loans; they offer tools to help you raise your score by paying bills like rent or utilities. This approach is helpful if you need cash today but also want to fix your financial health for the long haul. They focus on the reasons behind your score, not just the number itself.
By providing educational resources, they help you understand your creditworthiness in a way most lenders won’t bother with. It’s more of a partnership than a simple transaction.
Pros:- Provides access to credit-boosting tools.
- Helps match users with specific loan offers.
- Comprehensive financial guidance tools.
- The focus is often on credit monitoring rather than direct lending.
5. LendingPoint
LendingPoint focuses on personal loans for both urgent needs and planned life events. Whether it’s a tax bill or a home improvement project, they provide a structured way to get the cash. Their loan amounts range from $1,000 to $36,500. They tend to serve the “middle-market” borrower—someone with better credit than a subprime borrower but who still struggles with big banks.
The digital experience is designed to be very smooth. You can check your rate without it impacting your credit score, which lets you explore your options without any risk. This pre-qualification step is a must-have for anyone who wants to see if a loan is even a possibility before they commit.
It takes the guesswork out of the equation. You can see where you stand before you ever trigger a formal inquiry on your credit report.
Pros:- Wide variety of loan purposes supported.
- Loan amounts up to $36,500.
- Checking rates does not impact credit score.
- May require a higher credit tier than specialized installment lenders.
How to Get an Emergency Loan
If you find yourself needing money fast, a little bit of structure can save you from a lot of regret. Here is the best way to handle it:
- Figure out exactly what you need: Don’t just guess. Borrowing too much makes interest expensive, but borrowing too little means you’re still stuck with a bill.
- Use a soft credit check: Most good lenders let you check rates without hurting your score. Use this to compare at least two different places.
- Get your papers ready: Even online lenders will want to see your ID and proof of income. Have your pay stubs and bank statements ready to upload so things don’t stall.
- Look at the APR: The Annual Percentage Rate is the real number to watch. It includes interest plus any fees, so it’s the only way to compare the true cost.
- Check the monthly payment: Make sure you can actually afford it. A loan that is easy to get but impossible to pay back will only ruin your credit further.
Common Mistakes to Avoid
When your credit is low, it is very tempting to just take the first offer you see. Try to resist that urge. You need to look at the total cost of the loan, not just what you pay each month. A small monthly payment often means you’ll be paying much more in interest over a longer time.
For example, a $5,000 loan at 15% interest for 24 months is much cheaper than a 60-month loan at the same rate. The 60-month option might feel easier on your wallet today, but it will cost you thousands more in the long run.
Watch out for “hard pulls” on your credit. A “soft pull” is your friend; it lets you shop around without any penalty. Also, check the fine print for prepayment penalties. Some lenders actually charge you a fee for paying your loan off early. If you find a lender that lets you pay it off early for free, grab it.
| Mistake | The Risk | The Solution |
|---|---|---|
| Ignoring the fine print | Hidden fees can make the loan much more expensive than you thought. | Read the “Terms and Conditions” for “prepayment penalties.” |
| Borrowing for “Lifestyle” | Using high-interest loans for vacations creates a debt cycle. | Only use funds for essentials like medical or repair costs. |
| Missing a payment | Even one late payment can tank a low credit score. | Set up AutoPay so you never miss a due date. |
| Taking too many loans | Opening many lines of credit at once signals “credit hunger.” | Stick to one primary loan for your immediate need. |