
The 5 Best Personal Loans in Illinois: 2026 Lender Rankings
Last updated: 2026-11-10
Trying to find quick cash in the Windy City can feel like wandering through a maze of fine print and hidden costs. Maybe a sudden car repair has drained your savings, or perhaps you are looking to roll several high-interest debts into one manageable payment. The options throughout Illinois are massive, and they can feel overwhelming when you just need a straightforward answer.
Whether you are living in a busy Chicago apartment, a suburb like Naperville, or a quiet town downstate, your financial needs will look different than your neighbor’s. A loan that seems cheap on a monthly basis might actually become a heavy weight if the interest compounds aggressively. You have to look at the speed of funding and the terms to see if they actually fit your life.
This list breaks down the top performers currently available to Illinoisans. We have categorized them by their specific strengths so you can find a match that works for your specific situation.
- CreditNinja
- IllinoisLoansToday
- Wise Finance
- Alliant Credit Union
- Maroon Financial
How Illinois Lenders Were Evaluated
We looked at how well these providers actually help people living in Illinois. Speed matters immensely when an emergency hits. If you have a plumbing leak in an old Chicago bungalow or a medical bill that won’t wait, a 14-day bank review is simply too slow. We prioritized lenders that offer quick funding and reasonable loan amounts.
We also checked to see if they care about people with less-than-perfect credit. Some lenders are digital-first platforms using automated algorithms to make fast decisions. Other options are community-focused credit unions that prefer relationship-based lending. Knowing the difference helps you decide which path is right for you.
A student at a local university might find a better fit with a community credit union. On the other hand, a freelance professional needing immediate cash might prefer a digital matching service. It really comes down to whether you need a traditional banking relationship or just a fast, digital solution.
| Lender Name | Loan Amount Range | Funding Speed | Credit Focus |
|---|---|---|---|
| CreditNinja | See site | Same-day decision* | Flexible options |
| IllinoisLoansToday | $500 – $50,000 | Minutes | Bad credit options |
| Wise Finance | $1,200 – $10,000+ | Apply online today | See site |
| Alliant Credit Union | $1,000 – $100,000 | See site | |
| Maroon Financial | See site | See site |
1. CreditNinja
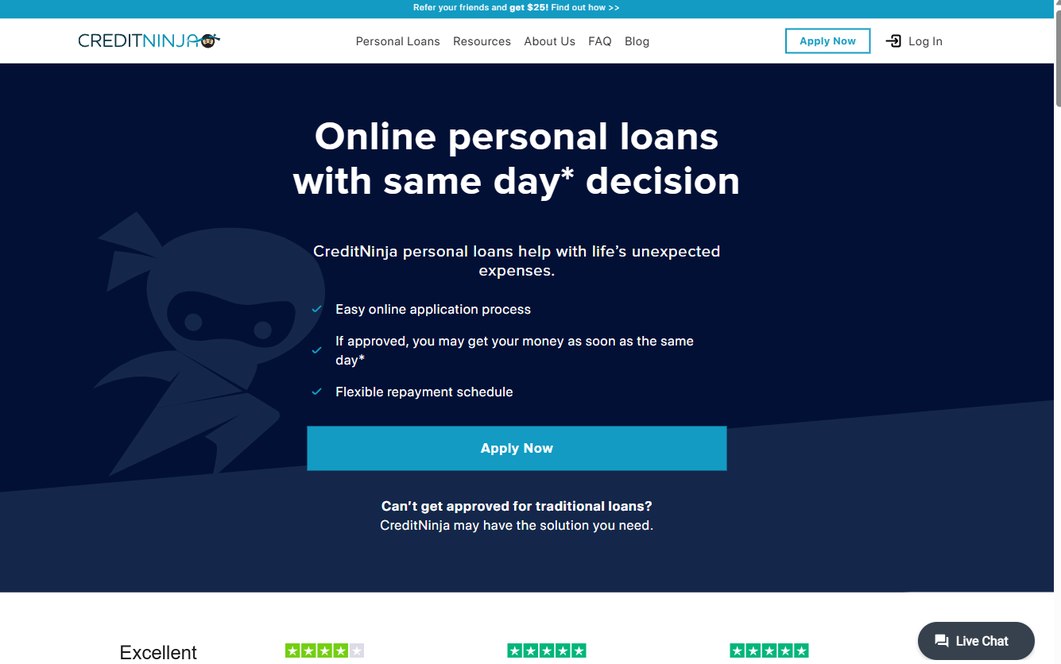
CreditNinja works well for those facing life’s unexpected expenses. Their platform is built for speed, using a simple online application that won’t require a mountain of paperwork. It is a solid choice for anyone who needs to know where they stand without waiting days for an answer. The interface is easy to use, even on a mobile phone while you are out and about.
If traditional banks have turned you away because of a thin credit file, this service might be a lifeline. They look beyond just your credit score to find potential matches, using various data points to see if you can repay. This “soft pull” approach for initial inquiries lets you explore your options without the risk of lowering your score with multiple hard inquiries.
The convenience is hard to beat when you are in a pinch. Once you sign the digital paperwork, funds can hit your account as soon as the same day, depending on your bank and the lender’s speed. It is a streamlined experience for Illinois residents who cannot afford to wait a week while their car sits at a mechanic’s shop.
Pros:
- Fast same-day decision potential for urgent needs.
- Simple and quick online application process.
- Considers more than just traditional credit scores.
Cons:
- Terms and rates can vary significantly based on individual profiles.
2. IllinoisLoansToday
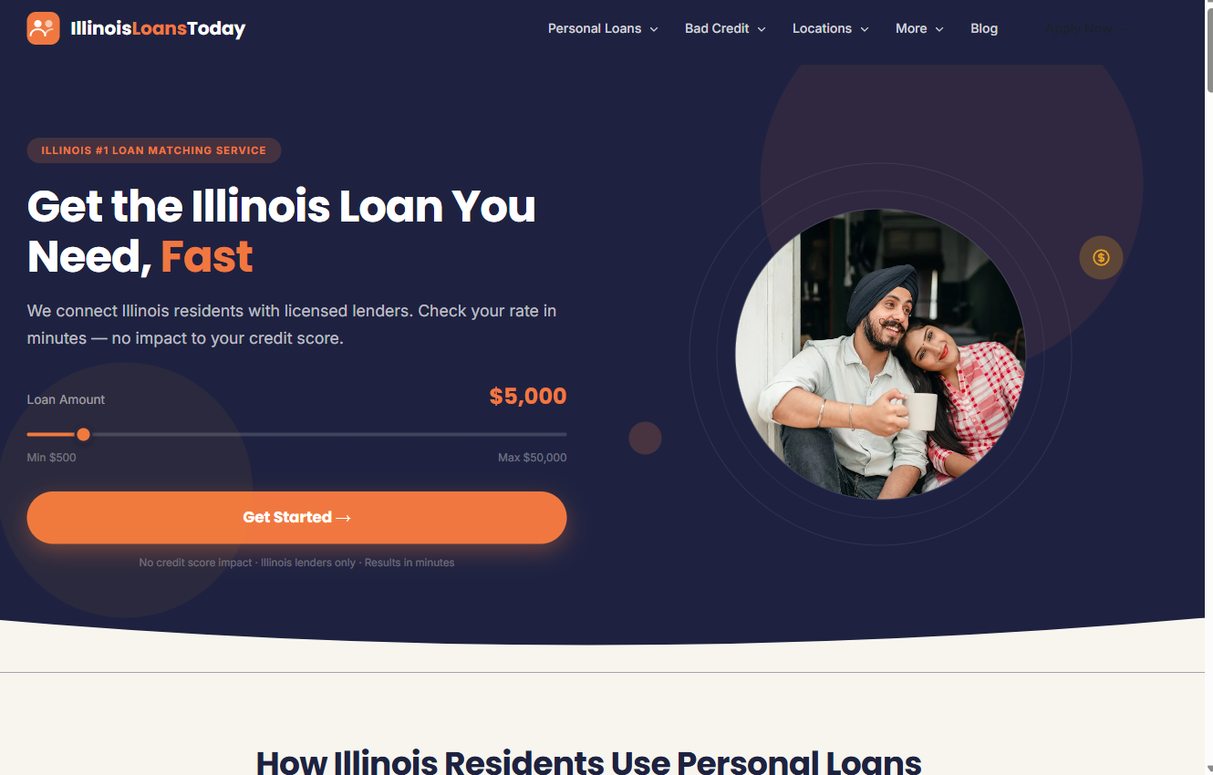
IllinoisLoansToday is a specialized matching service made specifically for people living in this state. They act as a connector, linking residents with a network of licensed lenders. This localized focus ensures that the options you see are relevant to Illinois laws regarding interest rates and lending practices. (illinoisloanstoday.com)
This service is great if you aren’t sure where to start. You can check your rate in a few minutes without hurting your credit score. That “pre-qualification” step is vital if you are trying to budget for a big expense like home repairs or consolidating debt. You get to see what you might qualify for before committing to a formal application.
The loan amounts range from a modest $500 to a substantial $50,000. This range covers everything from quick auto repairs to larger life transitions like moving or managing unexpected healthcare costs. Because they focus on the Illinois market, the lenders they partner with are often familiar with the local economy.
Pros:
- No impact to credit score when checking rates.
- Wide range of loan amounts from $500 to $50,000.
- Dedicated to Illinois residents only, ensuring local relevance.
Cons:
- As a matching service, you are being directed to other lenders rather than borrowing directly.
3. Wise Finance
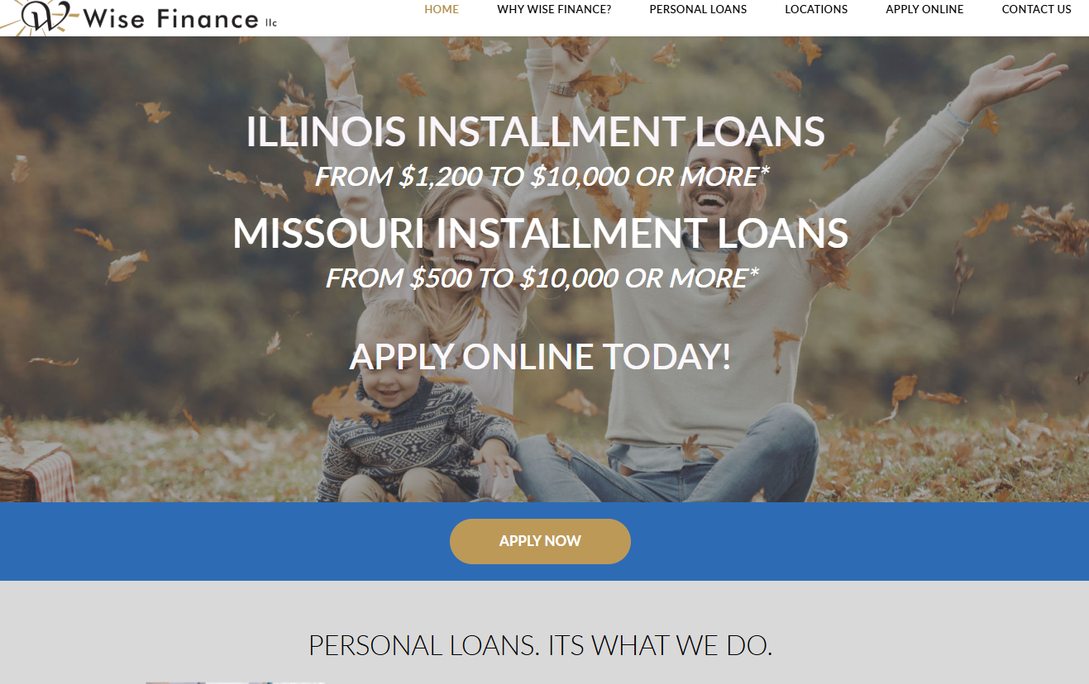
Wise Finance focuses on installment loans to help manage the inevitable hiccups in life. Whether it is a broken water heater, a dental bill, or a sudden holiday expense, they offer a steady hand. Their approach uses predictable repayment structures, which are often much easier to manage than the lump-sum repayments found in other short-term loans.
They offer installment loans starting from $1,200 up to $10,000 or more. This makes them a good choice for mid-sized expenses that need more breathing room than a small cash advance but don’t require a massive mortgage. Since payments are spread out over months, you can align them with your regular paychecks to keep your cash flow steady.
They also provide specific solutions for auto loans. You can use them to get something new or simply refinance a current vehicle to secure a lower interest rate. This versatility makes them more than just a personal loan provider. For an Illinois resident looking to lower monthly transportation costs, this can be a strategic move.
Pros:
- Offers installment loan structures for easier budgeting.
- Covers a variety of needs including auto loans.
- Online application is readily available and user-friendly.
Cons:
- Minimum loan amounts may be higher than some specialized micro-lenders.
4. Alliant Credit Union
Alliant Credit Union offers a more traditional banking experience with a focus on high-value products. For those with an established credit history and stable income, their personal loans offer significant flexibility. With amounts ranging from $1,000 up to $100,000, they are a strong option for major events like debt consolidation or home improvement projects.
They offer competitive APR ranges, typically between 8.74% and 11.74%. Repayment periods can span from 12 to 60 months. This structure lets you tailor monthly payments to your income. You might choose a 60-month term to keep payments low, or a 12-month term to pay off the debt quickly and save on interest.
As a credit union, they provide a different kind of service than a standard commercial bank. Credit unions are member-owned, so the focus is often on returning value to members through better rates. They also offer high-yield savings and CDs, making them a full-service partner for managing your entire financial journey.
Pros:
- High loan maximums up to $100,000 for significant needs.
- Predictable repayment periods up to 60 months.
- Wide range of banking products available.
Cons:
- Typically requires a better credit profile to access their best rates.
5. Maroon Financial
Maroon Financial Credit Union is a community-centric option that specifically serves the University of Chicago community. This makes them an excellent choice for staff, students, and alumni. They understand the specific professional and academic lifestyles of those living and working on the South Side of Chicago.
They offer specialized products like Payday Alternative Loans (PALs). These are designed to be a safer, more affordable alternative to high-interest payday loans. These PALs are often based on your relationship with the credit union rather than strictly your credit score. This provides a safety net for people who might have had a temporary financial setback.
Beyond these alternatives, they offer standard personal loans for debt consolidation and home improvements. Because they are a credit union, the focus stays on providing inclusive solutions for their members. They prioritize financial wellness, which often results in a more personalized experience than a massive, impersonal national bank.
Pros:
- Strong community focus for UChicago affiliates.
- Provides Payday Alternative Loans (PALs).
- Inclusive financial solutions for diverse groups.
Cons:
- Membership may be restricted to specific community groups.
Common Pitfalls to Avoid When Borrowing in Illinois
Before you sign a loan agreement, you must understand the fine print. One common mistake is ignoring origination fees or prepayment penalties. An origination fee is a one-time charge taken out of your loan. If you borrow $5,000 with a 5% fee, you only get $4,750, but you still owe interest on the full $5,000.
Watch out for the “low monthly payment” illusion too. People often pick the smallest monthly payment to keep things affordable. However, a lower payment usually means a much longer term. If you take 60 months instead of 36, you might feel better today, but you will end up paying much more in total interest. Always ask for the “total cost of credit” before signing.
Step-by-Step: How to Prepare for Your Loan Application
To make the process as smooth as possible, follow these steps before you start applying:
- Audit Your Documents: Gather your last two months of pay stubs, your last two years of W-2s, and recent bank statements. Even digital lenders often need these to verify your income.
- Check Your Credit Report: Visit AnnualCreditReport.com for a free copy. You want to fix any errors, like a debt that isn’t yours, before you apply to ensure you get the best rate.
- Define Your Exact Need: Don’t just ask for “some money.” Decide if you need $1,500 for a repair or $15,000 for a remodel. Asking for too much increases your interest costs, but asking for too little might force you to take a second loan later.
- Calculate Your Debt-to-Income (DTI) Ratio: Lenders look at how much of your monthly income already goes toward existing debts like rent or car loans. High DTI can lead to denials or higher rates.
How to Choose the Right Loan
Avoid the temptation to only look at the monthly payment. While a low payment sounds great, it often means a much longer term, which results in you paying significantly more in interest over the life of the loan. Always calculate the total cost of the loan before signing anything. If you are comparing two loans, see which one results in less money leaving your pocket in total.
Another mistake is neglecting to check the total origination fees or prepayment penalties. Some lenders might offer a low interest rate but will charge you a massive fee just to access the money. Always read the fine print. If a lender is hesitant to provide a clear breakdown of all fees in writing, treat that as a major red flag.
Finally, consider how your credit score affects your options. If you are in a rush, a matching service or a specialized lender might be faster. However, if you have excellent credit, a credit union like Alliant might offer much better interest rates. Match the lender to your urgency and your credit profile so you aren’t paying more than you need to.