
The 7 Best RV Financing Options for Travelers in 2026
Last updated: 2026-11-10
Hitting the open road in a luxury motorhome or a cozy travel trailer is a dream for many. However, the price tag on a modern rig can feel like a heavy anchor. Finding the right lender is the difference between a smooth journey and a stressful financial detour. Whether you are eyeing a high-end Class A diesel pusher or a lightweight pop-up camper for weekend excursions, the financing you secure will dictate your lifestyle for years to come.
Selecting a lender requires looking beyond just the monthly payment. You must consider how quickly funds arrive, what kind of credit history is required, and whether the lender understands the specific nuances of recreational vehicle assets. For example, a lender that specializes in auto loans might struggle to value a complex fifth-wheel with high-end solar packages and specialized interior amenities, potentially leading to lower loan-to-value ratios. This guide simplifies that complex search by breaking down the market into digestible segments.
- Solarity Credit Union
- Elite Direct Finance
- JetzLoan
- EZ RV Credit
- Huntington
- Prosper
- Bank Iowa
Evaluating the Top Recreational Vehicle Lenders
To determine which lenders offer the most value, several key metrics were analyzed. This process focused on the accessibility of funds and the flexibility of terms offered to different types of borrowers. We looked at how quickly a person could move from application to driving away, considering the time-sensitive nature of buying from private sellers or at high-volume dealership events.
The comparison also weighed the importance of credit requirements. Some lenders cater to those with pristine histories, offering the lowest interest rates and most favorable amortization schedules. Others specialize in helping people navigate the tricky waters of sub-prime or no-credit scenarios, prioritizing the asset’s value over a perfect FICO score. This ensures every type of traveler—from the seasoned retiree with decades of credit history to the young adventurer starting fresh—finds a suitable match.
| Lender Name | Loan Amounts | Terms | Credit Requirements | Funding Speed |
|---|---|---|---|---|
| Solarity Credit Union | See site | See site | See site | See site |
| Elite Direct Finance | See site | Up to 20 years | All types including sub-prime | Fast approvals |
| JetzLoan | Up to $50,000 | See site | No hard credit pull | As little as 24 hours |
| EZ RV Credit | See site | See site | No credit needed | See site |
| Huntington | See site | See site | See site | See site |
| Prosper | $2,000 – $50,000 | Up to 6 years | See site | Fast funding |
| Bank Iowa | See site | See site | See site | See site |
Top Rated RV Financing Providers
1. Solarity Credit Union
Solarity Credit Union operates with a focus on bright, straightforward banking. They provide specialized loans for RVs and motor sports, aiming to make the process as simple as possible for their members. Their approach is built around providing expert guidance and knowledgeable support, which is vital when dealing with the non-standard depreciation schedules of recreational vehicles.
This option is ideal for those who prefer a community-focused banking experience. Unlike a massive national conglomerate where you are just another account number, a credit union often provides a personalized touch. If you value digital tools and the stability of a federally insured institution, this credit union offers a professional path toward your next adventure. Their specialized knowledge means they are less likely to be surprised by the complexities of a luxury motorhome loan.
Pros:
- Expert guidance from knowledgeable employees
- Modern digital banking tools
- Federally Insured by NCUA
Cons:
- Requires membership or specific eligibility
2. Elite Direct Finance
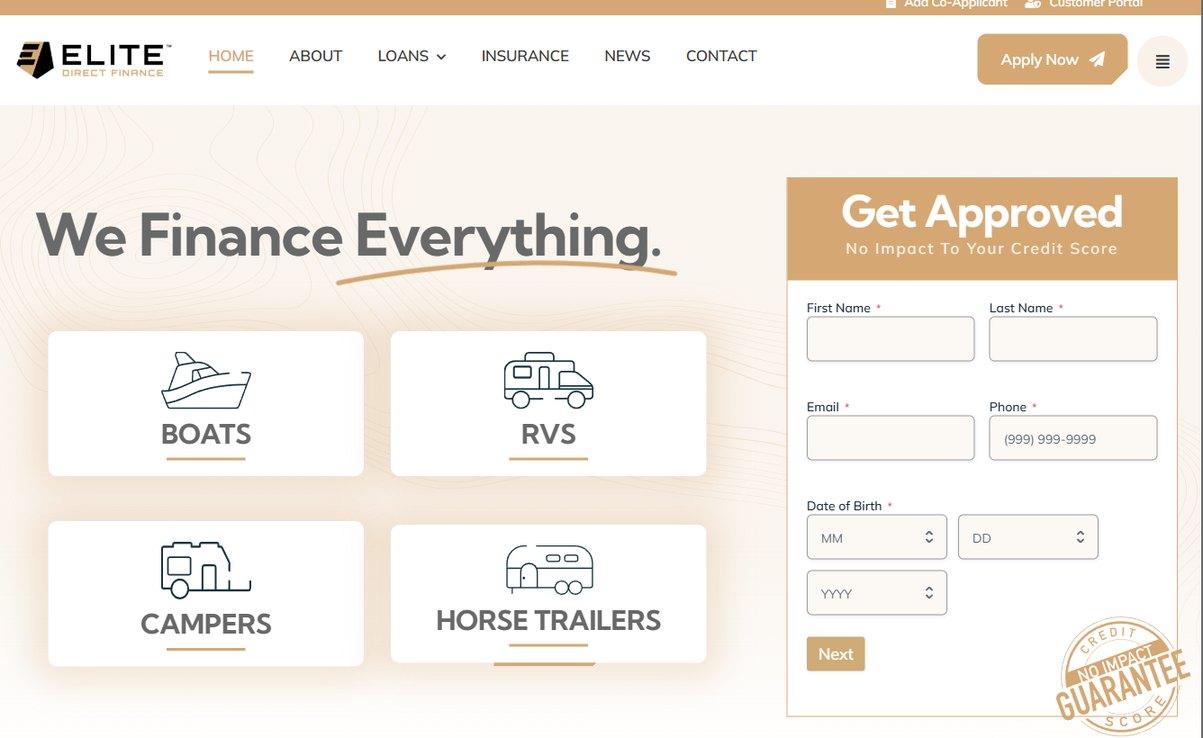
Elite Direct Finance acts as a bridge between borrowers and a wide network of lenders. They specialize in a massive variety of vehicles, including boats, campers, and even horse trailers. Their goal is to make the approval process feel almost instantaneous, which is critical when you are competing against other buyers at a seasonal RV show.
This is a fantastic choice for anyone who feels intimidated by complex paperwork or doesn’t want to spend weeks negotiating with multiple banks. They offer long-term flexibility with terms reaching up to 20 years, making large purchases feel much more manageable for the average budget. For example, a high-end $150,000 motorhome that might have an overwhelming monthly payment on a 10-year loan becomes much more approachable when spread over a two-decade term.
Pros:
- Longest terms up to 20 years
- Network of multiple lenders
- Covers boats and horse trailers
- No credit impact for initial approval
Cons:
- Approval depends on the specific lender in their network
3. JetzLoan
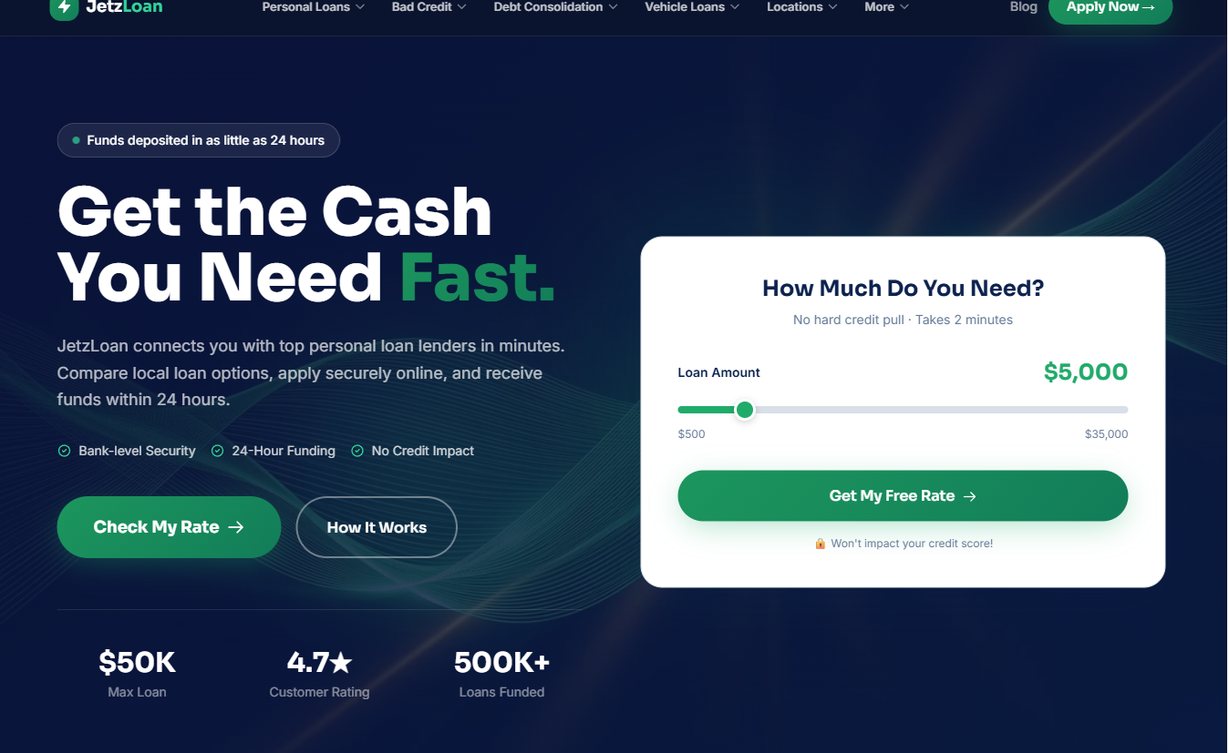
JetzLoan is built for speed and efficiency in a digital-first world. They connect users with top personal loan lenders in just a few minutes. This is perfect for the traveler who has found the perfect rig—perhaps a rare vintage trailer or a used camper listed on a private marketplace—and needs the cash to secure it immediately before someone else steps in. (jetzloan.com)
Because they offer a “no hard credit pull” option, you can explore your rates without worrying about your score dropping. This is a critical feature for budget-conscious shoppers who want to “window shop” various loan scenarios without the penalty of multiple inquiries on their credit report. It is a high-speed, low-stress method for securing up to $50,000 for your vehicle needs, making it an excellent supplement to a down payment.
Pros:
- Funding in as little as 24 hours
- No impact to credit score during check
- Simple, 2-minute application process
Cons:
- Loan amounts are capped at $50,000
4. EZ RV Credit
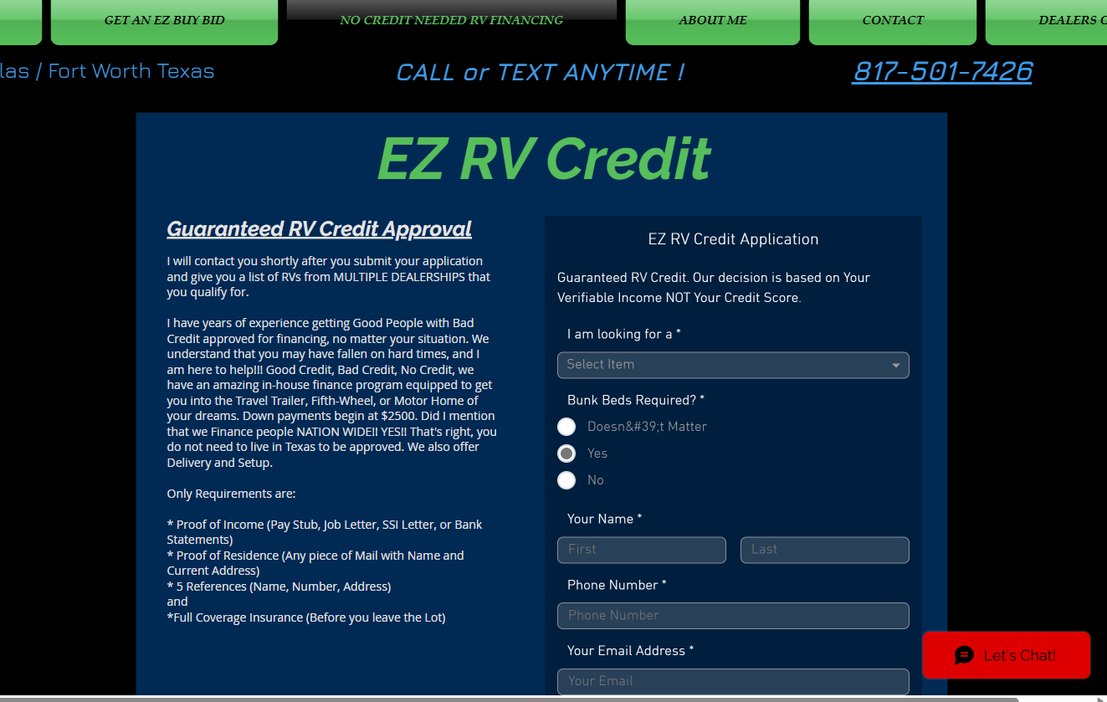
EZ RV Credit is the specialist for those who have faced financial hurdles in the past. They specialize in “Good People with Bad Credit,” offering an in-house finance program designed to get you into a fifth-wheel or motor home despite your history. They understand that a past bankruptcy or a period of unemployment shouldn’t permanently bar you from the freedom of the open road.
This lender is a lifeline for those who might be rejected by traditional banks. While you might encounter more stringent requirements regarding your current income or employment stability, they are willing to look at the person behind the score. With down payments starting at $2,500, they prioritize getting people on the road rather than strictly judging their past financial mistakes. This can be the difference between renting a camper for a weekend and finally owning your own mobile sanctuary.
Pros:
- No credit needed options available
- Nationwide service availability
- Low down payments starting at $2,500
Cons:
- May require higher down payments for certain profiles
5. Huntington
Huntington is a full-service powerhouse that offers much more than just simple lending. They provide a comprehensive suite of financial services, from investing and retirement planning to life insurance and checking accounts. This makes them an excellent partner for those who are planning for long-term nomadic living and want to integrate their travel expenses into a larger wealth management strategy.
This is the best choice for a borrower who wants their RV loan to be part of a larger, holistic financial strategy. For instance, if you are retiring and plan to travel full-time, Huntington can help structure your loans alongside your retirement withdrawals to maximize your cash flow. They focus heavily on customer satisfaction and provide a highly-rated mobile banking experience for busy travelers who need to manage their finances from a campsite with limited Wi-Fi.
Pros:
- Highly-rated mobile and online banking
- Comprehensive suite of financial products
- Strong focus on customer service
Cons:
- May be more rigid than specialized sub-prime lenders
6. Prosper
Prosper is a prominent name in the online personal loan space, known for its efficiency and high ratings. They offer terms up to 6 years, which provides a structured way to pay off your recreational vehicle without long-term debt drag. Because these are personal loans, they are often unsecured, meaning you aren’t putting your vehicle at risk in the same way a traditional RV loan might.
If you need a quick injection of cash between $2,000 and $50,000—perhaps for a major upgrade like a new lithium battery bank, a high-end solar array, or a new generator—Prosper is a streamlined option. They emphasize a fast, secure, and transparent digital experience that fits into a modern lifestyle. It is a great tool for those who already have an RV but need extra capital to make it road-ready for a long trek.
Pros:
- Up to 6-year terms available
- Fast, secure online process
- High customer satisfaction ratings
Cons:
- Loan amounts are relatively modest compared to specialized RV loans
7. Bank Iowa
Bank Iowa combines high-tech banking solutions with a hometown feel. They have a long history of serving communities, having celebrated 50 years of operation, which speaks to their stability and local commitment. This longevity is a key indicator of how they handle economic downturns and changing market conditions in the recreational vehicle sector.
This is a solid choice for those who prefer a lender that understands the value of community and local roots. They offer a blend of innovation and traditional banking values for their diverse client base. If you are buying from a local dealer or a private seller in the Midwest, a community-focused bank like this may have more flexibility in terms of local knowledge and relationship-based lending than a distant, automated online lender.
Pros:
- Long-standing history and stability
- Mix of high-tech and community-focused service
- Broad range of personal and business banking
Cons:
- Primarily focused on specific regional community needs
Understanding the Total Cost of Ownership
A common mistake in RV financing is focusing solely on the “sticker price” and the monthly payment. To truly budget for a life on the road, you must consider the Total Cost of Ownership (TCO). This includes more than just the principal and interest of your loan. When evaluating a lender, you should also factor in how their terms interact with other mandatory expenses.
First, consider insurance requirements. Many lenders require you to carry comprehensive and collision insurance, which can be significantly more expensive for a high-value motorhome than for a standard passenger car. Second, think about the depreciation factor. Unlike real estate, an RV is a depreciating asset. If you take a 20-year loan with a low interest rate, you may find yourself “upside down” or “underwater” on the loan—meaning you owe more to the bank than the RV is worth—within just a few years of ownership. This is why shorter terms, despite higher monthly payments, are often mathematically superior for long-term wealth building.
Third, account for the “hidden” costs of maintenance and storage. If your financing allows you to keep more cash in your pocket each month, you should immediately divert some of those savings into a dedicated maintenance fund. Unexpected repairs, such as a failed air conditioner or a transmission issue, can cost thousands of dollars. A lender that offers flexible repayment options or allows for easy extra payments can be an invaluable ally when these inevitable maintenance costs arise.
Avoiding Pitfalls in RV Financing
Before signing any paperwork, it is vital to look at the fine print. Many travelers make the mistake of only looking at the monthly payment. While a low payment looks great on paper, it often means you are paying much more in interest over a longer term. For example, a 20-year loan at 7% interest will cost significantly more in total interest than a 10-year loan at 6%, even if the 20-year monthly payment feels much easier to manage on a month-to-month basis.
Always ask about prepayment penalties. Some lenders charge you a fee if you decide to pay off your loan early, which can be a major headache if you come into extra cash through a bonus or a tax refund. Additionally, ensure you understand whether the loan is secured by the RV itself, which gives the lender the right to repossess the vehicle if payments are missed. This is a “title loan” structure, and the stakes are much higher than a personal loan.
Finally, do not be afraid to shop around. The difference in interest rates between two lenders can amount to thousands of dollars over the life of the loan. A difference of even 1% can result in a massive amount of wasted capital over a decade. Using tools that allow for no-impact credit checks can give you the leverage you need to find the best possible deal without damaging your ability to secure other credit, such as a mortgage or an auto loan, in the future.