
Top 6 Lenders for HVAC AC Financing: A 2026 Comparison
Last updated: 2026-11-10
When your furnace quits in the middle of a blizzard, the sudden bill feels like a punch to the gut. Homeowners often find themselves staring at massive repair quotes that threaten to wreck their monthly budget. Finding a way to pay for these systems is just as vital as picking the right unit. An HVAC emergency doesn’t care if your savings account is ready for a five-figure hit, and a freezing living room can make it hard to think clearly about money.
Choosing a lender involves more than just looking at the monthly payment. You have to weigh how fast you get the cash against what the interest will cost you over time. A lender might offer a tiny monthly payment by stretching a loan out over 72 months. However, once you calculate the total interest, you might realize you have paid for the furnace twice.
This list looks at different ways to pay, from traditional bank loans to flexible lease-to-own setups. The goal is to help you find an option that keeps your house comfortable without breaking the bank. We compared several providers to see which ones actually deliver when you need them most.
- Wells Fargo
- JetzLoan
- Breeze Lease Purchase
- Avant
- LightStream
- VivaLoan
How These Financing Options Were Evaluated
We focused heavily on how fast you can get the money. HVAC issues rarely happen on a schedule, so speed is everything. We looked for providers with quick applications and clear terms so you aren’t sitting in a freezing house while waiting for paperwork to clear. A three-day delay on a mortgage is a nuisance, but a three-day delay on a furnace repair during a polar vortex is a health hazard.
Diversity in credit requirements was our next priority. Not everyone has a perfect credit score, yet nearly a third of Americans hit walls when applying for traditional loans. We included options for different financial profiles, from those seeking high-limit personal loans to those needing specialized leasing programs for essential equipment. We checked if a lender required “prime” status or if they worked with “credit builders.”
| Lender Name | Loan Amount Range | Funding Speed | Credit Requirement |
|---|---|---|---|
| Wells Fargo | see site | see site | requires approved credit |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Breeze Lease Purchase | see site | Fast options | Regardless of credit status |
| Avant | see site | see site | Flexible choices |
| LightStream | see site | see site | see site |
| VivaLoan | $100 – $15,000 | As soon as tomorrow | All credit types welcome |
1. Wells Fargo
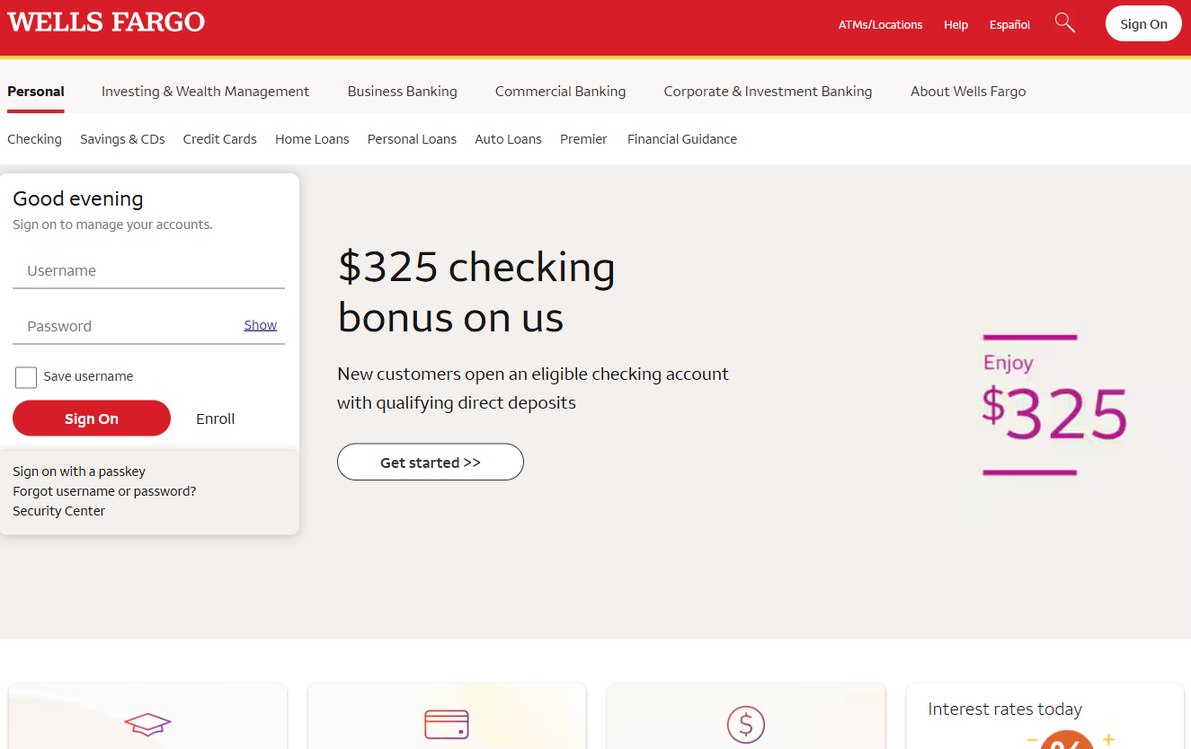
If you prefer the stability of a major institution, Wells Fargo offers a traditional route. This works well for homeowners who already have approved credit and want to fold HVAC costs into their existing financial management. You might use a personal loan or a home equity line of credit (HELOC) depending on how much the installation costs.
This is a solid choice if you already have a long-standing relationship with a large bank. If you have been a customer for years, your pre-approved rates might be much lower than those from third-party lenders. However, don’t expect lightning speed for an emergency. Traditional banks often require mountains of documentation regarding your income and assets.
Pros:- Established, reputable financial institution
- Integration with existing banking services
- Potential for 0% APR offers for certain projects
- Requires approved credit to qualify
- Traditional application processes can be slower
2. JetzLoan
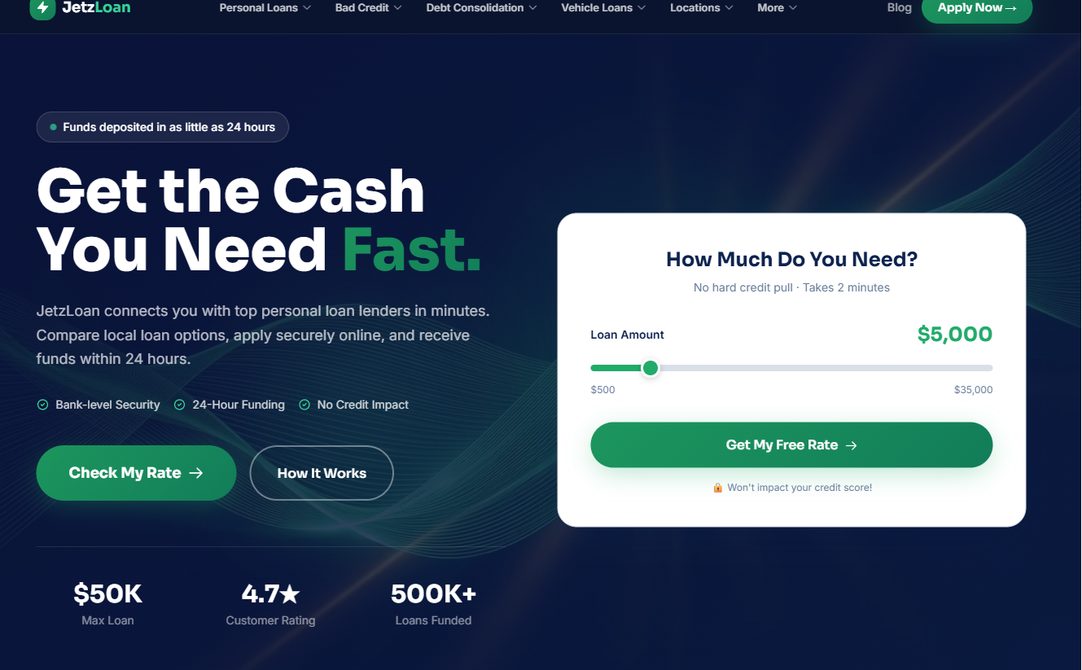
JetzLoan works as a high-speed bridge for people needing cash quickly to fix a broken AC. It connects users with various lenders in minutes, making it a powerhouse for anyone facing an urgent climate crisis. Instead of fighting through a single bank’s bureaucracy, JetzLoan acts as a digital conduit to a wide network of creditors.
The ability to check rates without a hard credit pull is a standout feature. You can shop around and see what you qualify for without risking a dip in your credit score. For a homeowner on the fence, seeing a “soft” quote allows for comparison shopping without any actual financial penalty to your credit standing.
Pros:- Funds can be deposited in as little as 24 hours
- No hard credit pull to check rates
- Quick 2-minute application process
- Maximum loan amount caps at $35,000
- Connecting to lenders involves multiple steps
3. Breeze Lease Purchase
If your credit history is a bit bumpy, Breeze Lease Purchase is built for you. They focus on helping the 29% of Americans who struggle to secure traditional contractor financing. They understand that a broken furnace is a necessity rather than a luxury, so they tailor their approach to fit that reality.
This is not a standard loan; it is a lease-to-own model. You are essentially renting the equipment with the intent to own it fully once the term ends. This is helpful for replacing water heaters or heat pumps when you need the unit running immediately but can’t get a bank loan due to a low FICO score.
Pros:- Flexible lease-to-own options available
- Designed for those with less-than-perfect credit
- Covers parts as well as full HVAC equipment
- Lease-to-own can be more expensive long-term
- Specific to equipment rather than general cash
4. Avant
Avant targets the middle ground of the market. They offer solutions for people who need to move forward financially despite life’s unexpected hurdles. Their tools include various credit cards and installment loans, often serving the “near-prime” segment—people with steady income who might have a few blemishes on their credit report.
This is a versatile option if your project is part of a larger home improvement plan. If you are also updating windows or insulation to improve efficiency, Avant’s flexible choices might align with those broader goals. They offer a much more personalized experience than the massive, impersonal mega-banks.
Pros:- Flexible choices for different financial journeys
- Provides various tools like credit cards and loans
- Friendly support for navigating financial choices
- Not specifically specialized in HVAC equipment
- Approval is subject to individual financial profiles
5. LightStream
LightStream by Truist is a specialized lending arm that offers loans for practically anything. This makes them a strong contender for major HVAC installations that require significant upfront capital, such as a full multi-zone system or a high-efficiency geothermal setup.
They are a dedicated service for people with specific, large-scale needs. Unlike a standard personal loan that might have rigid restrictions, LightStream’s structure is built for major life expenses. It is an efficient option for consumers who want to work through an established bank like Truist and benefit from competitive rates.
Pros:- Covers a vast range of personal needs
- Backed by Truist Financial Corporation
- Professional and structured lending process
- Currently not accepting new applications in some contexts
- Strictly follows traditional banking requirements
6. VivaLoan
VivaLoan is the go-to for those needing a smaller amount of cash to get through a crisis. With loans starting as low as $100, it is incredibly flexible for minor repairs or small part replacements. This is perfect for a new capacitor or a thermostat that doesn’t require a full system overhaul.
The speed here is hard to beat. Once a request is connected, funds are typically available via direct deposit as soon as the next business day. It is an excellent stop-gap measure to keep your home habitable while you save up for a more permanent, larger-scale solution later on.
Pros:- Extremely low minimum loan amounts
- Funds can arrive as soon as tomorrow
- Welcomes all credit types
- Maximum loan amount is limited to $15,000
- Short-term nature may lead to higher frequency of borrowing
Comparing Loan Types: Personal Loans vs. Lease-to-Own
When deciding how to fund your HVAC repair, you must understand the difference between a personal loan and a lease-to-own agreement. A personal loan is a lump sum of cash you receive upfront. Once that money hits your account, you are responsible for the debt, regardless of whether the technician does the job correctly. This gives you total control over which contractor you hire.
In contrast, a lease-to-own agreement is a service-based contract. You aren’t just borrowing money; you are entering a contract to use equipment with the intent to purchase it later. This is often easier to qualify for because the equipment itself acts as collateral. If you can’t make payments, the leasing company can reclaim the unit. This makes it easier for those with low credit, but it often comes with a higher total cost.
| Feature | Personal Loan | Lease-to-Own |
|---|---|---|
Approval Difficulty |
High (Credit-score dependent) | Lower (Asset-backed) |
Control over Funds |
Total control | Limited to equipment/service |
Total Cost |
Lower (if credit is good) | Higher (due to lease terms) |
Strategic Steps for Securing Emergency Financing
If you find yourself in an emergency, follow these steps to get the best terms without ruining your financial stability:
- Get Multiple Quotes: Before applying for a loan, get at least three quotes from different HVAC contractors. You won’t know how much you need to borrow until you know the exact cost of the repair.
- Check Your Soft Credit Score: Use a free service to check your score. This tells you immediately whether you should aim for a traditional bank like Wells Fargo or a more flexible provider like JetzLoan or VivaLoan.
- Inquire About “In-House” Financing: Many large HVAC companies have partnerships with financing firms. Always ask the technician if they offer in-house financing. They may have exclusive rates that aren’t advertised.
- Calculate the “Effective APR”: If a lender offers 0% interest for 12 months but charges a $500 “origination fee,” your actual cost is much higher than it looks. Always look at the total amount you will have paid by the end.
- Verify the Timeline: If your home is currently 50 degrees inside, speed is your priority. If you have a working furnace but it’s just inefficient, you have the luxury of waiting for a better interest rate.
Before signing any paperwork, look at the total cost of borrowing. It is easy to get distracted by a low monthly payment, but a longer term can mean you pay thousands more in interest over the life of the loan. Always ask for the total repayment amount. If the monthly payment is $100, but the term is 10 years, you are paying $12,000 for a $5,000 furnace.
Avoid the mistake of rushing into a high-interest agreement just because you are uncomfortable in your house. While heat is unpleasant, a predatory loan can cause financial distress for years. Compare the speed of a service like JetzLoan against the stability of a provider like Wells Fargo to see which fits your specific emergency. A well-informed decision today prevents a massive financial headache three years down the road.