
The Top 6 Lenders for a 550 Credit Score Personal Loan in 2026
Last updated: 2026-11-10
Walking into a bank with a 550 credit score often feels like trying to enter a VIP lounge without an invitation. Most traditional lenders see that number and immediately close the door. You end up stuck in a sea of high-interest offers and confusing fine print. It can be incredibly demoralizing when your financial past feels like an anchor holding you back from your future.
The rules of borrowing have changed quite a bit lately. Finding a way to bridge the gap between where you are and where you want to be is entirely possible if you know where to look. The difference between a “predatory” lender and a “specialized” one usually comes down to transparency and the intent of the loan. This list focuses on lenders that specifically look past a low score to see the actual person behind the paperwork.
- FastLendGo
- OneMain Financial
- Avant
- Max Cash
- LendingPoint
- Upgrade
How These Lenders Were Evaluated
Picking the best options for someone in the “poor” credit range requires a different lens than standard reviews. We didn’t just hunt for the lowest interest rates. Instead, we focused on accessibility and the likelihood of approval. A lender that offers a 5% interest rate is useless if they won’t even look at your application because of your credit history.
For a borrower with a 550 score, the “best” lender is one that provides a realistic path to approval without hidden fees that could exacerbate an existing financial crisis. We looked for providers that offer a clear way forward, whether that means quick cash for an emergency or a structured way to consolidate mounting debt.
We specifically analyzed the “soft pull” vs. “hard pull” processes to ensure you can check your eligibility without damaging your score further. Each entry was scrutinized based on their willingness to work with subprime borrowers, the speed of their funding, and the flexibility of their loan amounts.
| Lender | Loan Amounts | Speed of Funding | Credit Requirements |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Fast access | Bad/Fair Credit |
| OneMain Financial | $1,500 – $35,000 | As soon as 1 hour | See site |
| Avant | See site | Quick funding | As low as 550 |
| Max Cash | $250 – $10,000+ | In minutes | Bad Credit |
| LendingPoint | $1,000 – $36,500 | Fast funding | Fair Credit |
| Upgrade | Up to $50,000 | Fast funding | See site |
Top Ranked Lenders for Low Credit Scores
1. FastLendGo
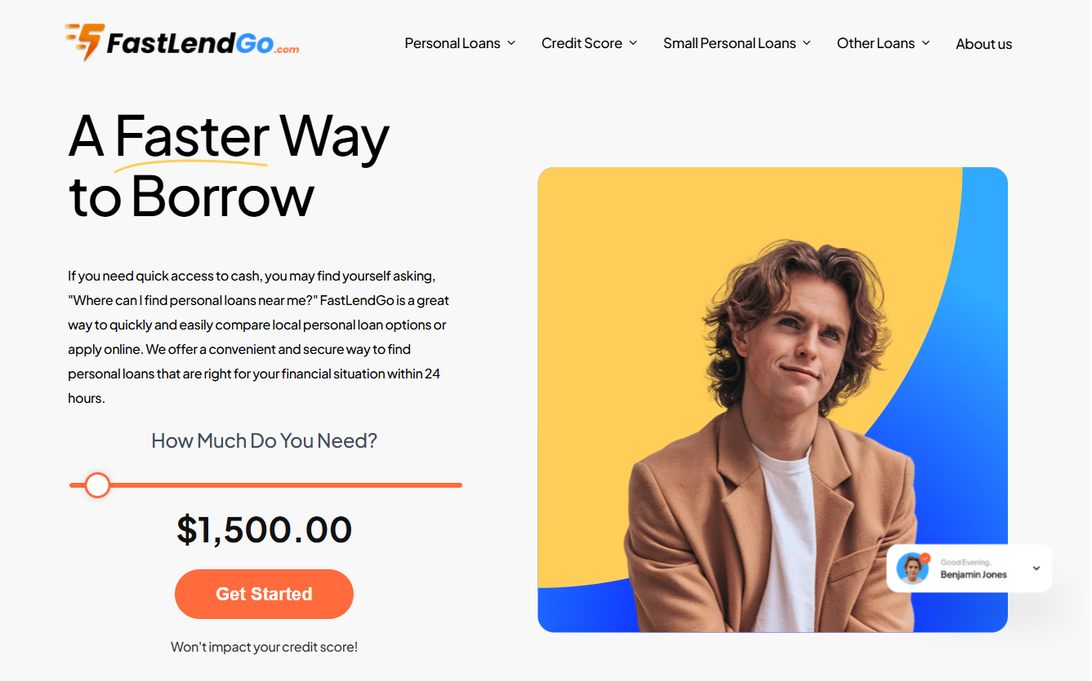
FastLendGo works for those who need quick access to cash without the usual mountain of red tape. They cater to people in various financial situations, from those needing small emergency loans to those looking for larger sums for auto or dental repairs. Many large-scale banks use automated “no” responses for scores under 600. FastLendGo‘s model is built around the immediate necessity of the borrower.
This lender is a solid choice for individuals who need flexibility in their loan purpose. Whether you are tackling a roof repair or just need a small cushion to get through the month, their model is built for speed and accessibility. They understand that a broken water heater or a car repair can trigger a domino effect of late fees if not addressed immediately.
Getting cash quickly can be a lifesaver when life throws a curveball. They focus on the immediate problem rather than a long, drawn-out deliberation. If you need to fix something today, their setup is designed to move at your pace.
Pros:- Covers a wide variety of specific needs like dental or auto repair
- Offers various loan sizes starting as low as $500
- Specialized options for high-income individuals or first-time borrowers
- Limited information on specific interest rate ranges provided
2. OneMain Financial
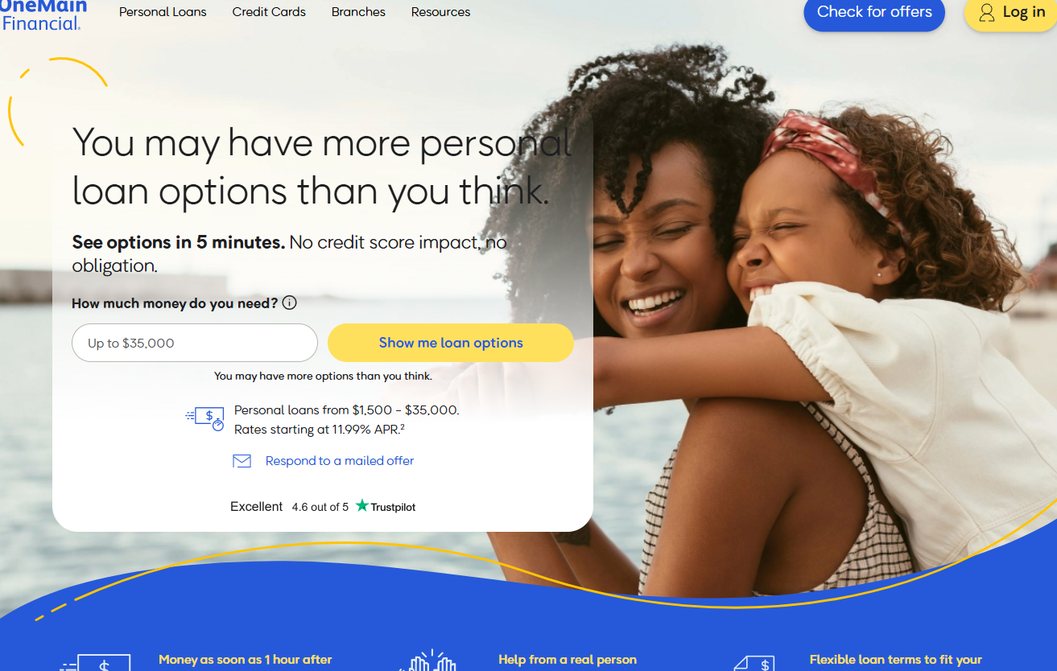
OneMain Financial is a powerhouse for those who prefer a more personal touch. While they offer a seamless online application, they maintain a massive network of over 1,300 physical branches where you can speak with a real person face-to-face. This “human element” is vital when your credit score is a 550. A loan officer can often look at your income stability or employment history to make up for a low FICO score in ways a computer algorithm cannot.
They are ideal for larger financial hurdles, providing significant loan amounts up to $35,000. If you need money to keep moving forward and want the security of a physical location to resolve disputes or ask questions about repayment, this is a very strong contender for your consideration.
Sometimes you just want to look someone in the eye when talking about your money. Having that option can make a world of difference if your paperwork is a bit messy. It turns a digital transaction into a real conversation.
Pros:- Extremely fast funding, potentially 1 hour after signing
- Large loan amounts up to $35,000
- Physical branches available for in-person support
- Requires a credit check for some offers
3. Avant
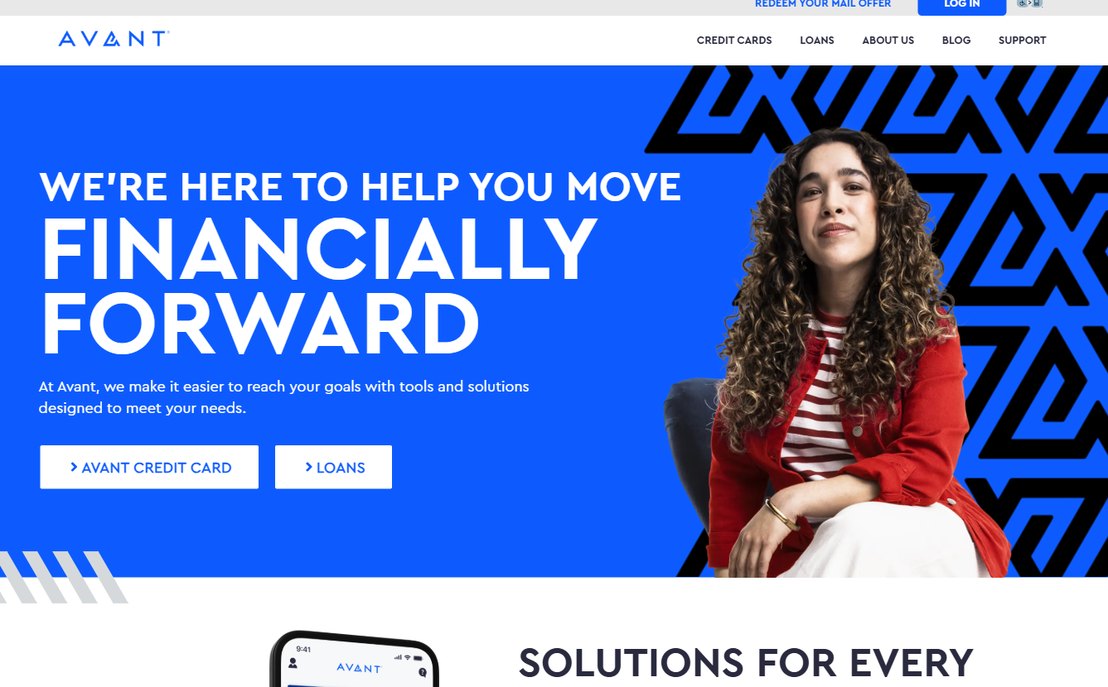
Avant has carved out a niche by specifically targeting the gap between “bad” and “good” credit. They are known for their efficiency, often providing answers to applicants quickly, making them a favorite for those in urgent situations. Their digital-first approach means you aren’t sitting in a waiting room; you are managing your application from your smartphone.
If you are sitting on the fence with a score around 550, Avant is worth the look. They provide tools to help you move financially forward, offering everything from installment loans to credit cards to help manage your journey. They focus on the “why” behind the score, recognizing that a single medical bill or a period of unemployment shouldn’t define your borrowing potential forever.
Their interface is built for the modern era. You can handle the whole process without ever leaving your couch. It is a streamlined way to see where you stand without a lot of unnecessary friction or waiting.
Pros:- Considers applicants with scores as low as 550
- Offers multiple products like credit cards and installment loans
- Fast approval process
- Terms and rates are not explicitly detailed for all credit tiers
4. Max Cash
Max Cash is the go-to option for those who need immediate, small-scale relief. Their system is designed for speed, allowing users to inquire about personalized products in just a few minutes without any initial obligation. This is particularly useful when you are unsure if you can qualify and don’t want to risk a “hard inquiry” that could drop your score even further.
They offer a tiered approach to borrowing, starting from very small amounts like $250 and scaling up to over $10,000. It is a versatile “one-stop shop” for those who might need a quick cash advance or a title loan instead of a traditional personal loan. This flexibility is critical for those who need to solve a problem today rather than next week.
Sometimes you just need a quick fix to keep the lights on. Max Cash handles those smaller, urgent needs without making you jump through the hoops required by a massive bank. It is a practical option for immediate problems.
Pros:- Very low entry point for loans starting at $250
- Quick, personalized inquiry process
- No obligation to move forward after the initial inquiry
- High variety of products can be overwhelming or confusing
5. LendingPoint
LendingPoint focuses on the “fair credit” demographic, offering a way to unlock possibilities that might be closed elsewhere. They specialize in structured loans meant for debt consolidation, medical expenses, or home improvements. Their underwriting process is often more sophisticated than “payday” style lenders, looking at your broader financial health rather than just a three-digit number.
If you are looking to clean up your financial slate by paying off high-interest credit cards, LendingPoint provides the necessary ammunition. Their loans are designed to be a tool for long-term stability rather than just a temporary fix. By consolidating several small, high-interest debts into one manageable monthly payment, you can actually start repairing your credit score through consistent, on-time payments.
It is about playing the long game. Instead of juggling five different due dates, you have one single target to hit every month. This structure can take a massive amount of mental weight off your shoulders.
Pros:- Loans up to $36,500 available
- No impact on credit score when checking your rate
- Specifically designed for debt consolidation
- Likely requires a “fair” rather than “poor” score for best terms
6. Upgrade
Upgrade is a modern, tech-forward option that integrates several financial services into one ecosystem. From personal loans to rewards checking accounts, they aim to be a comprehensive partner in your financial life. Their platform is designed for the modern consumer who wants to manage everything from a single dashboard.
They are a great fit for those looking for larger sums to fund major purchases or business needs. With a massive customer base, they offer a variety of tools designed to help you manage your money more effectively every day. Their structure is designed to scale with you: as your credit score improves through responsible use, you may find more competitive opportunities within their ecosystem.
Think of it as a digital wallet that grows with you. As you get your finances in order, the tools available to you can expand. It is a way to keep all your financial moving parts in one place.
Pros:- Large loan amounts up to $50,000
- Offers rewards and cash back through their checking accounts
- Fast rate checking that won’t impact your score
- May require a higher credit tier for the most competitive rates
The Real Cost of Borrowing: Understanding APR vs. Interest Rate
When browsing these lenders, you will see two numbers that look similar but are fundamentally different: the Interest Rate and the Annual Percentage Rate (APR). For a borrower with a 550 score, understanding this distinction is the difference between getting out of debt and falling deeper into it.
The interest rate is the cost you pay each month to borrow the money. However, the APR is a more comprehensive figure that includes the interest rate plus any lender fees, such as origination fees or processing costs. For example, a loan might have a 15% interest rate, but if there is a $500 upfront fee, the APR could jump to 18% or 20%. Always use the APR as your primary comparison tool when shopping between different lenders; it is the only way to see the “true” cost of the money you are borrowing.
Preparation Checklist: How to Increase Your Approval Odds
Even with specialized lenders, your application will move much faster—and your chances of approval will rise—if you come prepared. Don’t let a simple paperwork delay stall your funding when you need it most. Before you hit “apply,” ensure you have the following ready:
- Proof of Income: This is often the most critical factor for subprime lenders. Have your two most recent pay stubs, a W-2, or your last three months of bank statements ready to upload.
- Identity Verification: A valid, unexpired government-issued ID (Driver’s License or Passport) is mandatory.
- Proof of Residence: A recent utility bill (water, electric, or gas) can be used to prove your physical address.
- Debt List: If you are applying for debt consolidation, have a list of the exact balances and interest rates of the debts you intend to pay off. This shows the lender you have a strategic plan.
- Bank Account Details: Since most of these lenders use ACH transfers for fast funding, you will need your routing and account numbers ready to go.
Navigating the Borrowing Process
When you are dealing with a 550 credit score, the temptation to grab the first offer you see is incredibly strong. It is like being thirsty in a desert; you might be tempted to drink something that isn’t actually water. Always read the fine print regarding APRs and any potential prepayment penalties before you sign anything. Prepayment penalties are particularly dangerous; they are fees charged to you if you try to pay your loan off early, which effectively punishes you for being financially responsible.
Mistakes often happen when borrowers focus solely on the monthly payment amount. While a low monthly payment feels great today, a longer loan term means you will pay significantly more in interest over the life of the loan. For example, a $5,000 loan with a 5-year term at 20% interest will cost you much more in total than a 2-year term at the same rate, even though the monthly payment for the 5-year term is much smaller. Always look at the total cost of the loan to see the real price of your borrowing.
Finally, remember that a personal loan should be a tool for improvement, not a way to dig a deeper hole. Use these funds to consolidate high-interest debt or cover essential repairs that prevent further financial damage. If you use a loan to fund lifestyle expenses you cannot afford, you are simply running in place. The goal is to use this temporary liquidity to build a foundation that eventually allows you to walk into those “VIP” banks with confidence.