
The 5 Best Lenders for Uber Drivers with Bad Credit in 2026
Last updated: 2026-11-10
Driving for rideshare apps is a grind that doesn’t wait for a perfect credit score. When a transmission starts making noise or a sudden medical bill arrives, you need cash immediately. Relying on a traditional bank can feel like running a marathon through sand when your financial history isn’t pristine. For a driver, a single mechanical failure isn’t just a repair bill. It is a total loss of income during the repair window, creating a secondary crisis that can spiral without fast intervention.
This list helps gig workers find their way through the murky waters of alternative lending. Choosing a lender involves more than just hunting for the lowest interest rate. You need a partner that understands the irregular income patterns of a 1099 worker. Speed and accessibility are the real currencies here. Whether you are managing seasonal surge pricing or unpredictable platform payouts, your lender needs to be as agile as your driving schedule.
- FastLendGo
- Giggle Finance
- Elite Personal Finance
- NetCredit
- World Finance
How These Lenders Were Evaluated for Gig Workers
The selection process focused on accessibility for those with non-traditional income streams. Standard banks often demand pay stubs that look nothing like the weekly earnings reports from Uber or Lyft. We looked for lenders that prioritize your actual cash flow over a static, historical credit score. A traditional lender might see a $1,200 week and a $400 week and flag you as “unstable,” but a gig-focused lender looks at your annual aggregate and your ability to pay based on weekly velocity.
We also prioritized how fast you get funded and the ability to handle “bad” or “fair” credit tiers. A lender that takes two weeks to approve a loan is useless when your car needs a new alternator to keep you on the road. We analyzed the application-to-funding timeline, the transparency of disclosure documents, and whether their underwriting models account for 1099 tax structures. The following comparison highlights the most viable options available right now.
| Lender Name | Max Loan Amount | Credit Requirements | Funding Speed | Best For |
|---|---|---|---|---|
| FastLendGo | See site | Bad, Fair, Good, Great | See site | Emergency Repairs |
| Giggle Finance | $15,000 | 1099 / Self-Employed | Minutes | Small Business/Gig Growth |
| Elite Personal Finance | $5,000 | 400 – 500 Credit Score | 5 Minutes | Ultra-Low Credit |
| NetCredit | $10,000 | Advanced Algorithms | Same-day availability | Flexible Terms |
| World Finance | $450 (Minimum) | No matter the score | Same-day | Quick Cash/Tax Needs |
1. FastLendGo
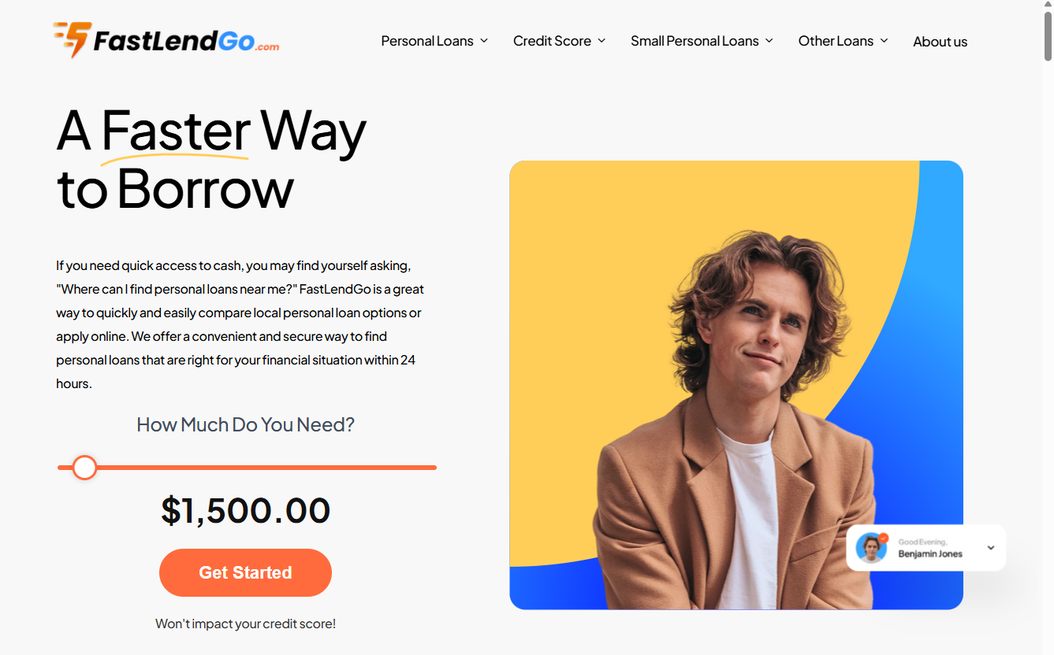
FastLendGo operates as a versatile bridge for those facing sudden financial hurdles. They offer a wide spectrum of products, ranging from small $500 loans to larger $5,000 personal loans. This flexibility is vital for drivers who might just need a quick fix or a larger capital injection for vehicle upgrades. For example, if you need a $600 set of new tires to pass a vehicle inspection, a small-scale loan is far more appropriate than a high-interest long-term debt instrument. (fastlendgo.com)
The platform is designed for speed, catering specifically to those looking for personal loans near them without the traditional banking headache. Whether you are dealing with an unexpected dental bill or an auto repair, their system is built to match your specific credit tier. They understand that a driver’s needs change from week to week, and their product lineup reflects that volatility.
Pros:
- Covers a wide range of credit scores from bad to great.
- Specific options for auto and motorcycle repair financing.
- Quick comparison of local personal loan options.
Cons:
- Does not specify a maximum loan ceiling for all users.
- Focus is heavily on quick access rather than long-term low interest.
2. Giggle Finance
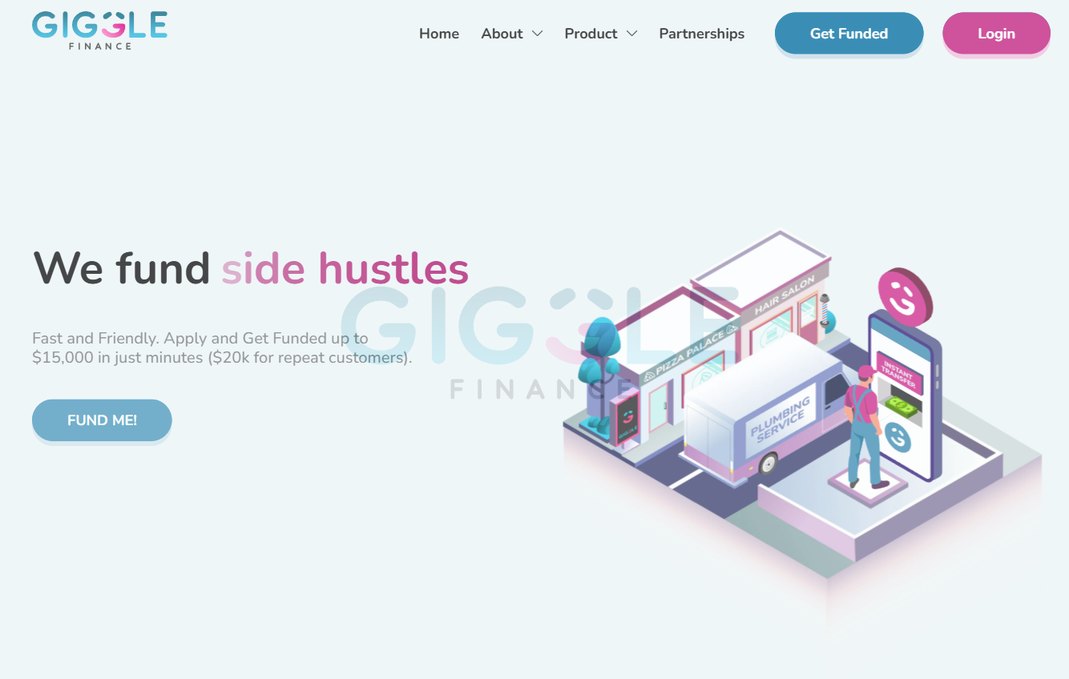
Giggle Finance is built specifically for side hustlers and the 1099 warriors. They understand that a driver’s income doesn’t always look like a standard salary. This lender focuses on the “gig” economy, making them a natural fit for Uber and Lyft drivers looking to scale their operations. While a bank might see your lack of a W-2 as a risk, Giggle Finance views it as your standard operating procedure.
They offer substantial amounts, reaching up to $15,000 in just minutes. For repeat customers who have proven their reliability, that limit can even climb to $20,000. This is particularly useful for drivers looking to transition from a single vehicle to a multi-car fleet or those wanting to purchase a more fuel-efficient hybrid to increase their margins. It is a powerhouse for anyone looking to move from a side hustle to a legitimate small business venture.
Pros:
- Extremely fast funding, often within minutes.
- High loan limits for repeat customers.
- Tailored specifically for self-employed and 1099 workers.
Cons:
- Higher limits are reserved for repeat customers only.
- May be more restrictive for those with zero income history.
3. Elite Personal Finance
Elite Personal Finance is the “emergency room” of the lending world. They cater to those who have been told “no” by almost every other institution. With credit scores as low as 400 or 500, they provide a lifeline to drivers who are often ignored by the mainstream financial sector. This is critical for drivers who have experienced a series of financial setbacks and need a way to stabilize their situation without falling into the predatory cycle of payday loan shops.
Their model is designed to be a legitimate alternative to predatory payday loans. They offer personal loans of up to $5,000 with APRs that, while higher than prime loans, remain much more manageable than traditional high-interest debt traps. It is a quick, 5-minute approval process for those in a pinch, making it an ideal choice for urgent, non-negotiable expenses like a sudden utility shut-off notice or an unavoidable medical co-pay.
Pros:
- Accepts very low credit scores (400-500 range).
- Rapid 5-minute approval process.
- Provides a legitimate alternative to payday lenders.
Cons:
- APRs can be high for those in the lower credit tiers.
- Loan amounts are capped relatively low at $5,000.
4. NetCredit
NetCredit takes a more sophisticated approach to the lending process. Instead of just looking at a single, static number, they use advanced algorithms to look at a broader picture of your financial health. This is a massive advantage for drivers who may have “spiky” income due to seasonal demand or fluctuations in platform incentives. For instance, a driver might earn significantly more during the holiday surge, and NetCredit’s models are better equipped to recognize that seasonal pattern than a rigid scoring system.
They offer loans up to $10,000 with flexible terms that can be adjusted to fit your budget. The availability of same-day funding is a lifesaver when a car issue threatens your ability to earn the very money you need to repay the loan. By using alternative data points—such as consistent deposit history rather than just a FICO score—they offer a path to credit for the modern workforce.
Pros:
- Uses advanced algorithms rather than just a FICO score.
- Same-day funding availability for quick needs.
- Flexible terms to help manage repayments.
Cons:
- Eligibility is subject to complex algorithmic checks.
- Not as specialized for 1099 workers as niche gig lenders.
5. World Finance
World Finance is a dual-purpose provider that handles both personal loans and tax-related needs. For the driver who is struggling to get their tax refund or needs a small $450 bump to get through the week, this is a highly accessible option. They cater to all credit levels, making them a reliable safety net for a wide demographic of gig workers.
Their service is built around “worry-free” financing. They provide fixed interest rates and fast funds, which removes the moving target of variable interest when you are already stressed. Their ability to assist with tax preparation makes them a one-stop shop for the gig worker’s annual cycle, particularly during the high-stress window of January through April when tax obligations can feel overwhelming.
Pros:
- Provides both personal loans and tax preparation services.
- Fixed interest rates provide predictable payments.
- Same-day personal loans available.
Cons:
- Minimum loan amounts are quite low.
- The focus is on short-term fixes rather than large capital.
Comparing Loan Types: Which One Fits Your Crisis?
Understanding the difference between the types of loans available can save you hundreds of dollars in interest. Gig workers typically fall into one of three categories: the “Quick Fix,” the “Growth Capital,” or the “Survival Loan.”
| Category | Typical Use Case | Best Lender Example | Risk Level |
|---|---|---|---|
| Quick Fix | Tires, oil change, minor repair | World Finance | Low to Moderate |
| Growth Capital | New vehicle, bulk fuel purchase, business tax | Giggle Finance | Moderate |
| Survival Loan | Rent, medical, emergency utility bill | Elite Personal Finance | High (due to APR) |
If you are looking at a “Quick Fix,” your goal is minimal interest over a short period. If you are looking at “Growth Capital,” you are essentially investing in your ability to earn more, meaning the loan should be viewed as a business expense. If you are in a “Survival” situation, your priority is speed and immediate relief, but you must have a clear plan to pay it back quickly to avoid the high interest rates associated with emergency credit.
Preparing Your Documentation for Faster Approval
The biggest delay in the lending process isn’t usually the credit check—it is the verification of income. Because 1099 workers don’t have traditional W-2s, lenders need to see proof that your income is consistent and reliable. If you are applying for a loan to cover a sudden car repair, having your documentation ready can shave hours off the approval time.
Follow these steps to streamline your application:
- Download your weekly earnings summaries: Don’t rely on screenshots from your phone. Download the official PDF earnings reports from your Uber, Lyft, or DoorDash driver portal. These are much more likely to be accepted as official proof of income.
- Prepare your bank statements: Most alternative lenders will want to see the last 30 to 60 days of activity in the bank account where your platform payouts are deposited. Ensure these statements show the direct deposits from your rideshare provider.
- Have your tax returns handy: If you are applying for a larger amount (like $5,000 or more), a lender will likely want to see your most recent Schedule C from your tax returns to verify your annual income.
- Verify your vehicle status: If the loan is specifically for repairs, having an estimate from a mechanic ready can sometimes help expedite “purpose-specific” loan approvals.
By being proactive with your paperwork, you move from being a “risky applicant” to a “verified professional.” This shift in perception is often the difference between an instant approval and a rejection.
How to Choose Your Best Path Forward
The most common mistake drivers make is choosing a lender based solely on the first number they see. A high loan amount might look great, but if the interest rate is designed to keep you in debt for years, it is a trap. Always check the total cost of the loan, not just the monthly payment. A $1,000 loan with a $50 monthly payment might sound easy, but if that payment lasts for three years, you will end up paying double or triple what you borrowed.
Another pitfall is ignoring the fine print regarding “same-day” funding. Often, this requires you to have a specific type of bank account or to apply before a certain time of day. If your car breaks down at 9:00 PM on a Friday, a “same-day” lender might not actually help you until Monday. Always ask, “If I am approved right now, when will the cash actually be in my account?”
Finally, remember that your income is your greatest asset. When applying, have your most recent earnings statements from your rideshare app ready. Proving a consistent flow of cash, even if the amount varies, is much more effective than trying to hide your 1099 status from a lender. Transparency is your best tool for securing the best possible terms in a high-speed lending environment.