
Top 5 Lenders for Loans for Bad Credit in 2026
Last updated: 2026-11-10
Trying to fix your finances when your credit score is in the gutter feels like walking through a thick fog without a compass. Most traditional banks tend to slam the door shut the moment they see a low number on your report. It is incredibly discouraging when you need cash for an emergency or to consolidate debt. You might find yourself staring at a screen, watching “denied” messages roll in from major institutions, feeling like your financial history has become a permanent barrier to your future stability.
This ranking focuses on finding paths forward through the gloom. Selecting a lender in this category requires looking past just the interest rate. You have to weigh speed, the impact on your score during the application, and the actual amount of capital available to you. A high interest rate is often the price of accessibility, but you must distinguish between “expensive” and “predatory.” The goal is to find a lender that provides a bridge to a better situation rather than a trap that leads to further insolvency.
- JetzLoan
- LendingPoint
- MoneyLion
- Check City
- Acorn Finance
How These Lenders Were Evaluated
The selection process for this list involved looking at how these companies handle “subprime” or difficult credit profiles. It is not enough to simply offer money; the method of delivery matters immensely. A lender that performs a hard inquiry during the initial phase might hurt a score that is already teetering on the edge. We analyzed the friction points in the application process, the transparency of the fee structures, and the actual accessibility of funds for those with scores in the 500s or lower.
Criteria included the maximum loan limits offered, the speed of funding, and the specific types of credit products available. We looked for a balance between those who offer quick, short-term relief and those providing long-term structural solutions like debt consolidation or home improvement financing. Transparency in the application process was a major factor. We specifically looked for lenders that utilize “soft pulls” for initial quotes, allowing users to shop around without the penalty of multiple hard inquiries appearing on their reports.
| Lender Name | Max Loan Amount | Funding Speed | Credit Impact | Best For |
|---|---|---|---|---|
| JetzLoan | $50,000 | 24 Hours | No Hard Pull | Fast Funding |
| LendingPoint | $36,500 | See Site | No Impact Check | Debt Consolidation |
| MoneyLion | $100,000 | Fast/Expedited | Build Credit | Credit Building |
| Check City | See Site | Quick Cash | See Site | Short-term Cash |
| Acorn Finance | See Site | Fast | No Impact Check | Home Improvement |
1. JetzLoan
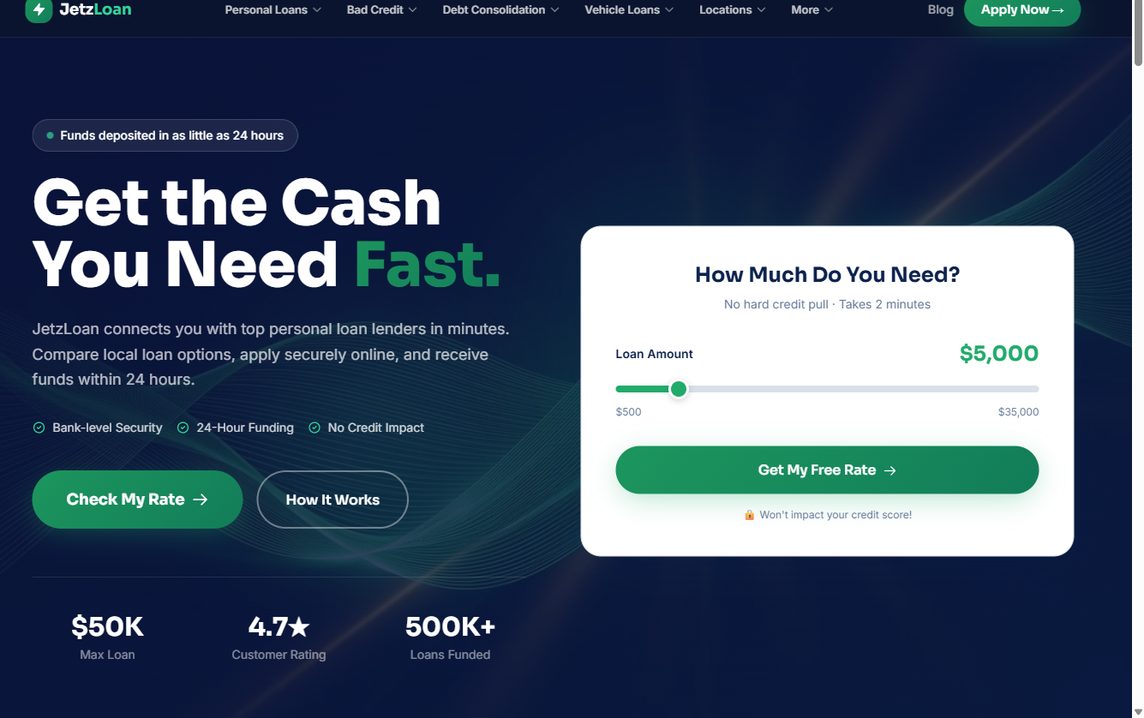
JetzLoan acts as a bridge for those who need cash in a hurry without the fear of further damaging their standing. It connects users with a variety of top personal loan lenders in just a few minutes. This efficiency is a lifesaver when an unexpected car repair or medical bill arrives unannounced, and you cannot afford to wait for a bank’s three-day review process.
The platform is designed for speed, allowing users to fill out a simple form that takes less than two minutes. This streamlined approach minimizes the “application fatigue” that often plagues those in financial crisis. Once approved, funds can be deposited into a bank account in as little as 24 hours. This is particularly beneficial for time-sensitive situations, such as avoiding a utility shut-off or paying a deductible to get back on the road.
Because JetzLoan functions as a marketplace, they do a significant amount of the heavy lifting for you. Instead of you spending hours applying to five different lenders only to be rejected by four of them, JetzLoan matches your profile with the lenders most likely to say yes. This maximizes your chances of success while minimizing the risk of credit score erosion.
Pros:
- Funds can arrive in as little as 24 hours.
- No hard credit pull during the initial rate check.
- High maximum loan amount of up to $50,000.
Cons:
- Limited to connecting with other lenders rather than being the sole source.
2. LendingPoint
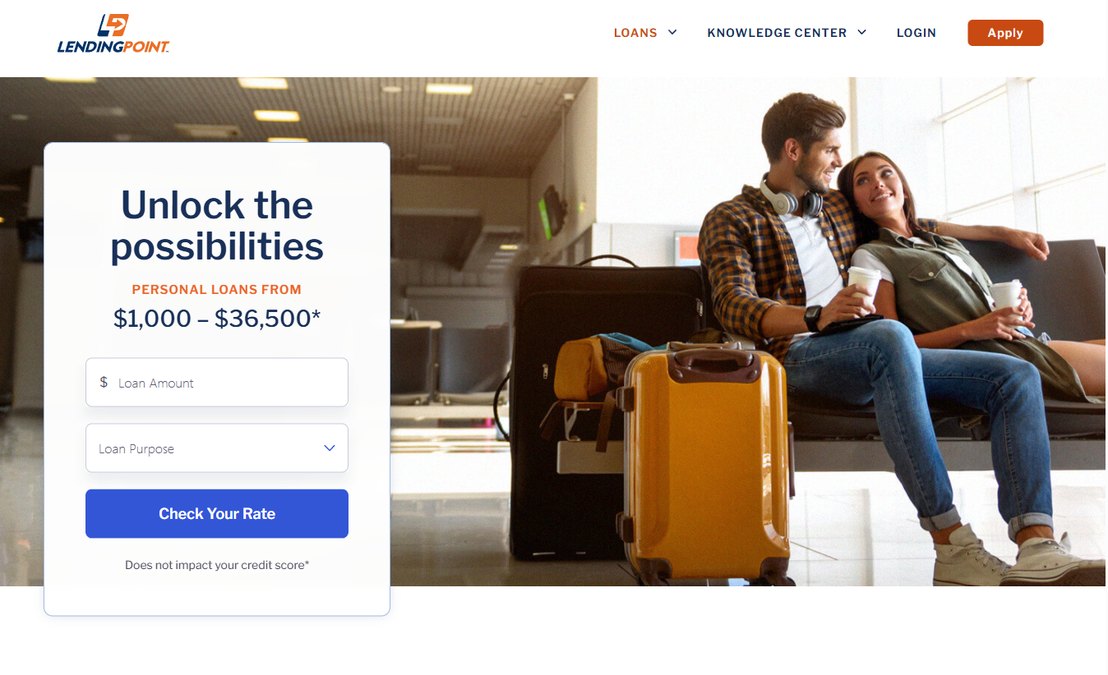
LendingPoint is a solid option for those looking to clean up their financial slate through debt consolidation. They offer personal loans ranging from $1,000 up to $36,500. This makes it a viable tool for someone trying to roll several high-interest credit card balances into one manageable payment. For example, if you are carrying three different cards with 29% APR, consolidating them into a single personal loan with a lower fixed rate can drastically reduce your monthly interest expense.
The platform is quite transparent about its purpose, catering to various needs like medical expenses, wedding costs, or travel. However, their real strength lies in their ability to look at the “whole picture” of a borrower. While a traditional bank might see a single late payment and automatically decline you, LendingPoint’s underwriting process is designed to consider the broader context of your financial stability.
They offer a way to check rates without impacting a credit score, which is a vital safety net for someone trying to stay afloat. This “pre-qualification” phase allows you to see your potential monthly payment and APR before you ever commit to a formal application, providing a level of certainty that is rare in the subprime lending space.
Pros:
- Wide range of loan purposes from weddings to taxes.
- Check rates without impacting credit score.
- Solid loan amounts for mid-sized financial goals.
Cons:
- Specific approval criteria may still vary based on individual profile.
3. MoneyLion
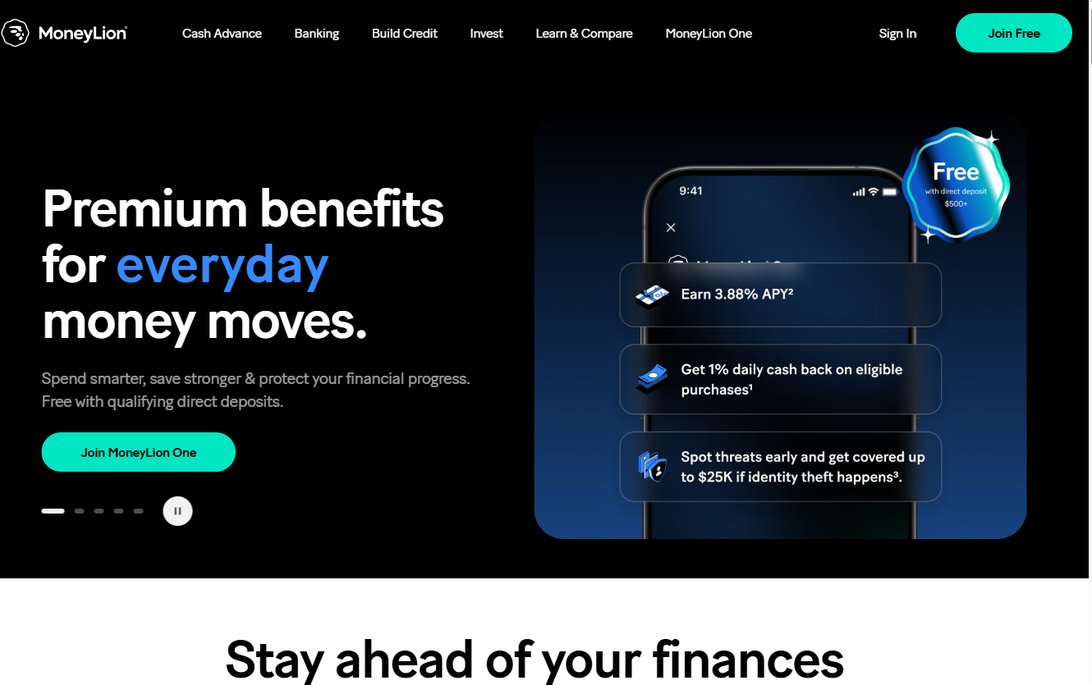
MoneyLion is more than just a lender; it is a comprehensive financial toolkit for those looking to climb out of a hole. They offer a massive range of products, including cash advances and the ability to borrow up to $100,000 for major life changes like going back to school or consolidating high-interest debt. This makes them a versatile partner for various stages of a financial recovery journey.
One of the most attractive features is the Credit Builder Plus option. Instead of just providing a temporary bandage, they offer tools to help improve a credit score over time. This is essential for anyone who wants to move from “bad credit” to “excellent credit” in the long run. By reporting your payments to the major credit bureaus, MoneyLion helps create a positive paper trail that can eventually lead to lower interest rates from mainstream lenders.
The app-based interface is highly intuitive, allowing you to monitor your spending, track your credit score, and manage your loans all in one place. This centralization of financial data is a significant psychological advantage for those who previously felt overwhelmed by disparate bills and accounts.
Pros:
- Extremely high borrowing ceiling of up to $100,000.
- Features tools specifically designed to build credit.
- Offers cash advances for immediate liquidity.
Cons:
- Expedited delivery of cash may require an additional Turbo Fee.
4. Check City
When the situation is dire and the need is immediate, Check City provides quick cash options like payday loans. These are designed to be fast-funding options that are typically due on the borrower’s next payday. This is a high-speed solution for very short-term gaps, such as a sudden car repair needed to get to work or an urgent grocery bill. However, it is vital to use these with extreme caution.
They also offer installment loans, which might be a slightly more manageable alternative to payday loans. These break payments into smaller chunks, making them a bit easier to digest than a single lump-sum repayment. For instance, instead of owing $500 all at once in two weeks, an installment loan might allow you to pay back $75 over several months. While the total interest paid might be higher, it reduces the immediate risk of a total budget collapse.
Pros:
- Offers multiple types of loans including installment options.
- Designed for quick cash needs and immediate liquidity.
- Accessible through various online application methods.
Cons:
- Payday loans can be expensive and carry high risks if not managed carefully.
5. Acorn Finance
Acorn Finance specializes in a very specific niche: home improvement financing. If you are looking to remodel a kitchen or install a new pool, this service connects you with personalized rates. This is a vital service because home improvements are often viewed as investments rather than expenses, and having the right financing can increase your home’s equity while you pay off the loan.
The platform is highly rated by users for its ease of use, particularly for those working with contractors. One of the major hurdles in home renovation is the “middleman” problem. Contractors often have their own financing options that may not be the most competitive. Acorn Finance allows you to shop around for the best rate independently of your contractor, giving you more leverage in negotiations.
There are no dealer fees involved, which helps keep the cost of home renovations from spiraling out of control. This is a significant advantage over some traditional home equity lines of credit (HELOCs) or contractor-offered financing, which may include hidden administrative costs or high origination fees. It is a specialized tool for a specific type of borrower who is looking to add value to their primary asset.
Pros:
- Tailored specifically for home improvement and contractor financing.
- No dealer fees for the borrower.
- Personalized rates with no credit score impact during checking.
Cons:
- Limited to home improvement use cases rather than general personal needs.
Comparing Loan Types: Short-Term vs. Long-Term Solutions
Understanding the difference between the products listed above is critical for your long-term success. Not all debt is created equal, and choosing the wrong tool for your specific problem can exacerbate your financial issues.
| Feature | Short-Term (Payday/Cash Advance) | Long-Term (Personal/Consolidation Loans) |
|---|---|---|
| Primary Goal | Immediate liquidity for emergencies | Debt restructuring or major purchases |
| Interest Rates | Typically very high | Moderate to high, but structured |
| Repayment Period | Days to weeks | Months to years |
| Credit Impact | Minimal (unless missed) | Can build credit through consistent payment |
If you are facing a “fire”—an immediate crisis that requires cash in the next 48 hours—a short-term solution like Check City or a MoneyLion cash advance is appropriate. However, if you are trying to solve a systemic problem, like a mountain of credit card debt, you should ignore the quick-cash options and focus on a long-term structural tool like LendingPoint or MoneyLion’s credit-building products.
Common Pitfalls and How to Avoid Them
Even with the right lender, the way you approach the loan can determine whether it helps or hurts you. Below are the three most common mistakes made by borrowers with struggling credit.
1. The “Multiple Inquiry” Trap: When you are desperate, it is tempting to apply to every lender you find on a Google search. Every time you submit a formal application, the lender performs a “hard pull” on your credit. Multiple hard pulls in a short window can cause your credit score to drop significantly, making you even less likely to get approved by better lenders in the future. Use marketplaces or “no impact check” services to shop for rates first.
2. Ignoring the APR in Favor of the Monthly Payment: Borrowers often focus solely on the monthly payment because it fits their current budget. However, a low monthly payment often comes with an incredibly long term. While this makes the monthly bill easy to pay, you might end up paying double or triple the actual cost of the loan in interest. Always look at the Total Cost of Loan to see the real price of the money you are borrowing.
3. Using Debt to Fund Lifestyle Expenses: This is the most dangerous trap. Using a personal loan to cover a gap in your budget is a strategic move; using a personal loan to fund a vacation or a shopping spree is a recipe for a debt spiral. If the loan does not directly lead to a more stable financial position, like paying off high-interest debt or fixing a car needed for work, it is likely contributing to your downward trend.
Choosing the right lender is like choosing a vehicle for a long journey; you need to know if you need a sprint or a marathon runner. If you need to fix a leaky roof tomorrow, a quick cash advance might be the only way to stop the damage. However, if you are trying to fix your life, a credit-building tool is a much better long-term companion.
A common mistake is rushing into the first offer that comes along without checking the fine print. Always ask if a credit check will be “hard” or “soft.” A soft check is like a handshake; it doesn’t change your score. A hard check is like a formal interrogation; it leaves a mark on your record. For those with bad credit, every single point counts.
Another pitfall is ignoring the total cost of borrowing. A loan might look small, but if the repayment terms are too aggressive, it could lead to a cycle of debt. Always ensure the monthly payment fits comfortably into your existing budget without requiring you to skip meals or rent. Financial stability is the ultimate goal, not just a quick infusion of cash.