
Top 7 Lenders for a 620 Credit Score Personal Loan in 2026
Last updated: 2026-11-01
Trying to manage your finances with a 620 credit score can feel like driving through a thick fog. You know the shore is out there somewhere, but the interest rates and approval odds remain frustratingly blurry. Many people find themselves stuck in this middle ground. You are not quite “prime,” but you aren’t completely out of options either.
This “fair” credit tier is a tricky pivot point. It is high enough to get you in the door with specialized lenders, but low enough that one small slip-up during the application can lead to a rejection. You might even end up with an interest rate that feels predatory. It is a high-stakes zone where every move counts.
Finding the right lender requires looking past those flashy, polished advertisements. It is about matching your specific debt needs with a provider that actually understands your profile. Whether you are trying to consolidate high-interest cards to free up monthly cash flow or tackling a sudden medical bill, the right partner changes everything. A strategic loan should be a tool for progress, not a temporary bandage that leads to a cycle of high interest.
- OneMain Financial
- JetzLoan
- Max Cash
- Avant
- Upgrade
- LendingPoint
- United Finance
How These Lenders Were Evaluated for 620 Credit Scores
The selection process focused on how easy it is to get started and how transparent the terms are. Since a 620 score sits in a sensitive zone, we prioritized the ability to check rates without a hard credit pull. Lenders that offer a “soft” inquiry allow you to shop around without damaging your precious score any further.
We looked closely at how these lenders transition from a soft inquiry to a hard pull. You do not want to be blindsided by a sudden drop in your credit score while you are still just comparing options. We wanted to ensure that the comparison phase doesn’t cost you money before you’ve even signed anything.
Speed of funding and total loan amounts were also heavy factors. A lender that takes a full week to move money is useless during a genuine emergency. We examined the “time-to-cash” metric across various scenarios, from simple personal loans to more complex installment structures. We wanted a diverse list that caters to both the person in an emergency and the long-term planner.
| Lender Name | Loan Amount Range | Funding Speed | Credit Impact Check |
|---|---|---|---|
| OneMain Financial | $1,500 – $35,000 | As soon as 1 hour | No impact |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No impact |
| Max Cash | $250 – $10,000+ | In minutes | See site |
| Avant | See site | See site | See site |
| Upgrade | Up to $50,000 | Fast funding | No impact |
| LendingPoint | $1,000 – $36,500 | See site | No impact |
| United Finance | Up to $20,000 | See site | See site |
1. OneMain Financial
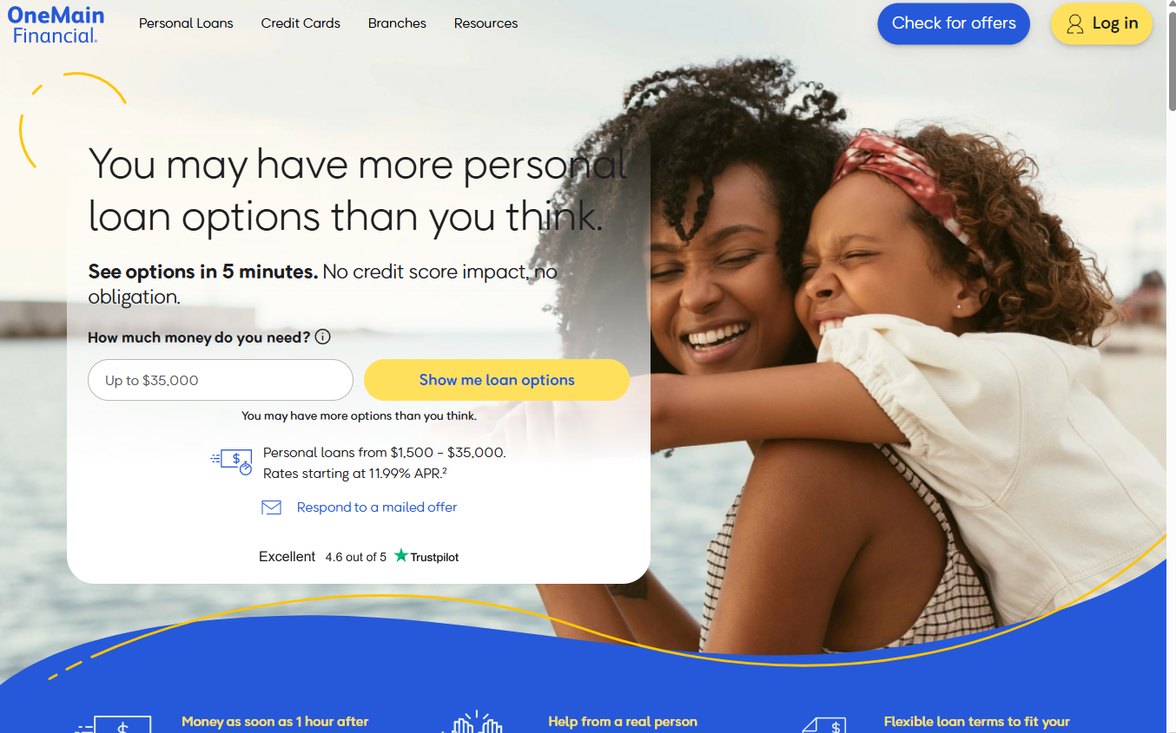
OneMain Financial is a powerhouse for those who prefer a human touch. With over 1,300 physical branches, they offer a level of accessibility that purely digital lenders simply cannot match. It is a solid choice if you want to sit down with a real person to discuss your financial roadmap. This is especially helpful if your credit history is complex and requires a nuanced explanation that an automated algorithm might miss.
Their products range from $1,500 up to $35,000, making them versatile for various needs. If you are in a pinch, they can move incredibly fast. Money can potentially arrive just one hour after you sign the paperwork. This speed is a lifesaver during urgent household repairs or sudden emergencies. However, keep in mind that the “in-person” aspect often means more rigorous documentation requirements. You should be prepared to bring proof of income and residency to your local branch.
Pros:
- Extensive branch network for in-person support
- Extremely fast funding options
- Flexible terms from 24 to 60 months
Cons:
- Requires visiting a branch for some levels of service
- Interest rates vary significantly based on profile
2. JetzLoan
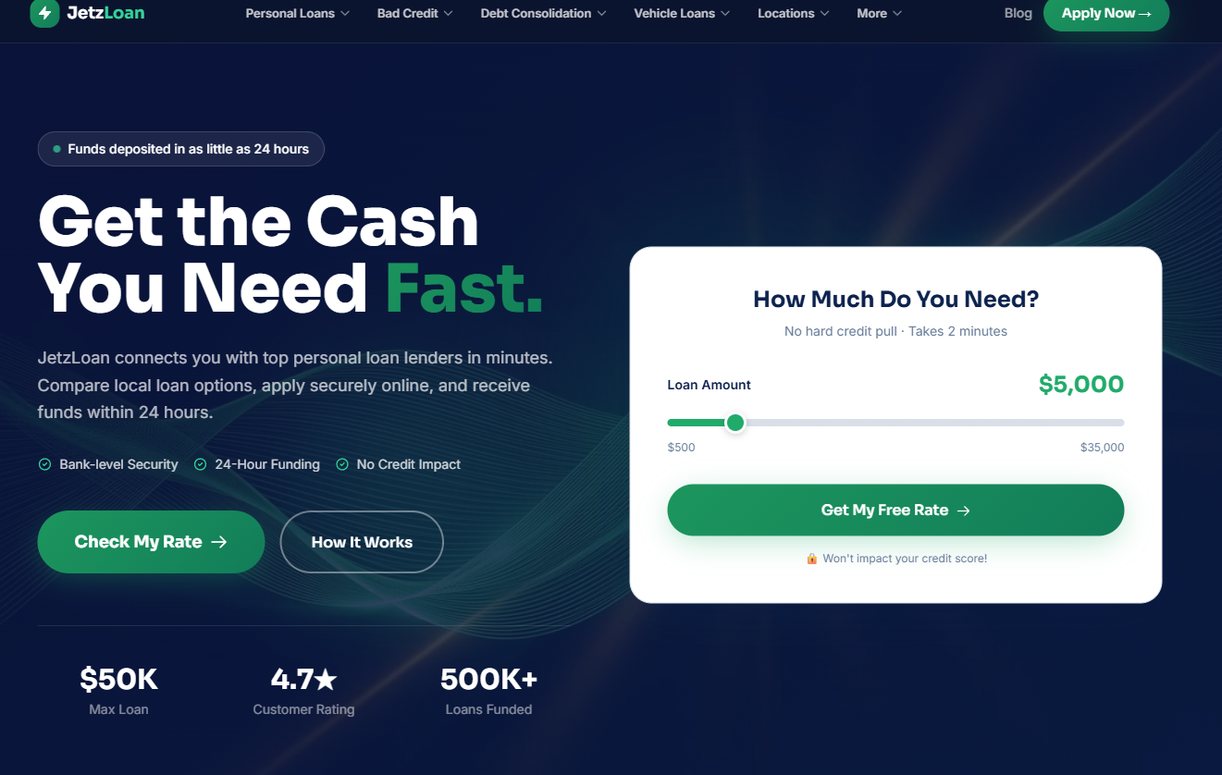
JetzLoan operates like a high-speed bridge between borrowers and top lenders. Their platform is built for speed, connecting you with options in just a few minutes. It is particularly useful for those who want to scan the horizon without the fear of a credit score dip. Rather than being a single lender, they act as a sophisticated matchmaker. They filter your 620 score against a network of providers to find the best fit. (jetzloan.com)
With a maximum loan amount of $50,000 and a focus on 24-hour funding, they cater to the “need it now” crowd. Their process is streamlined, requiring less than two minutes to complete the initial application form. This makes them an ideal starting point for borrowers who are unsure which direction to take. You can know your options before the end of the business day.
Pros:
- Fast 24-hour funding capability
- No hard credit pull for rate checks
- High customer rating of 4.7 stars
Cons:
- Connects you to other lenders rather than being the sole lender
- Minimum loan amounts can be quite low
3. Max Cash
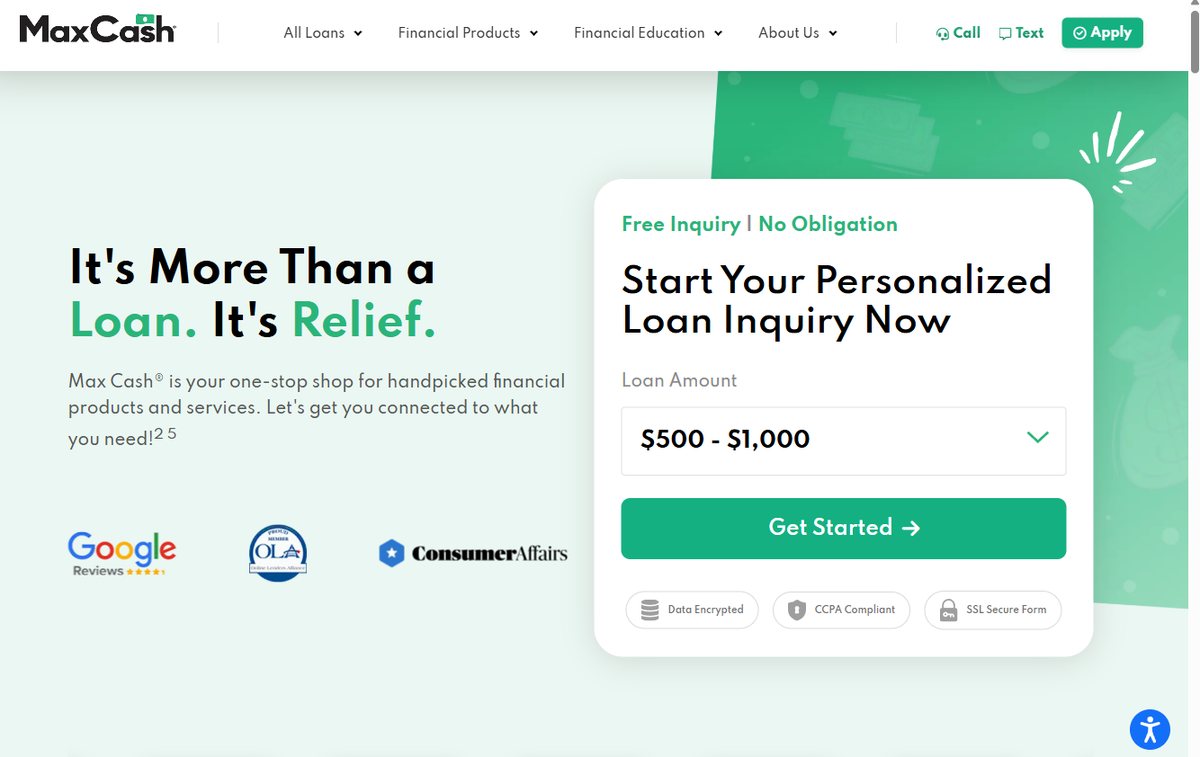
Max Cash is a versatile player that covers a massive spectrum of loan sizes. From a tiny $250 cash advance to large loans exceeding $10,000, they have a product for almost every scenario. This makes them a “one-stop shop” for various financial relief needs. You can find everything from minor unexpected costs to larger capital injections here.
They offer more than just simple personal loans; you can find installment loans and title loans as well. It is important to note that title loans require using your vehicle as collateral. This carries much higher risk than a standard unsecured personal loan. If you are looking for immediate relief through different financial products, Max Cash provides a wide array of options. Just be sure to read the fine print on collateral-based products.
Pros:
- Extremely wide range of loan amounts
- Offers multiple types of financial products
- Fast inquiry process
Cons:
- Product variety can be overwhelming
- Title loans involve higher risks for collateral
4. Avant
Avant focuses heavily on helping people move their financial lives forward. They offer specialized solutions for debt consolidation, home improvement, and emergency expenses. Their approach is geared toward providing clarity. They want to give you the tools to manage your journey step by step. This makes them a favorite for those looking to consolidate multiple high-interest debts into a single, more manageable monthly payment.
The company offers both personal loans and credit cards. This gives you options to choose how you want to manage your money. They emphasize flexible choices and friendly support, which makes them a strong contender for those looking to reorganize their existing debt. Their digital platform is highly intuitive. It is easy to track your repayment progress and see how your score might improve as you pay down your balance.
Pros:
- Specialized loan purposes like debt consolidation
- Offers both loans and credit cards
- User-friendly digital experience
Cons:
- Approval criteria can be specific
- Less focus on very small, micro-loans
5. Upgrade
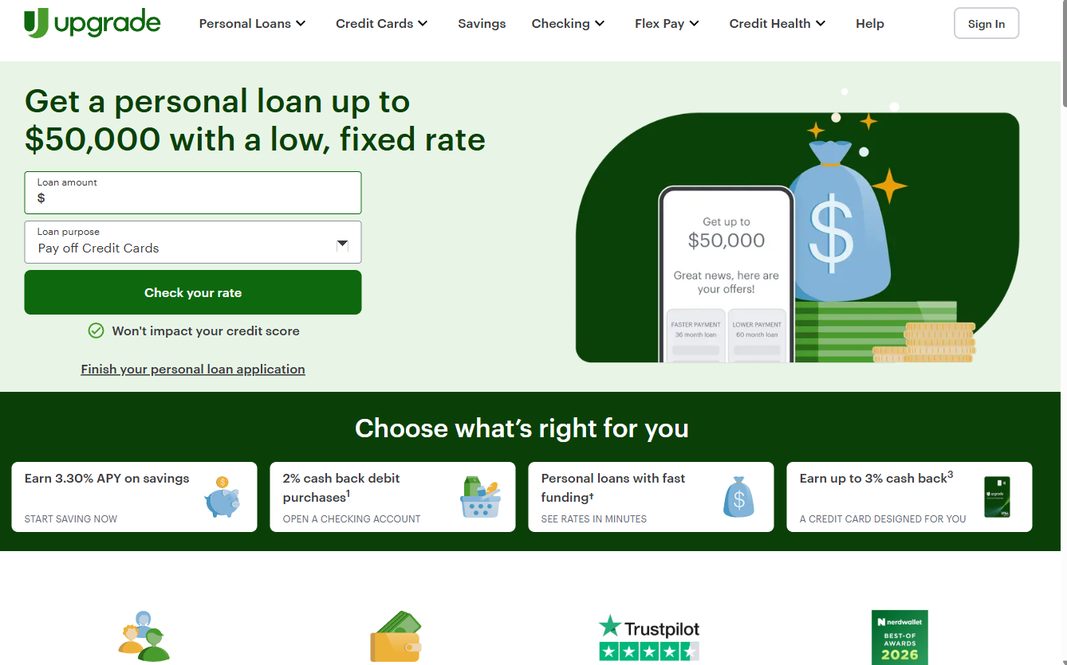
Upgrade is a sophisticated option for those looking to integrate their finances. They offer personal loans up to $50,000 and even provide high-yield savings and checking accounts. It is a comprehensive ecosystem designed to help you build wealth while managing debt. For a borrower with a 620 score, using a platform that encourages both borrowing and saving can be a strategic way to balance your cash flow.
They provide a unique “check your rate” feature that won’t impact your credit score. This allows you to see if you qualify for their low, fixed rates before you commit to anything. It is a very low-pressure way to explore your options. The integration with their banking tools allows you to see exactly how a loan payment would impact your overall monthly budget before you ever sign a contract.
Pros:
- High maximum loan amounts up to $50,000
- Integrated banking and savings options
- No impact on credit score when checking rates
Cons:
- Complex product ecosystem can be distracting
- Requires specific financial management to maximize benefits
6. LendingPoint
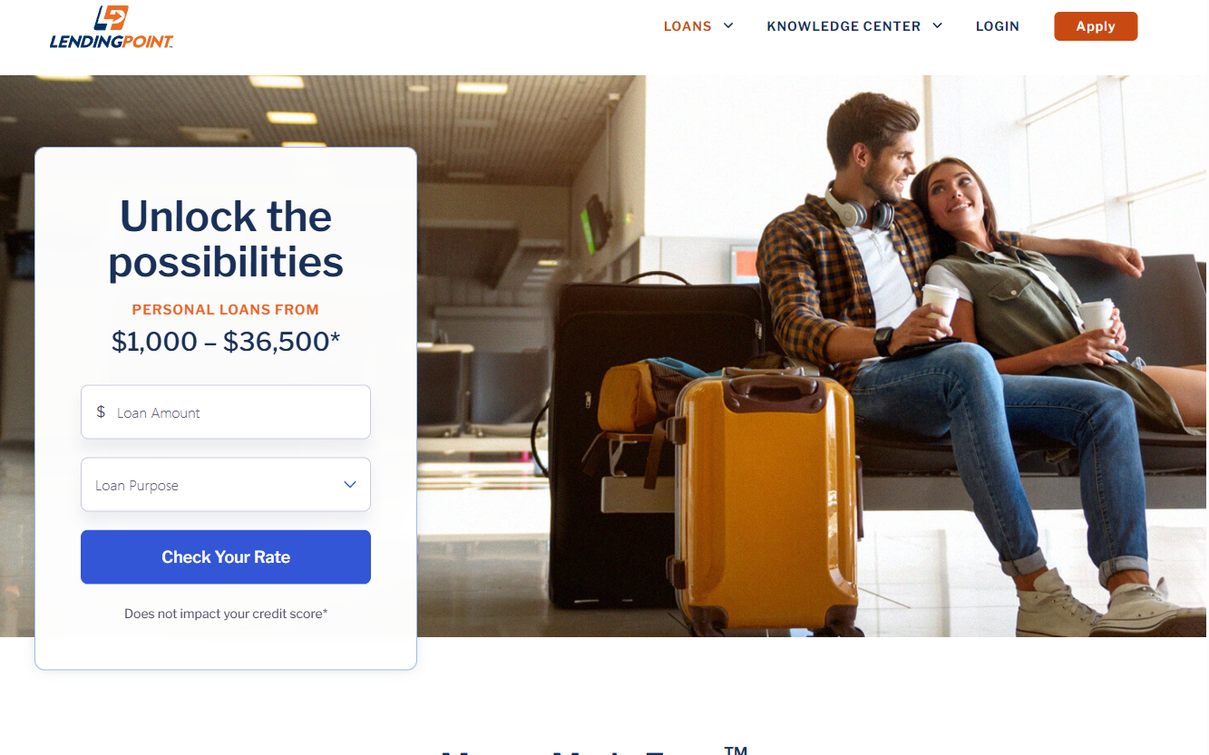
LendingPoint aims to unlock possibilities for those who might feel locked out by traditional banks. Their personal loans range from $1,000 to $36,500. They cover everything from medical bills to wedding expenses. They focus on making the money-making process as easy as possible. By using advanced technology to assess risk, they can often be more lenient with mid-tier credit scores than a major national bank.
One of their standout features is the “check your rate” tool, which does not impact your credit score. This is a vital feature for anyone with a 620 score who wants to protect their standing while shopping for the best terms. Because every inquiry counts toward your credit utilization and inquiry count, being able to “window shop” without consequence is a major advantage.
Pros:
- No impact on credit score for checking rates
- Wide variety of loan purposes
- Significant loan amounts for mid-range credit
Cons:
- Strict verification processes for identity
- May require more documentation than others
7. United Finance
United Finance is a seasoned veteran in the lending world, having been around since 1922. They offer a sense of stability and tradition that many borrowers find comforting. They specialize in personal and auto loans that are designed to fit into a household budget. For those who are wary of “fintech” startups that might disappear, United Finance offers the peace of mind that comes with nearly a century of operation.
Beyond simple personal loans, they offer high-yield certificates for Oregon residents and various auto financing options. If you need a lender with a long history of trust and dedicated, friendly lenders who can walk you through the nuances of interest accrual and amortization schedules, United Finance is a reliable choice. Their longevity shows they can handle various economic cycles successfully.
Pros:
- Decades of established industry experience
- Dedicated and friendly lender support
- Diverse options including auto loans
Cons:
- More localized/specific offerings
- May lack the high-tech speed of digital-only lenders
Strategic Steps to Maximize Your 620 Score During the Process
Before you begin your application journey, you can take small, actionable steps to move your score closer to the “Prime” category. This could save you thousands in interest. Even a 10-point bump can change your eligibility for certain loan products. Small changes often lead to big savings.
First, address your credit utilization immediately. If your credit cards are near their limits, your score is being suppressed. Paying down even a small portion of your balance before applying can signal to lenders that you are managing your debt effectively. Second, ensure there are no errors on your credit report. A single incorrect “late payment” mark from two years ago can keep you stuck in the 620 range. Use a free reporting service to scan for inaccuracies and dispute them before you start your loan search.
Third, consider the timing of your applications. Avoid applying for multiple types of credit, like a new credit card and a personal loan, in the same week. Spacing out your inquiries helps prevent the appearance of “credit seeking behavior,” which is a red flag for lenders. Finally, gather your documents ahead of time—pay stubs, W-2s, and bank statements. Having these ready speeds up the verification process and prevents your application from stalling in the “pending” phase.
How to Navigate Your Loan Search Without Mistakes
Before signing any paperwork, always look at the total cost of the loan, not just the monthly payment. A lower monthly payment often means a longer term, which results in paying much more in interest over the life of the loan. For example, a $5,000 loan with a 36-month term at 15% interest will cost significantly less in total interest than the same loan with a 60-month term at 18%, even if the 60-month monthly payment looks much more attractive to your current budget.
Another mistake to avoid is applying for multiple loans simultaneously with hard credit pulls. This can make your 620 score look much worse than it actually is. Each hard inquiry can shave points off your score. Several in a short window can make you look like a high-risk borrower in desperate need of cash. Always use the “no impact” check features offered by companies like JetzLoan or Upgrade to find your best match first.
Finally, consider a cosigner if you find that rates are too high for your current profile. Adding a person with a higher credit score can act as a safety net for the lender, often resulting in lower interest rates for you. This is a significant responsibility for the cosigner, as they become legally liable for the debt if you fail to pay. It is a powerful tool to turn a “maybe” into a “yes,” but it must be approached with extreme caution and clear communication between both parties.