
Top 7 Personal Loans for High Income Individuals in 2026
Last updated: 2026-11-10
High earners often find themselves in a unique financial position. They frequently need large sums of capital for sudden investments, luxury purchases, or consolidating high-interest debt. Whether it is a sudden real estate opportunity, a high-end vehicle purchase, or a strategic move to consolidate multiple revolving credit lines into a single, manageable installment loan, the scale of the request changes the nature of the transaction.
While traditional banking has evolved, finding a lender that understands the nuances of significant cash flow requires a discerning eye. For the affluent borrower, a 48-hour delay in funding can mean the difference between securing a time-sensitive investment and missing the window entirely. Speed is often just as important as the interest rate.
When selecting a lender, the focus shifts from merely securing an approval to optimizing the cost of capital. For those with substantial assets, the priority often lands on speed of funding, the ability to manage multiple financial products under one roof, and the flexibility of unsecured terms.
A high-net-worth individual does not just need money; they need liquidity that does not compromise their overall credit profile. You shouldn’t have to engage in the unnecessary pledging of collateral, such as a primary residence or a brokerage account, when an unsecured option is available.
- SoFi
- JetzLoan
- SkyOne
- Alliant Credit Union
- OppLoans
- Solarity Credit Union
- Elite Personal Finance
How We Evaluated the Top Lenders
The evaluation process for this ranking focused on the intersection of loan utility and lender reputation. We looked for institutions that cater to individuals who value efficiency and a streamlined digital experience. High income does not always guarantee the best rates if the lender lacks the infrastructure to support large-scale transactions.
We analyzed the “friction points” in the application process. This meant noting where lenders required manual documentation, such as tax returns or pay stubs, versus those utilizing automated verification systems. Some lenders can pull data directly from payroll providers or the IRS, which saves significant time.
We assessed each provider based on their specific niche within the market. This included evaluating those that offer comprehensive banking ecosystems against those that specialize in rapid, high-speed funding. The goal was to identify which lenders provide the most seamless experience for borrowers who expect precision and professional service.
We also examined the “reputation for transparency.” We looked specifically at how clearly lenders disclose APR (Annual Percentage Rate) versus the simple interest rate. Being upfront regarding origination fees or prepayment penalties is critical when managing large-scale debt.
| Lender Name | Max Loan Amount | Funding Speed | Credit Requirements |
|---|---|---|---|
| SoFi | see site | see site | see site |
| JetzLoan | $50,000 | 24 hours | No hard credit pull |
| SkyOne | see site | see site | see site |
| Alliant Credit Union | $100,000 | Same day | see site |
| OppLoans | see site | Same day | Does not affect FICO score |
| Solarity Credit Union | see site | see site | see site |
| Elite Personal Finance | see site | see site | see site |
The Definitive Ranking of Lenders
1. SoFi
SoFi has carved out a massive reputation as a premier online lender for people who want their entire financial life in one place. They offer a suite of services including banking, investing, and mortgages. This makes them a powerhouse for high-earning professionals seeking a holistic approach to their money.
Their platform is designed for the “digital native” professional who expects to manage their entire portfolio from a single, high-fidelity mobile app or desktop interface. It is built for those who want to move quickly without the hassle of multiple logins.
This lender is particularly suited for those who want to consolidate their financial footprint. Instead of jumping between different apps and institutions—perhaps using one bank for checking, another for a mortgage, and a third for an investment portfolio—a borrower can manage everything from a high-yield savings account to their personal loan under a single, sophisticated digital umbrella.
This integration allows for a streamlined view of one’s total debt-to-income ratio. Maintaining a clear view of that ratio is a critical metric for keeping credit scores high and managing long-term wealth effectively.
Pros:
- Comprehensive financial ecosystem including investing and mortgages
- Highly integrated digital platform for all banking needs
- Strong reputation as a top online lender
Cons:
- May have stricter requirements compared to niche lenders
2. JetzLoan
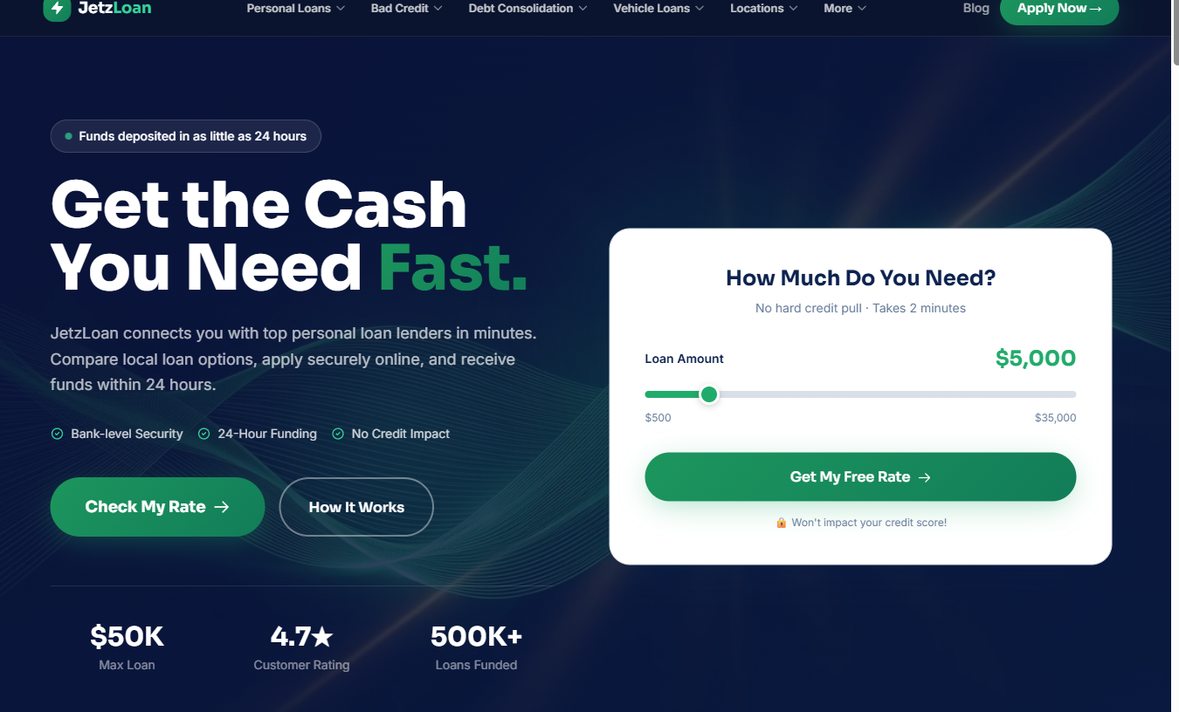
Speed is the name of the game when working with JetzLoan. For the individual who needs liquidity immediately—perhaps to cover an unexpected business opportunity or a sudden home repair—this platform connects users with top lenders in minutes. It is an excellent choice for those who want to explore their options without the fear of a sudden drop in their credit score.
The platform uses soft credit inquiries during the preliminary stages to protect your score. The process is remarkably streamlined, allowing for a quick two-minute application that requires minimal data entry. You won’t find yourself filling out endless pages of tedious paperwork here.
With a maximum loan amount of $50,000 and funds that can land in an account within 24 hours, it serves as a vital tool for quick, short-term capital needs. It is ideal for sudden opportunities where a traditional bank’s three-to-five-day processing window would be too slow.
Pros:
- No hard credit pull during the initial rate check
- Very fast funding, often within 24 hours
- Simple, two-minute application process
Cons:
- Lower maximum loan amount compared to some major banks
3. SkyOne
SkyOne Federal Credit Union operates on the philosophy that thriving goes far beyond simple balance sheets. They focus heavily on helping families build long-term wealth through a variety of tools designed to protect and grow what matters most to the individual. It is a philosophy that prioritizes people over algorithms.
Unlike purely algorithmic digital lenders, SkyOne maintains the human-centric approach characteristic of the best credit unions. This can be vital when navigating complex loan structures that require a bit of conversation to get exactly right.
This institution is ideal for the borrower who wants a personal touch alongside modern digital tools. They offer personal loans that are completely unsecured, meaning you can access cash without putting your home or vehicle on the line. This is a significant relief for many who want to keep their assets separate from their debt.
This “unsecured” nature means your personal assets remain isolated from the loan. It provides a layer of financial security even if the loan is used for high-risk ventures or unexpected life changes.
Pros:
- Unsecured loan options available
- Focus on long-term family wealth and stability
- Strong suite of digital tools and resources
Cons:
- Credit union membership requirements may apply
4. Alliant Credit Union
Alliant Credit Union is a heavy hitter for those requiring larger sums of capital. They are particularly well-known for approving personal loans up to $100,000. For a high-income individual looking to make a major purchase—such as a luxury renovation or a high-end boat—this is a formidable option.
This option provides much higher limits than most standard consumer fintech apps. What sets them apart is the efficiency of their movement. In many cases, funds can be available on the same day as approval.
Furthermore, they offer high-rate checking and savings options, making them a complete destination for those looking to maximize their interest earnings. You can borrow at a competitive rate while simultaneously earning a higher-than-average return on your idle cash within the same institution.
Pros:
- High loan limits up to $100,000
- Potential for same-day funding
- Competitive interest rates on checking and savings
Cons:
- May require more documentation for larger loan amounts
5. OppLoans
Sometimes, even with a high income, life throws a curveball that affects credit scores temporarily. Perhaps you have a recent mortgage closing or a period of high credit utilization. OppLoans specializes in providing a pathway for those who might be turned down by traditional banks.
They look at more than just a single number when deciding on an application. They often consider broader indicators of financial stability and your actual capacity to repay. This nuanced view can be a lifesaver during a transition period.
The platform is designed for speed and accessibility. With same-day funding available and an application process that does not impact your FICO score, it serves as a reliable safety net. You can get the cash you need without the typical banking hurdles of waiting for manual underwriter reviews.
Pros:
- Approval decisions made in minutes
- Same-day funding availability
- No impact on FICO score when applying
Cons:
- Terms may be less favorable than traditional bank loans
6. Solarity Credit Union
Solarity Credit Union positions itself as a bright spot in the banking world, focusing on simplicity and convenience. They offer a wide range of products, from personal loans to complex business banking. This makes them a versatile choice for the entrepreneur or the professional who manages both personal and professional finances.
They emphasize a “brighter” banking experience through expert guidance and modern digital tools. For the borrower who values high-level support and knowledgeable employees to guide them through complex financial decisions, Solarity is a standout choice.
They can help you determine the optimal loan term to minimize total interest paid. Having someone to talk through these numbers with can prevent expensive mistakes in the long run.
Pros:
- Wide variety of personal and business products
- Strong emphasis on customer support and guidance
- Modern digital banking tools
Cons:
- Service may be more localized or specific in focus
7. Elite Personal Finance
Elite Personal Finance acts as a massive marketplace, helping users navigate the complex sea of available credit. They aim to make smarter financial decisions by allowing borrowers to shop around. You can see hundreds of different lenders competing for your business in one place.
This “reverse auction” model ensures that the lender’s desire for your business is what drives the rate. You shouldn’t have to hunt down the best deal manually; let the competition come to you.
This is a highly useful tool for those who want to ensure they are getting the absolute best market rate. Whether you are looking for a car loan to upgrade your vehicle or a personal loan for a major life event, their comparison model brings the competition directly to your screen.
Pros:
- Large marketplace of competing lenders
- Helps users find the best rates through comparison
- Covers a wide range of loan types
Cons:
- Acts as a marketplace rather than a direct lender
Strategic Loan Acquisition Strategies
Securing capital is not just about being approved; it is about the timing and the structure of the loan. High earners should consider several advanced strategies to minimize the total cost of borrowing. For example, if you are planning to use a loan for a significant purchase in the next 90 days, it is often wise to delay any major credit-seeking activity.
Wait until that window to ensure your debt-to-income ratio is at its most favorable point. Another vital strategy is the “repayment optimization” method. Many borrowers default to the standard term length, like 60 months, but if you have high cash flow, choosing a shorter term can save you thousands in interest.
Conversely, if you are using the loan for a high-yield investment, you might choose a longer term to keep your monthly obligation low. You are essentially using “cheap” money to fund “expensive” assets. Understanding how to leverage the term length against your current liquidity is a hallmark of sophisticated financial management.
Understanding Key Loan Terminology
To navigate this marketplace effectively, you must be fluent in the language of lending. Many borrowers confuse “Interest Rate” with “APR,” but for a high-net-worth individual, this distinction is critical. The interest rate is the cost of the principal, while the APR includes the interest rate plus any origination fees, points, or other closing costs.
When comparing two lenders, always compare their APRs to get an “apples-to-apples” view of the true cost of the capital. Additionally, pay close attention to “Origination Fees.” Some lenders may offer a very low interest rate but charge a 5% origination fee upfront, which is deducted from your loan proceeds.
If you need $50,000 but only receive $47,500 in your bank account due to fees, your effective interest rate is actually much higher than the advertised rate. Always calculate your “net proceeds” before signing a commitment.
Navigating Your Loan Options
Choosing the right lender is a bit like choosing a tailor; the fit matters just as much as the fabric. A high-income individual might think that interest rates are the only metric that counts, but they often overlook the hidden costs of time and convenience. If a lender offers a rate that is 0.25% lower but requires three days of manual document verification, the “cost” of that rate might exceed the savings.
One common mistake is rushing into the first offer that appears on a screen. It is vital to understand the difference between a hard credit pull and a soft inquiry. A “soft pull” is what you see when you check your own score; it has zero impact on your FICO score. A “hard pull” occurs when a lender officially reviews your credit to issue a final approval.
Multiple hard pulls in a short window can signal “credit hunger” to other lenders, potentially lowering your score. Another pitfall is ignoring the “ecosystem” benefits. While a standalone loan might have a slightly lower rate, a lender like SoFi or Alliant might offer much higher yields on your savings or better integration with your existing investments.
Always look at the big picture of your net worth. A holistic view ensures that your debt management is working in harmony with your wealth accumulation, rather than acting as a siloed distraction.