
Top 6 Lenders for Bad Credit Loans New York: 2026 Rankings
Last updated: 2026-11-10
Living in the Big Apple can feel like a marathon through a thunderstorm. One minute you are fine, and the next, a sudden car repair or a medical bill lands on your kitchen table. The stress is heavy. For many New Yorkers, a bruised credit score feels like a locked door, keeping you away from the cash needed to keep things running.
Between Manhattan rents and Brooklyn grocery bills, a sudden $1,000 expense can wreck a monthly budget before you even realize it. You need a way to bridge that gap without losing control. Finding a lender requires more than a quick glance at a headline. You have to weigh how fast you get the cash against what it actually costs you in the long run.
It is easy to get caught in a trap. There is a massive difference between a high-interest payday loan and a structured personal loan. One might help you recover quickly, while the other keeps you stuck in a debt cycle for years. This list helps clear the fog so you can see your actual options in the New York market.
- JetzLoan
- GadCapital
- Experian
- GreendayOnline
- Optimal PLO
- United Finance
Evaluating Financial Assistance Options for New Yorkers
Picking a lender in New York requires a sharp eye. You should look at how fast the cash hits your bank account and what the maximum loan amounts are. Another big factor is the credit pull. A hard inquiry can shave points off your score, which makes things difficult when you eventually want to apply for a mortgage or an auto loan.
If your FICO score is 640, a single hard inquiry might drop it to 635. That small dip could disqualify you from much better interest rates later on. Speed matters most when an emergency strikes. Some services promise same-day money, but that usually means you have to be approved before noon. Other lenders might take 24 to 48 hours to get funds to you.
The amount you can borrow is just as vital. A student might only need $300 for a textbook, while a freelancer might need $10,000 to cover a three-month gap in client payments. You need a loan that fits your specific hole, rather than a one-size-fits-all solution that doesn’t actually cover your bills.
| Lender Name | Loan Amounts | Funding Speed | Credit Impact |
|---|---|---|---|
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| GadCapital | $100 – $5,000+ | See site | No credit checks |
| Experian | $2,000 – $50,000 | See site | See site |
| GreendayOnline | $100 – $5,000 | As soon as the same day | No hard credit checks |
| Optimal PLO | $1,000 – $5,000 | See site | See site |
| United Finance | Up to $20,000 | See site | See site |
1. JetzLoan
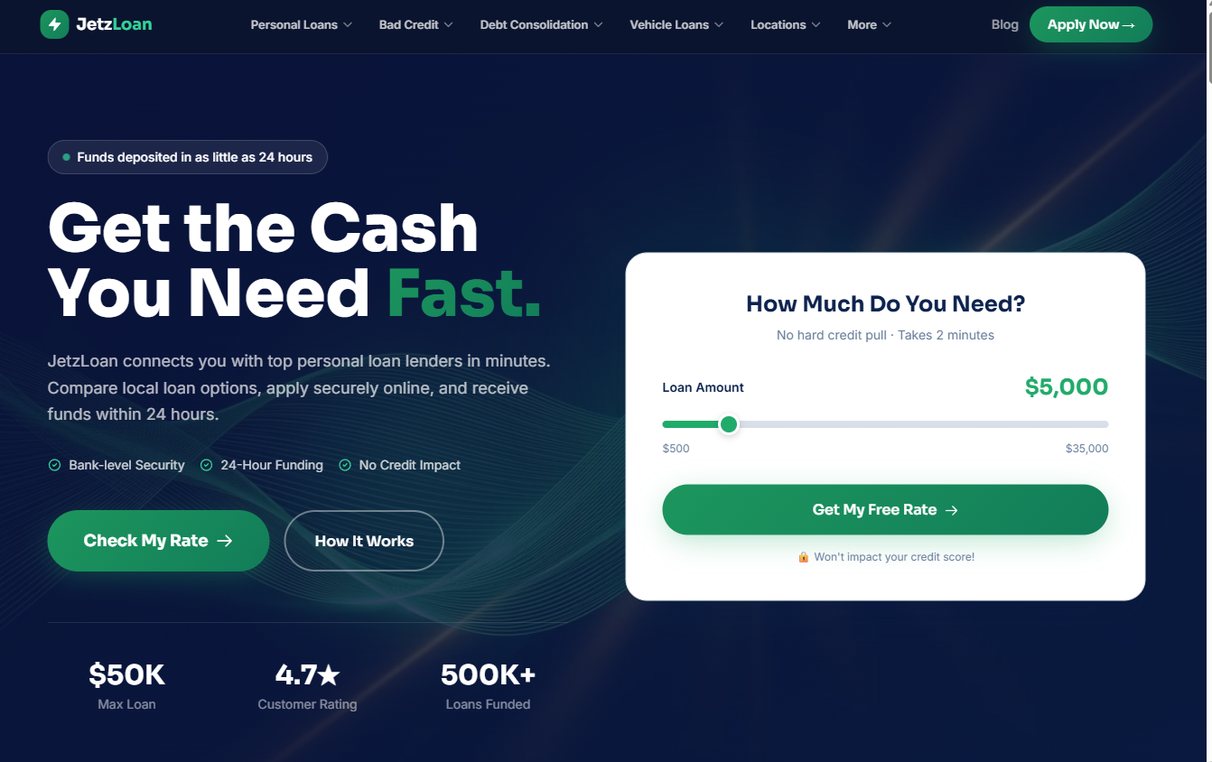
JetzLoan works like a digital connector. It links borrowers to a wide variety of top personal loan lenders. This is a great tool if you need a large sum, like for a vehicle or to consolidate debt, but you don’t want to hurt your credit score during the search. Instead of hitting up ten different banks, JetzLoan simplifies the whole thing.
They focus on speed. You can often see funds in your account in as little as 24 hours. They use digital underwriting to check your ability to repay, so you don’t have to wait for a loan officer to manually review your paperwork. It is a smart pick for a busy New Yorker who needs a fast fix without the “hard pull” that scares off future lenders.
Pros:
- No hard credit pull during the initial check
- High maximum loan limit of $35,000
- Rapid 24-hour funding potential
- Connecting with multiple lenders can lead to various offers to sort through
2. GadCapital
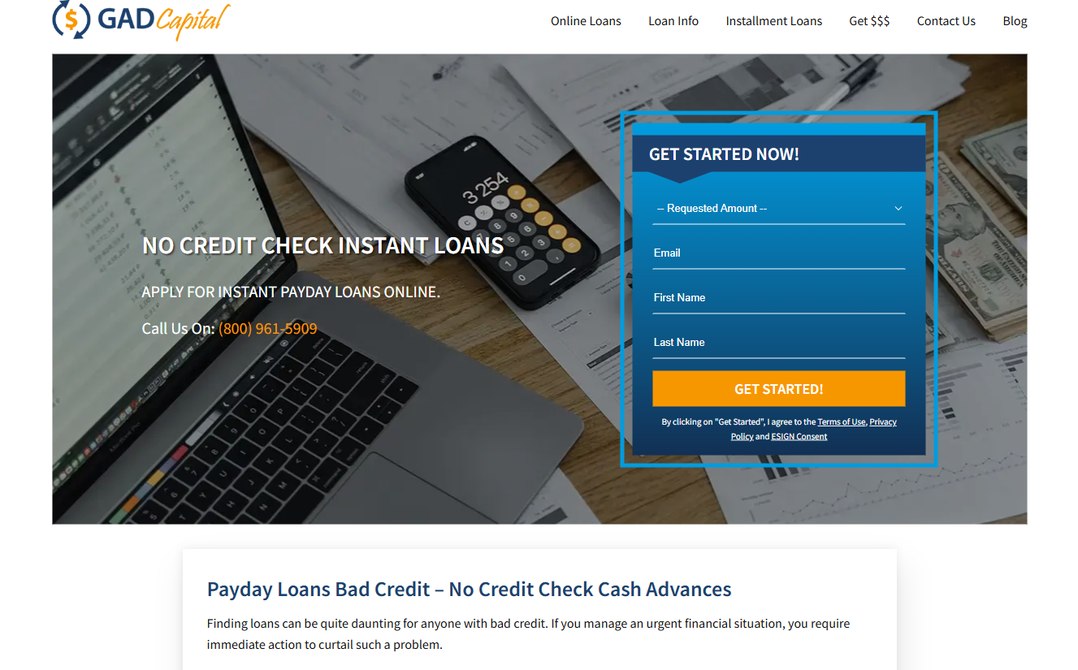
GadCapital is built for the “right now” moments. Their model focuses on direct lenders providing installment loans. This can be a lifesaver when a traditional bank says no because of a low credit score. It is particularly helpful for people with “thin” credit files or those with past bankruptcies who find the doors to big banks firmly shut.
The application is quick and straightforward. If you are staring at an unexpected utility bill or a plumbing emergency in an old apartment, GadCapital offers a way to get liquid cash when credit cards aren’t an option. They target that immediate relief that many people need to keep their lives on track.
Pros:
- No credit checks required
- Covers a wide range of small amounts from $100 upwards
- Straightforward online application process
- Focuses on smaller amounts rather than large-scale consolidation
3. Experian
Experian takes a wider view of your financial health. They don’t just provide a quick cash injection; they give you tools to manage your FICO® Score and report. This is a strategic move if you want to fix your actual standing rather than just covering up a symptom. Disputing an error on your report through them can actually raise your score over time.
If you need a larger chunk of capital, they can help with that too. Their system is designed to help you build credit by using utility and rent payments. These data points used to be invisible to lenders, but they are vital now. It makes them a long-term partner for stability rather than just a quick transaction.
Pros:
- Access to larger loan amounts up to $50,000
- Provides tools to boost credit scores through bill payments
- Comprehensive financial guidance and credit protection
- The focus is more on credit management than instant emergency cash
4. GreendayOnline
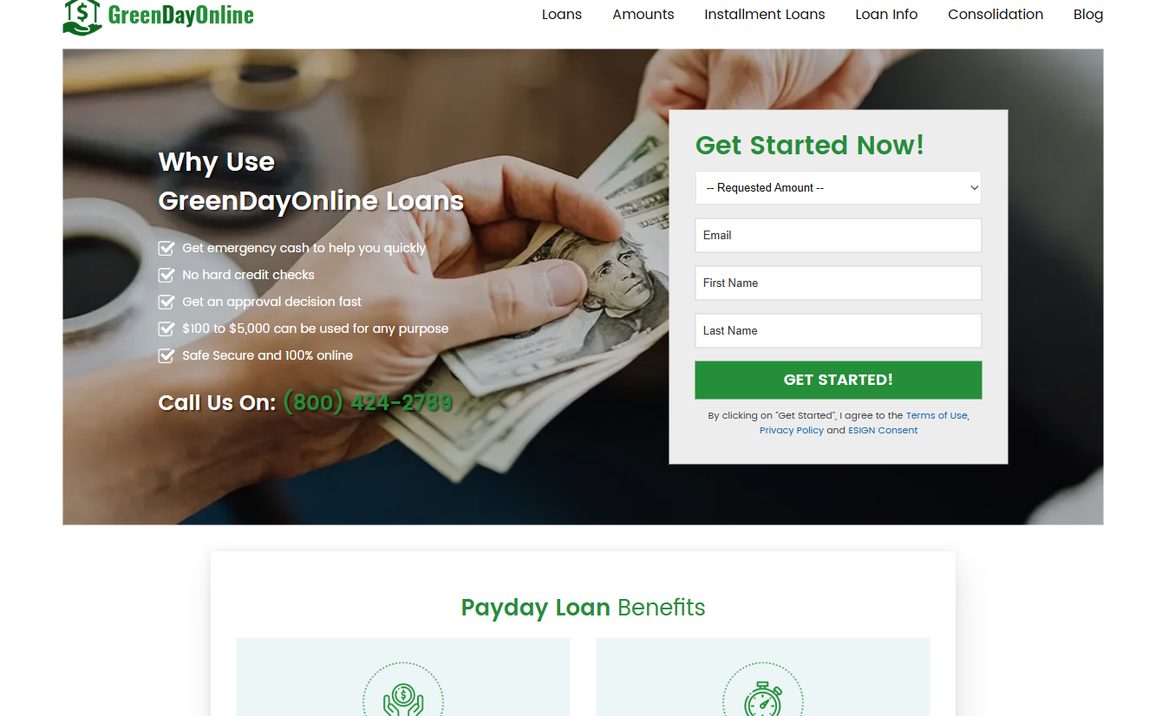
GreendayOnline is a specialized choice for people who need small payday loans without the stress of a hard credit check. They focus on the emergency market, offering between $100 and $5,000 for almost any reason. This is perfect for micro-emergencies, like a sudden pharmacy bill or a quick trip to the mechanic for a flat tire.
The speed is the real standout here. You might see money as soon as the same day. In a city where time is money, being able to fix a financial hiccup before the sun goes down is an incredible service for the working class. It provides a safety net when you simply cannot wait for a bank’s processing cycle.
Pros:
- Extremely fast approval and same-day funding potential
- No hard credit checks required
- Versatile loan amounts for various needs
- Lower maximum loan limits compared to personal loan specialists
5. Optimal PLO
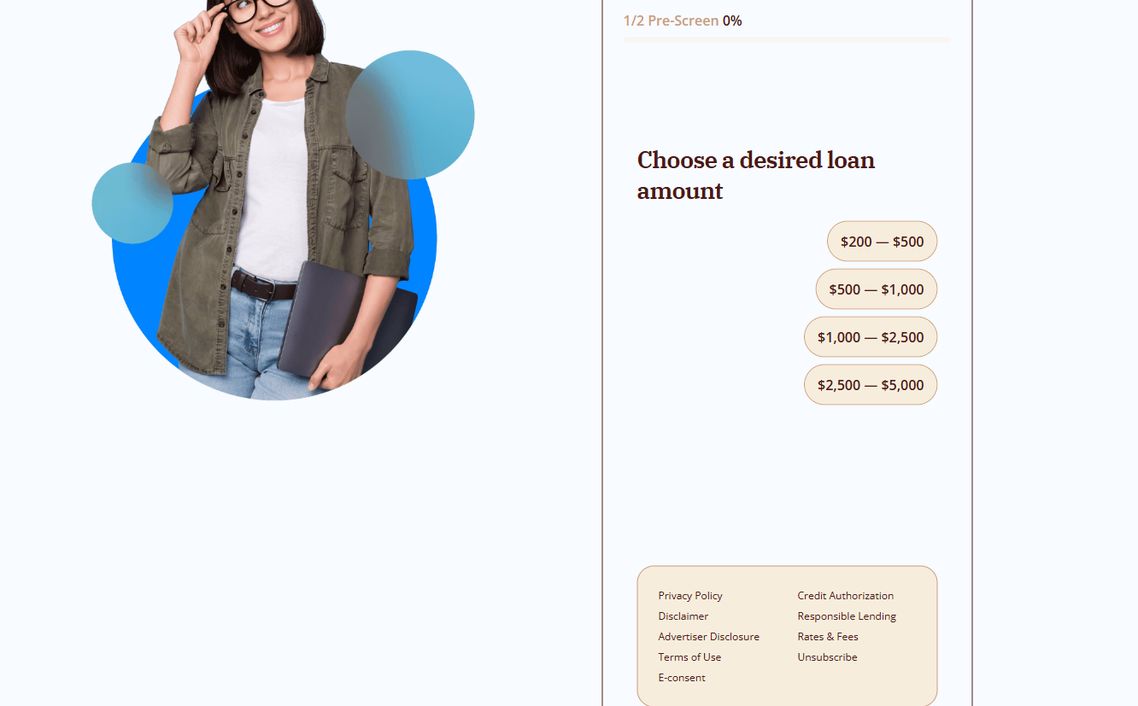
Optimal PLO acts like a specialized search engine for your debt. Instead of you hunting through dozens of websites, they search their network of lenders for you in real-time after you fill out a form. It saves you a massive amount of time and mental energy, which is a luxury when you are in a crisis.
This is perfect if you want to see many options without the repetitive paperwork. You provide your info once, and their system does the heavy lifting. Once a lender is found, you are sent directly to their page to see the specific terms. This keeps the final step transparent and clear.
Pros:
- Efficient search through a network of lenders
- Simple two-minute initial application form
- Real-time results with no expired offers
- You are dependent on the terms offered by the specific lender found in the network
6. United Finance
United Finance brings a sense of history to the table. They have been around since 1922, offering a more structured approach with personal and auto loans. In an era of fly-by-night fintech startups, having a lender with nearly a century of history provides a level of security that many borrowers find comforting.
They are a solid choice for New Yorkers who want a conventional experience. Their focus is on being simple and accessible, making them a reliable option for personal loans up to $20,000. Whether you want to consolidate high-interest cards or renovate a kitchen, they provide the stability of a traditional institution.
Pros:
- Long-standing reputation and established history
- Offers both personal and auto loan options
- Dedicated and friendly lending approach
- May not offer the “instant” speed of payday-style lenders
Understanding the Real Cost of Borrowing
Before you sign anything, look at the APR (Annual Percentage Rate) and the total interest. Many people only look at the monthly payment. A $500 loan with a $75 monthly payment sounds easy, but if it lasts twelve months, you’ve paid back $900. That is an 80% increase over what you originally took out.
Watch out for “prepayment penalties” too. Some lenders charge you a fee if you try to pay the loan off early. It sounds counterintuitive, but they make money when you stay in debt longer. Always ask, “If I pay this back two months early, will I be charged a fee?” You shouldn’t be punished for being responsible.
A Step-by-Step Guide to Securing Emergency Funds
If you are in a bind, following a plan can stop you from making expensive mistakes. Use these steps to handle your options efficiently:
- Step 1: Calculate the Exact Need. Don’t guess. Look at the actual invoice or bill. Borrowing $1,000 when you only need $650 just increases your interest burden for no reason.
- Step 2: Check Your Credit Score. Even with “no credit check” options, knowing your score helps you know if you qualify for better rates elsewhere.
- Step 3: Compare the Speed vs. Cost. If your car is broken and you can’t get to work, speed is your priority. If you are consolidating debt, look for the lowest interest rate.
- Step 4: Verify the Lender’s Legitimacy. Make sure the company is registered in New York. Never pay an “upfront fee” to get a loan; that is a major red flag for a scam.
- Step 5: Read the Repayment Terms. Check the due dates, late fees, and what happens if you miss a payment.
Avoiding Common Lending Pitfalls
When a crisis hits, you might want to grab the first offer you see. Remember that “no credit check” often means much higher interest rates. Read the fine print. A high-interest loan might solve a $500 problem today, but it could create a $2,000 problem next month if you aren’t careful.
Don’t ignore the total repayment amount. A $500 loan can easily end up costing you double or triple that if the terms are poor. Always ask for a clear breakdown of the total cost before signing. The goal is to solve a problem, not to create a new one. If the math doesn’t work, try negotiating a payment plan with your original creditor instead.