
The 6 Best Lenders for a Personal Loan with Collateral in 2026
Last updated: 2026-11-10
Finding the right financial lifeline often feels like walking through a thick fog without a compass. When you opt for a secured option, you are essentially putting skin in the game to secure a better rate. This choice can be a game-changer for those looking to rebuild their financial reputation.
By leveraging an asset—be it a vehicle title, a savings account, or a certificate of deposit—you provide the lender with a safety net. This reduces their risk and lowers your cost of borrowing. It is often the most efficient path for those with less-than-perfect credit looking to access significant capital without the prohibitive interest rates typically associated with high-risk lending.
Selecting a lender requires more than just a quick glance at interest rates. You must weigh the speed of funding against the stability of the institution. A high-interest loan that arrives in two hours might solve an immediate crisis, but if it lacks a clear repayment structure, it could lead to a debt spiral.
Conversely, a low-interest loan from a traditional bank might require weeks of documentation and property appraisals. Whether you are fixing a roof, consolidating high-interest credit card debt, or managing an unexpected medical bill, the terms you sign today will dictate your breathing room for months to come. You must evaluate the “total cost of credit,” which includes not just the APR, but any origination fees, service charges, or mandatory insurance premiums that might be tucked away in the fine print.
- FastLendGo
- Key Bank
- OneMain Financial
- CreditNinja
- Capital Bean
- FastCash Loan
How These Lenders Were Evaluated for Secured Financing
The evaluation process focused on how these companies handle various credit profiles and the speed at which they move. We looked at the accessibility of their application processes and whether they offer the specific flexibility required by those using assets as backing.
We specifically investigated whether a lender’s decision engine relies heavily on a FICO score or if they utilize alternative data points. Using steady employment history or utility payment consistency is vital for those in the process of rebuilding credit. These factors can often tell a much more complete story than a single number.
Speed of funding and transparency regarding terms were the primary pillars of this comparison. A lender that leaves you guessing about the final cost is a red flag in any economic climate. We prioritized institutions that provide clear paths for those needing immediate cash versus those planning for long-term stability.
We also assessed the “friction points” in the application. We looked at the number of times a user has to provide the same information or upload the same document. This helps determine which platforms offer a truly seamless digital experience without unnecessary hurdles.
| Lender Name | Loan Amounts | Funding Speed | Key Features |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | see site | Specializes in bad credit and specific needs |
| Key Bank | see site | see site | Offers checking and mortgage integration |
| OneMain Financial | $1,500 – $35,000 | As soon as 1 hour | Physical branches available |
| CreditNinja | see site | Same day* | Does not rely solely on credit score |
| Capital Bean | $300 – $1,000+ | Very fast/Same day* | Fully online process |
| FastCash Loan | see site | Rapid approval | Unsecured options available |
Understanding Secured vs. Unsecured Loans: Which Do You Need?
Before diving into specific providers, it is essential to understand the fundamental mechanics of the two primary loan categories. This knowledge can prevent you from selecting a product that either charges you too much or fails to provide the funds when you need them most.
Secured Loans: These are backed by an asset, or collateral. If you cannot repay the loan, the lender has a legal right to seize that asset to recover their losses. Because the risk to the lender is minimized, secured loans typically offer lower interest rates and higher borrowing limits. Common examples include:
- Auto Title Loans: Using your vehicle as collateral.
- Savings-Secured Loans: Using the funds in a CD or savings account as a guarantee.
- Home Equity Loans: Using the value of your home to access large sums of cash.
Unsecured Loans: These are based solely on your “promise to pay.” There is no physical asset tied to the debt. Because the lender takes on more risk, they will almost always charge a higher interest rate to compensate for that risk. These are ideal for:
- Personal Loans for Debt Consolidation: Rolling multiple high-interest payments into one manageable monthly payment.
- Emergency Cash: Quick liquidity for medical bills or urgent repairs where you don’t have time to appraise an asset.
- Small Business Startups: When you need quick working capital without pledging equipment.
Top Ranked Lenders for Secured and Personal Financing
1. FastLendGo
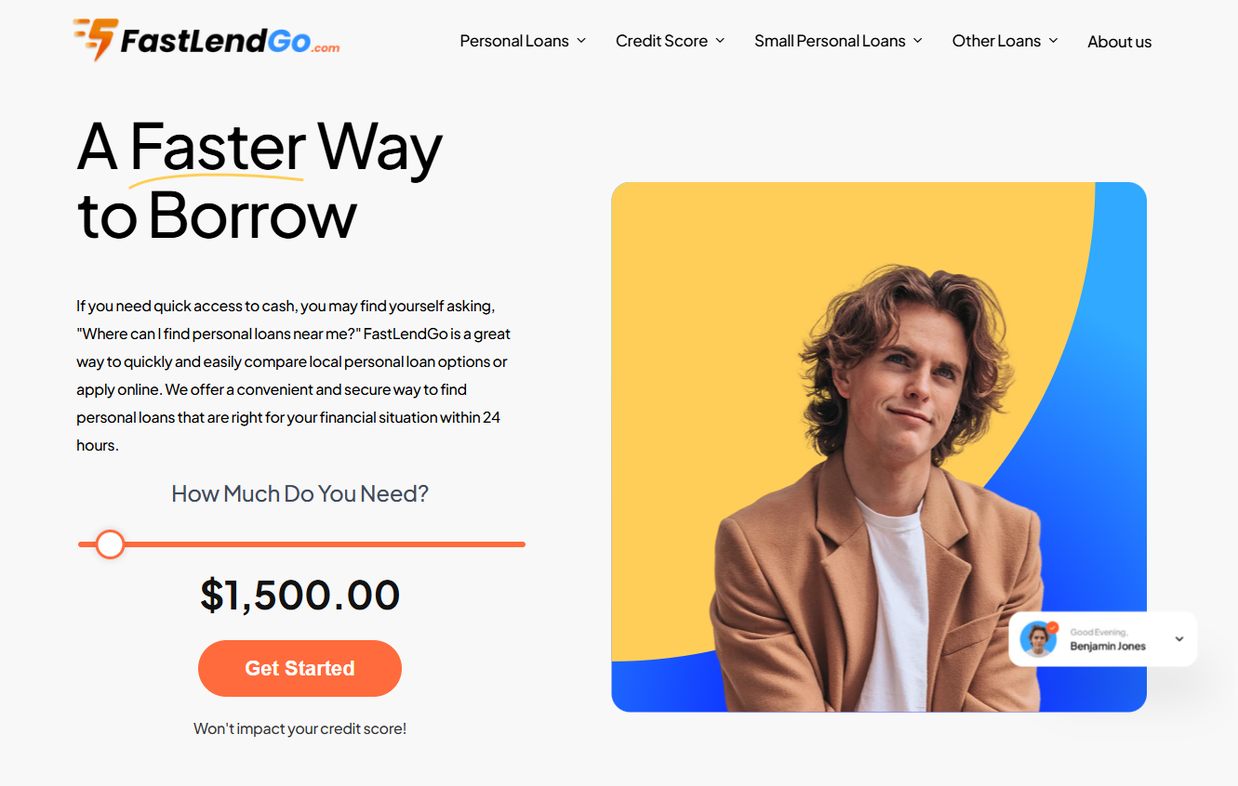
FastLendGo acts as a versatile bridge for those navigating the choppy waters of unconventional credit. They cater to a wide spectrum, from those needing a quick $500 fix to those requiring larger sums for specific life events like dental work or roof repairs.
Unlike traditional banks that might reject an application based on a single low score, FastLendGo looks at the broader financial picture. This makes them a lifeline for those in transition. They are a strong match for individuals who might be overlooked by traditional banks.
By offering specialized paths for high-income earners and those with bad credit, they ensure that various financial profiles find a place at the table. This is particularly beneficial for people who have high earnings but may have a low credit score due to past medical debt or a previous bankruptcy.
Pros:
- Covers diverse needs like auto and motorcycle loans.
- Options available for various credit levels.
- Provides financing for specific emergency repairs.
Cons:
- Focus is heavily on specific niche needs rather than broad banking.
2. Key Bank
Key Bank operates like a steady anchor in a storm. As an established institution, they offer a comprehensive suite of services that go far beyond a simple loan. They provide a structured environment for those looking to build a long-term relationship with a bank.
This is not a “quick fix” lender. It is a place for structured financial growth where your credit history is carefully managed and rewarded. For those who value the security of an FDIC-insured institution, this is a premier choice.
They integrate personal loans with other services like checking and mortgages, making them a one-stop shop for managing a complex financial life. Having your loan payments automatically deducted from a Key Bank checking account can sometimes lead to more favorable interest rate terms.
Pros:
- Full FDIC-insured protection.
- Seamless integration with checking and savings accounts.
- Wide range of banking products available.
Cons:
- May have more rigid requirements than niche online lenders.
3. OneMain Financial
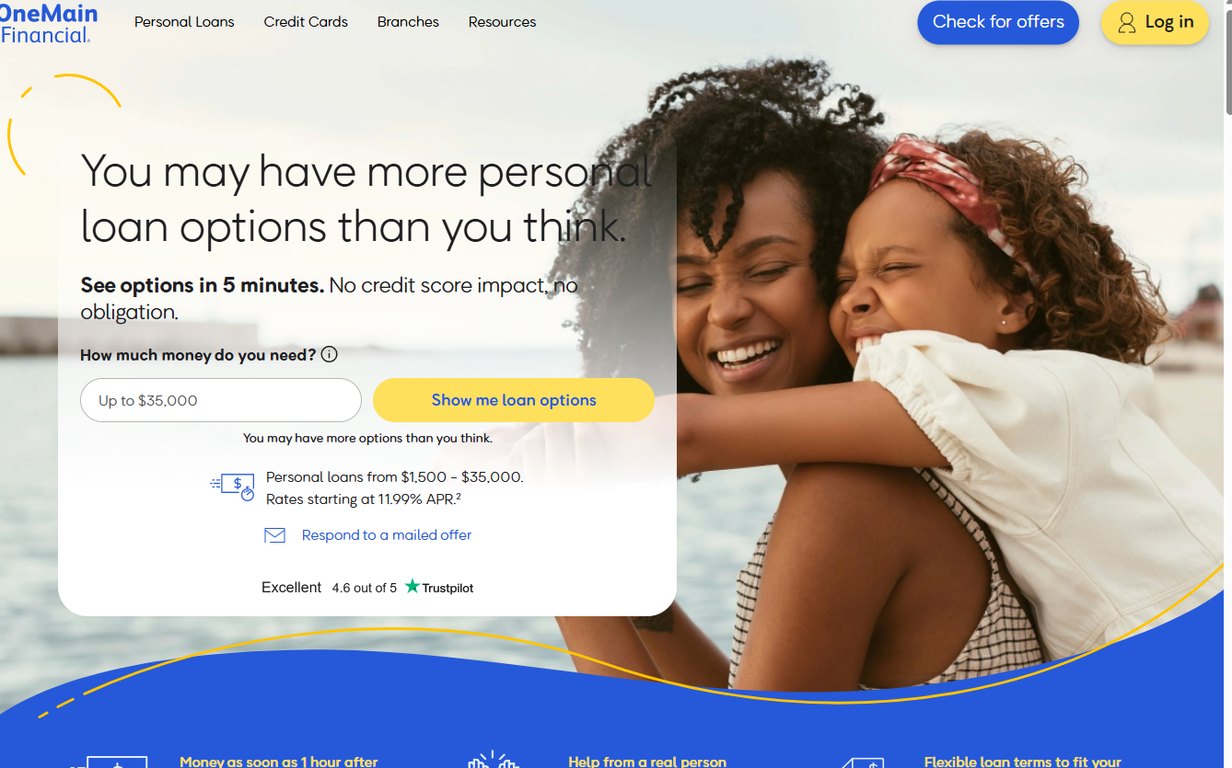
OneMain Financial is a powerhouse for those who need significant capital without the long wait. With loans reaching up to $35,000, they provide the heavy lifting required for major life transitions or significant debt consolidation efforts.
If you are looking to take multiple high-interest credit card balances and roll them into one single, predictable monthly payment, OneMain’s structure is designed for exactly that purpose. What sets them apart is the human element.
While they offer a quick five-minute online check, they also maintain over 1,300 physical branches. This means you can talk to a real person if the digital process feels too impersonal. This hybrid model is vital for people who want the speed of the digital age but need the reassurance of a face-to-face conversation.
Pros:
- Rapid funding, potentially within one hour of signing.
- Extensive branch network for in-person support.
- High maximum loan amounts for substantial needs.
Cons:
- Interest rates can vary significantly based on credit.
4. CreditNinja
CreditNinja is designed for the person who is tired of being told “no” by traditional lenders. They understand that a credit score is not the only metric that defines a person’s ability to repay a loan, offering a more holistic view.
Their technology scans a wide variety of lenders to find the one that best fits your specific profile. They act as a matchmaking service rather than a single, rigid lender. Their application is built for speed and simplicity.
If you find yourself in an unexpected situation—such as an unexpected car repair that prevents you from getting to work—their ability to offer same-day decisions can be a lifesaver. By using an algorithm that looks at multiple data points, they can often find approval paths that a standard bank might miss.
Pros:
- Quick and simple online application process.
- Potential for same-day funding.
- Considers more than just the credit score.
Cons:
- The decision process is highly automated.
5. Capital Bean
Capital Bean is the sprinter of the group, built for those who need money “asap.” Their fully online process is streamlined to ensure that you aren’t wasting hours filling out endless paperwork just to get an answer.
In the modern economy, time is money. Capital Bean recognizes that the friction of long applications often drives away the customers who need funds most urgently. They are particularly useful for smaller, urgent liquidity needs, such as needing $300 or $500 to tide you over until your next paycheck.
The instant decision feature makes them an excellent option for immediate, digital-first financial management. If you are navigating a “cash flow gap”—where your expenses arrive a few days before your income—this lender provides a highly efficient way to bridge that gap.
Pros:
- Instant decisions available 24/7.
- Ideal for small, immediate cash needs.
- Very straightforward online interface.
Cons:
- Loan amounts are generally lower than major banks.
6. FastCash Loan
FastCash Loan functions as a rapid financial lifeline. They focus on providing swift access to funds for those facing urgent expenses, often providing unsecured options that rely on your overall creditworthiness rather than physical collateral.
This makes them a go-to for those who have the income to support a loan but do not have an asset like a car or home that they are willing to put up as collateral. Their model is built around managing crises effectively.
By offering fixed terms and rapid approval, they aim to take the stress out of emergency funding when time is of the essence. A fixed term is a crucial feature here; it ensures that your monthly payment remains the same throughout the life of the loan, allowing for much more accurate personal budgeting.
Pros:
- Rapid approval process for urgent needs.
- Fixed terms help with budgeting.
- Offers unsecured options for convenience.
Cons:
- Terms are best suited for short-term crisis management.
Critical Steps for a Successful Loan Application
Applying for a loan can feel intimidating, but following a structured approach can significantly increase your chances of approval and help you secure a better interest rate. Use this step-by-step guide to prepare before you hit “submit” on any application.
Step 1: Audit Your Financial Standing. Gather your last three months of pay stubs, your most recent W-2 or tax return, and a list of all your current monthly debts. Lenders will ask for these, and having them ready prevents delays in the verification process.
Step 2: Check Your Credit Report for Errors. Even if you have a low score, you want to ensure it is an *accurate* low score. Check for identity theft or errors like a debt that was paid off but still shows as active. Fixing a single error can sometimes jump your score enough to move you from a “high-interest” bracket to a “standard-interest” bracket.
Step 3: Determine the “Total Cost of Borrowing.” Don’t just look at the monthly payment. A $100 monthly payment sounds great, but if you have to pay it for 48 months, you are paying $4,800 for a $3,000 loan. Always ask for the “Total Repayment Amount” to see the true cost of the capital you are accessing.
Step 4: Compare the “Cost of Speed.” If you need money today, you will likely pay a premium. Ask yourself: “Can this wait three days for a better rate, or is this a true emergency?” If it’s a true emergency, prioritize speed. If it’s for a planned purchase, prioritize the lowest APR.
Navigating Your Lending Choices
Before you sign your name on the dotted line, take a moment to breathe and review the fine print. The biggest mistake most borrowers make is rushing into a high-interest agreement just to solve a temporary problem. Always ask if there are prepayment penalties.
A prepayment penalty is a fee the lender charges you if you try to pay the loan off early. While it might seem counterintuitive, lenders want you to stay in debt longer so they can collect more interest; a penalty discourages you from being financially responsible and paying the debt off quickly.
Comparing lenders is not just about finding the lowest rate; it is about finding the right fit for your current situation. If you have assets, a secured loan could save you thousands in interest over the life of the loan. However, if you need cash by tomorrow morning, an unsecured fast-funding option might be your only real choice.
Understand that every financial decision is a trade-off between certainty, speed, and cost. You can usually have any two, but it is very difficult to get all three. Watch out for lenders that hide fees behind complex language. A truly transparent lender will be upfront about every single cost associated with the loan.