
Best Lenders for Loans for Postal Employees with Bad Credit in 2026
Last updated: 2026-11-10
Dealing with a sudden money crunch while working a demanding job at the post office can feel like walking through a blizzard without a coat. When credit scores take a hit, traditional banks often slam the door shut. This leaves hardworking federal employees searching for a lifeline. Finding a lender that understands your situation is the first step toward finding stability.
Maybe it is an unexpected medical bill or a sudden car repair that threatens your ability to commute to the station. Perhaps a home maintenance emergency has popped up out of nowhere. The stress of a temporary cash shortage can make it hard to focus on the job. You need a solution that respects your work ethic.
This ranking focuses on lenders that prioritize your employment status and your ability to repay over a single number in a database. We looked for speed and accessibility. We wanted to see how much these companies actually value your unique position as a postal worker. It is about finding a way over troubled waters, not just any old loan.
Your steady government paycheck is a significant asset. Many traditional lenders overlook this when they only look at a credit report. We want to highlight the companies that see the person behind the score. They see the reliability that comes with a federal career.
- Credit Ninja
- BMG Money
- JetzLoan
- Sun Loan
- Wells Fargo
- Sunbit
- NetCredit
How These Lenders Were Evaluated
The selection process involved looking at how each provider handles non-traditional credit profiles. Many postal workers rely on allotments or deal with fluctuating scores due to life events. A sudden change in household income or a period of medical leave shouldn’t ruin your financial future. We looked for lenders who can approve you based on your job stability.
We wanted to find those who offer quick decisions. This prevents emergencies from spiraling into long-term debt cycles. If you are stuck in a rut, you need a way out that doesn’t involve waiting weeks for an answer. Speed is a necessity when the bills are piling up on the kitchen table.
Speed of funding was the second major pillar of our comparison. If someone needs money for a car repair to get to their route, waiting two weeks is not an option. We analyzed the availability of same-day or 24-hour funding across the options. The most efficient lenders rose to the top of this list.
A lender that takes too long to move can sometimes be as unhelpful as a lender that won’t approve you at all. We needed to know who can actually get the cash into your hands when it matters most. Efficiency is the name of the game for someone facing a sudden crisis.
We also scrutinized the transparency of their fee structures. Many high-interest lenders hide the true cost of borrowing behind complex language. Our evaluation sought lenders that are upfront about origination fees, late penalties, and total interest costs. You need to know exactly what you are signing up for.
We wanted to ensure that the “solution” provided by the lender doesn’t become a new problem for a postal worker trying to get their finances back on track. Transparency is non-negotiable. You shouldn’t be surprised by a massive fee when you are already struggling to make ends meet.
| Lender Name | Max Loan Amount | Terms | Funding Speed | Credit Impact of Inquiry |
|---|---|---|---|---|
| Credit Ninja | See site | Flexible | Same day* | Not mentioned |
| BMG Money | $12,000 | 6-48 months | Instant | Apply regardless of score |
| JetzLoan | $50,000 | See site | As little as 24 hours | No hard credit pull |
| Sun Loan | $10,000 | See site | Same day available | Soft inquiry for pre-qual |
| Wells Fargo | See site | See site | See site | See site |
| Sunbit | See site | See site | See site | See site |
| NetCredit | $10,000 | Flexible | Same-day available* | Won’t affect FICO score |
Top-Rated Lenders for Postal Workers
1. Credit Ninja
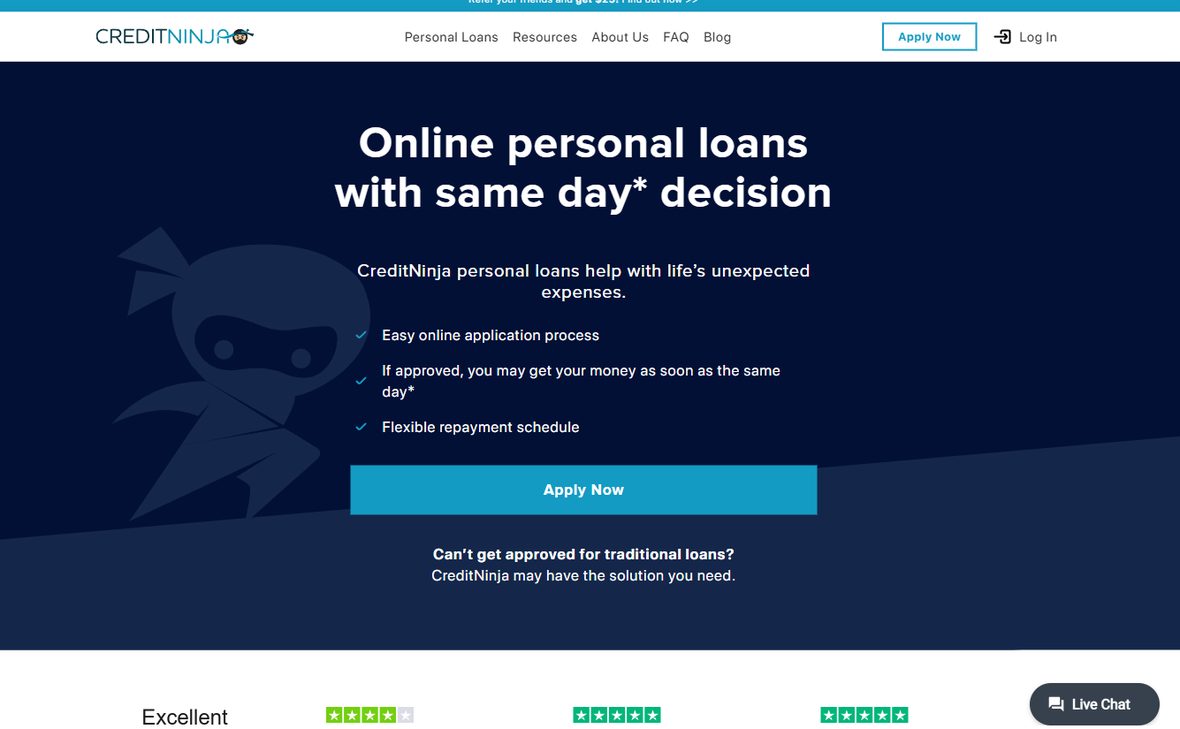
Credit Ninja is a strong contender for those who feel stuck because of their credit score. They offer a straightforward online application. It doesn’t just stare at a FICO number, but looks at the bigger picture of your financial health. This approach often includes evaluating your income stability and your current debt-to-income ratio.
This is vital for someone with a steady, predictable government salary. If you find yourself in a pinch, the speed here is hard to beat. They aim for same-day decisions. This can be a lifesaver when an unexpected expense pops up right before payday.
The platform is built for the modern worker who needs answers fast. You won’t spend hours on hold with a customer service representative. Their system is designed for efficiency, moving you from application to decision in a matter of minutes.
Pros:
- Quick and simple online application process.
- Potential for same-day decisions and funding.
- Considers more than just your credit score.
Cons:
- Approval is not guaranteed and depends on personalized factors.
2. BMG Money
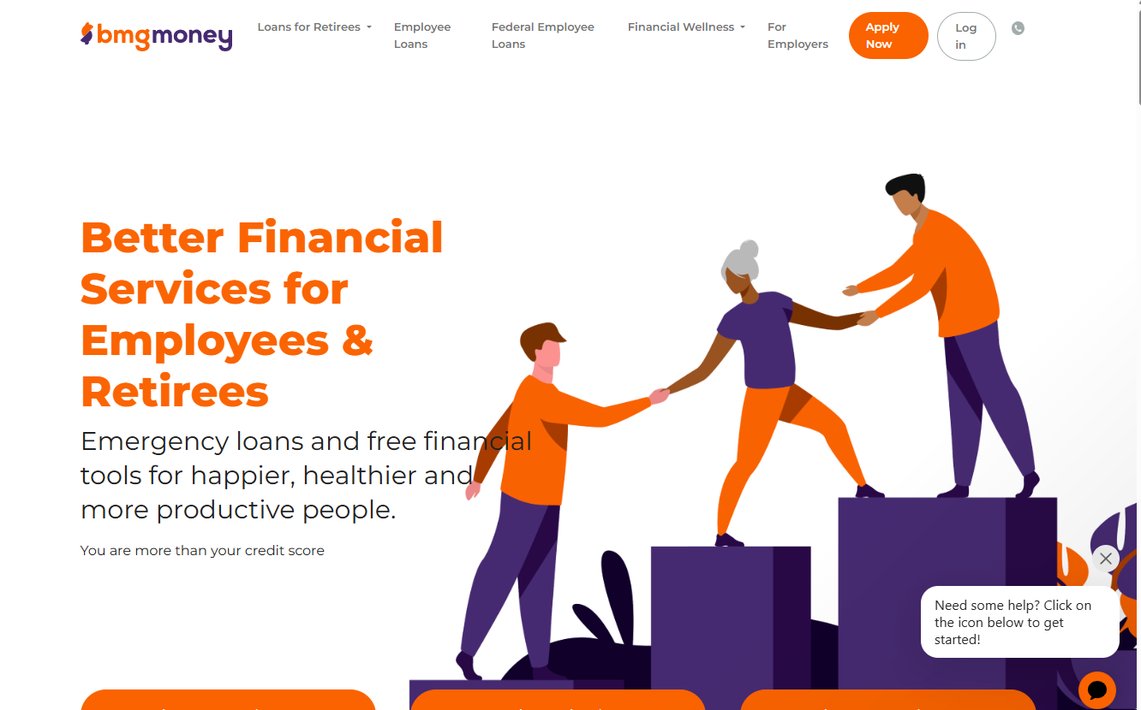
BMG Money stands out because they specifically cater to employees and retirees. They understand that your paycheck is steady. That makes you a much better bet than a random applicant with irregular freelance income. This specialized focus is a breath of fresh air for federal employees.
You might have a high level of job security but a lower credit score due to past financial mismanagement. BMG Money sees that distinction. Their loan amounts are quite practical, ranging from $500 up to $12,000. This makes them ideal for mid-sized emergencies like a dental procedure or an appliance replacement.
With terms spanning 6 to 48 months, you can pick a repayment schedule that doesn’t leave you feeling underwater. A shorter term means less interest paid overall. A longer term keeps your monthly payments manageable. They also offer instant funding for many of their borrowers.
Pros:
- Specifically designed for employees and retirees.
- Loan amounts up to $12,000.
- Instant funding options available.
Cons:
- Interest rates can be high, ranging from 19.99% to 35.99%.
3. JetzLoan
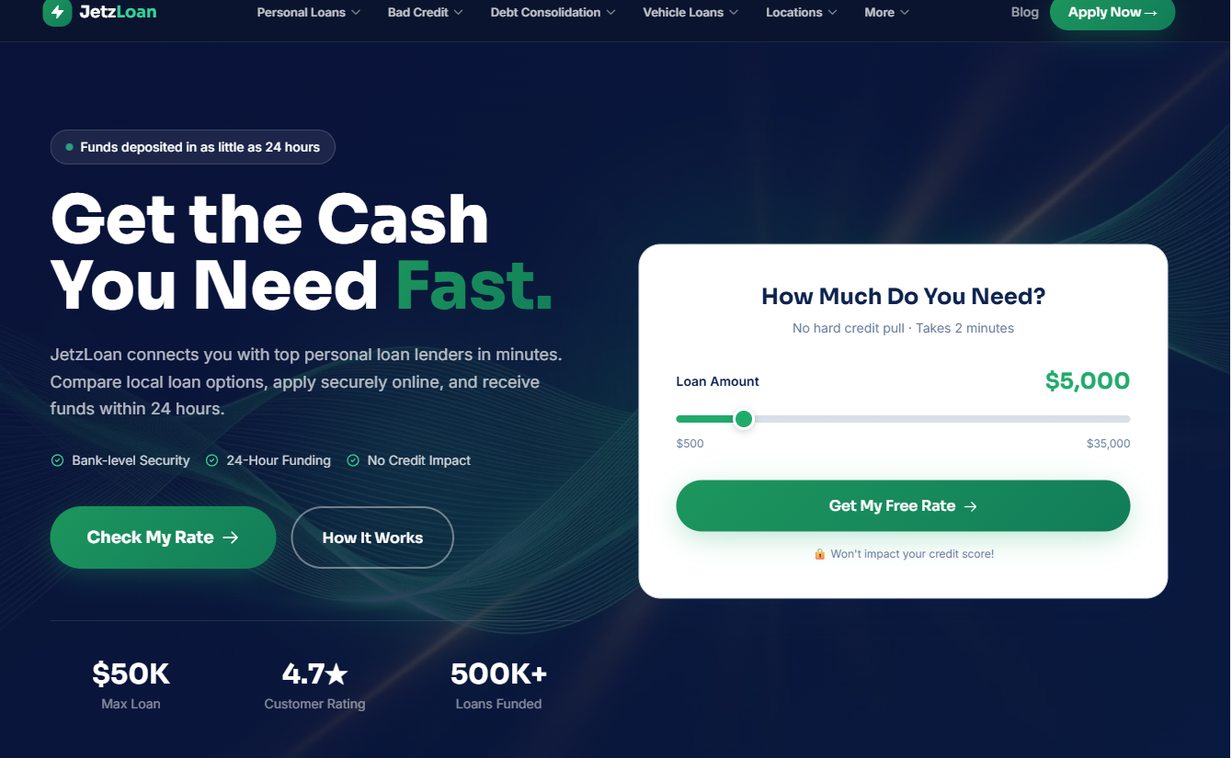
JetzLoan acts as a connector, linking you with top personal loan lenders in a matter of minutes. This is perfect for the postal worker who wants to see a variety of options without jumping from website to website. Instead of applying to ten different lenders, JetzLoan streamlines the whole comparison process.
It is a one-stop shop for comparison, saving you valuable time after a long shift. The most significant benefit here is the “no hard credit pull” feature for checking rates. You can see what you might qualify for without bruising your credit score further.
This is a critical distinction. Many people damage their ability to get a mortgage or a car loan later by “rate shopping” too aggressively. With a maximum loan of $50,000, it covers everything from small repairs to larger debts like debt consolidation.
Pros:
- No hard credit pull to check your rate.
- Connects you to multiple lenders quickly.
- High maximum loan amount of $50,000.
Cons:
- You are matching with third-party lenders, not a single direct source.
4. Sun Loan
Sun Loan offers a more traditional feel with the convenience of modern technology. They allow you to apply both online and in-branch. This is great if you prefer talking to a real person about your financial situation. Sometimes, a conversation provides a level of clarity that a digital form simply cannot match.
This is especially helpful when discussing sensitive topics like repayment terms or specific financial hardships. They are very careful about your credit score during the initial stages. You can pre-qualify using a “soft” inquiry, meaning you won’t see a dip in your score just for checking.
This allows you to shop around with confidence. You can determine your eligibility before making any formal commitment. Their physical presence also provides a sense of security and accountability that many digital-only lenders lack.
Pros:
- Choice of online or in-branch applications.
- Soft credit inquiry for pre-qualifying.
- Loans available up to $10,000.
Cons:
- A hard credit inquiry is required if you actually accept the loan.
5. Wells Fargo
Wells Fargo is a massive, established institution that many people turn to for their primary banking. While they have very high standards for credit, they offer a wide suite of financial services. They are a heavyweight in the banking world, providing a sense of permanence.
For many postal workers, having a relationship with a major bank can make future financial endeavors, like a mortgage, slightly smoother. For those who manage to maintain a decent score, their products are incredibly stable. They offer everything from checking accounts to complex wealth management.
However, you must manage your expectations. They are not specifically tailored toward those with bad credit or those needing high-risk, fast-turnaround personal loans. They are a mainstream option that works best for those who already have a solid financial foundation.
Pros:
- Highly established and reputable banking institution.
- Wide variety of financial products and services.
- Offers various promotional bonuses for new accounts.
Cons:
- Strict credit requirements may make them difficult for those with bad credit.
6. Sunbit
Sunbit is not a traditional loan provider but a “pay over time” technology. This is incredibly useful for specific, high-cost needs like dental work, auto repairs, or eye care. Instead of taking out a massive lump-sum personal loan, Sunbit allows you to pay the merchant directly through a structured plan.
This prevents the temptation to spend the loan money on other non-essential items. The beauty of this system is its transparency. They aim for fair rates. Most importantly, there are no late fees or hidden origination charges that can catch you off guard.
It is a specialized tool designed to solve specific, urgent life expenses without the baggage of a traditional high-interest personal loan. If your car needs a new alternator or your child needs braces, Sunbit is a highly targeted solution.
Pros:
- No late fees or origination charges.
- Transparent interest rates.
- Ideal for specific services like dental or auto repair.
Cons:
- Limited to specific merchants and types of services.
7. NetCredit
NetCredit uses advanced algorithms to look beyond your FICO score. They realize that a number in a database doesn’t tell the whole story of a person’s reliability. This makes them a very human-centric option for those struggling to find traditional help.
They look at your overall financial behavior. This can be a major advantage for someone whose credit score was temporarily damaged by a single medical event or a period of unemployment. They provide loans up to $10,000 with flexible terms and same-day funding possibilities.
This makes them a solid choice for someone who needs a quick injection of cash to get their finances back on the right track. Whether it is paying off high-interest credit card debt or covering an emergency repair, their process is designed to be frictionless.
Pros:
- Uses advanced algorithms to assess creditworthiness.
- Flexible terms and same-day funding available.
- Checking eligibility does not affect your FICO score.
Cons:
- Availability may be limited to certain states.
Understanding the Real Cost of Borrowing
Before signing your name on the dotted line, it is vital to look at the total cost of borrowing. Many borrowers make the mistake of only looking at the monthly payment amount. For example, a $1,000 loan with a $50 monthly payment sounds easy. But if the term is 36 months, you will end up paying significantly more than the original amount borrowed.
Always ask for the “Total Cost of Loan” and the “Annual Percentage Rate (APR).” The APR is the most accurate way to compare different lenders. It includes both the interest rate and any mandatory fees. You need the full picture to avoid a financial trap.
Consider the impact of compounding interest. If you are taking out a loan to pay off other debt, ensure the interest rate on this new loan is lower than what you are currently paying. If you are taking out a loan for an emergency, ensure the repayment schedule is one you can strictly adhere to. A single missed payment can trigger late fees and further damage your credit score.
Smart Strategies for Managing Debt as a Federal Employee
As a postal worker, you have access to certain financial advantages that the private sector might not offer. Understanding how to leverage these can help you manage debt more effectively. For instance, if you find yourself in a deep financial hole, consider looking into the specifics of your Thrift Savings Plan (TSP) or other federal retirement benefits.
While it is generally advised not to withdraw from your retirement accounts early due to taxes and penalties, understanding how these assets interact with your overall net worth can provide a sense of long-term stability. It is about knowing where you stand in the long run.
Additionally, many federal employees are eligible for specific consumer protections or have access to credit unions that offer lower rates than commercial banks. Before turning to a high-interest short-term lender, check if your local credit union offers “emergency” or “small-dollar” loans. These are often designed specifically for people in your position and frequently come with much more favorable terms.
Using the right tool for the right job can save you thousands of dollars over your lifetime. Whether it is a specialized service like Sunbit for dental work or a comparison tool like JetzLoan for a large debt, make sure you choose the one that fits your specific need.