
The 6 Best Lenders for Bad Credit Loans in Arkansas for 2026
Last updated: 2026-11-10
Trying to find financial help when your credit score is low can feel like driving through a thick Arkansas fog. You know you need a lifeline, but every door seems to slam shut the moment you mention your history. It is a stressful cycle that often leaves people hunting for quick fixes rather than solutions that actually last.
Maybe you are facing an unexpected medical bill in Little Rock or an urgent car repair in Fayetteville. Perhaps it is a sudden home maintenance issue in Jonesboro. The feeling of being “unbankable” can be paralyzing when you just need to get through the week.
When searching for these products, the goal is to find a balance between accessibility and affordability. Getting cash today is great, but you don’t want interest rates to sink your budget tomorrow. A high-interest payday loan might solve a Friday problem, but it creates a Monday disaster that haunts you for months.
This list focuses on lenders that offer paths forward for those dealing with difficult financial terrain. We emphasize long-term stability over short-term relief. We want to help you find a way through, not just a way to patch a hole.
- Bank of Little Rock
- SkyOne Credit Union
- JetzLoan
- Sunward
- Union Bank
- Prosper
How Arkansas Lenders Were Evaluated
We focused on how accessible these lenders are for people with less-than-perfect credit histories. In Arkansas, local familiarity often matters just as much as the interest rate. We looked for entities that provide clear paths to application and do not hide their terms behind a mountain of fine print.
Our analysis looked at the transparency of fee structures, the ease of digital applications, and how fast funds actually arrive. We prioritized speed and transparency. If you are facing an emergency, waiting two weeks for an answer is not an option.
Lenders that offer rapid decisions or quick funding windows earned a higher standing in this ranking. We didn’t just look at the interest rates. We looked at the “total cost of borrowing,” which includes origination fees, late penalties, and the impact the application itself has on your credit score.
| Lender Name | Loan Amounts | Funding Speed | Credit Impact |
|---|---|---|---|
| Bank of Little Rock | see site | see site | see site |
| SkyOne Credit Union | see site | see site | see site |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Sunward | see site | Minutes for pre-qual | No impact to credit |
| Union Bank | see site | see site | see site |
| Prosper | $2,000 – $50,000 | Fast funding | Your credit will be impacted |
Top Rated Lenders for Arkansas Residents
1. Bank of Little Rock
This institution is a bedrock for personal and business banking within the state. It is an FDIC-insured entity, which means your money is backed by the full faith and credit of the U.S. Government. This provides a sense of security that many online-only lenders simply cannot match.
When you are dealing with significant debt or large loan amounts, knowing your institution is stable and regulated is vital for peace of mind. They offer affordable financing for various personal needs, such as catching up on existing payments or funding a much-needed vacation.
Their approach is built around personal service. It is a breath of fresh air in an era of automated chatbots and endless phone menus. Because they are a traditional bank, you can often walk into a branch to discuss your specific situation with a loan officer. They can look at your entire financial picture rather than just a single numerical score.
Pros:
- FDIC-insured security
- Personalized banking service
- Versatile personal loan options
Cons:
- Likely requires more traditional documentation
- May have stricter requirements than online lenders
2. SkyOne Credit Union
SkyOne operates with a community-first mindset, focusing on helping families build savings and plan for the future. Unlike big national banks that prioritize shareholder profits, credit unions are member-owned cooperatives. This structure often translates to more favorable interest rates and a genuine interest in your success.
They provide a variety of products, including auto loans and home loans, which can be vital for those trying to rebuild their financial standing. Their services extend beyond simple lending. They offer tools to help families thrive through smart savings and protection.
It is a holistic approach to finance that looks at the person, not just the number on a credit report. For example, if you are struggling with debt, a credit union might offer debt consolidation options that are more manageable than the high-interest credit cards you are currently carrying.
Pros:
- Focus on family financial growth
- Diverse loan products available
- Community-oriented approach
Cons:
- Credit union membership requirements may apply
- Less focus on immediate emergency cash
3. JetzLoan
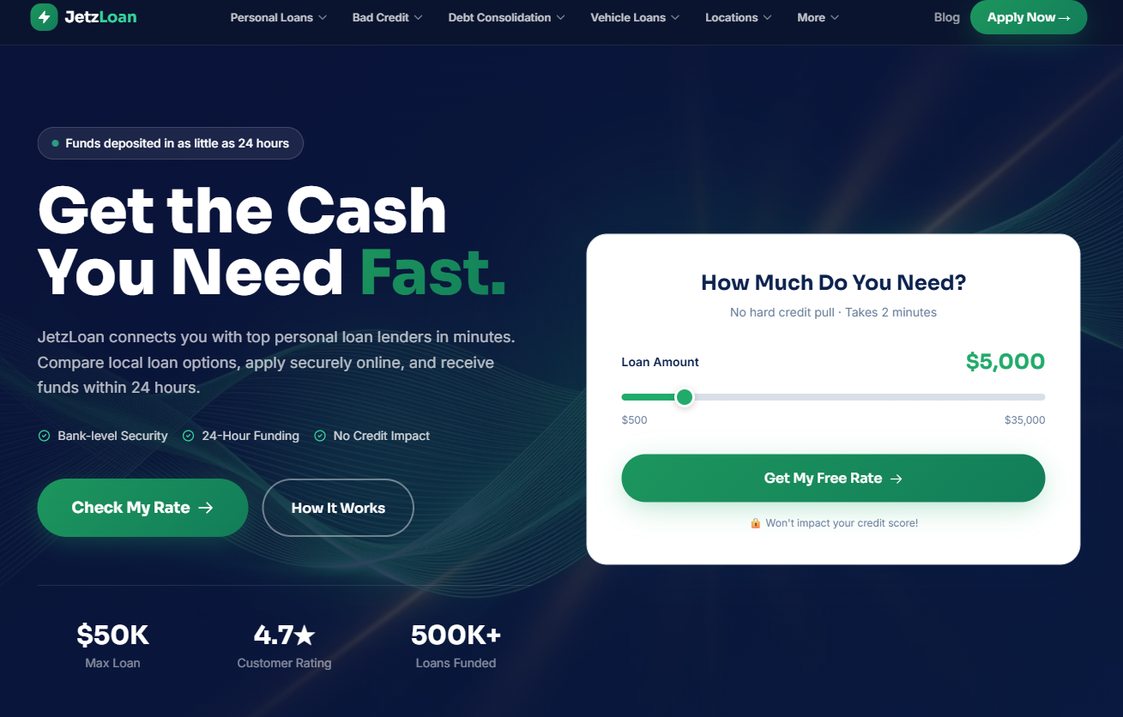
If you are in a pinch and need cash in a heartbeat, JetzLoan is built for speed. They boast that funds can be deposited in as little as 24 hours. This makes them a top choice for urgent situations like a sudden medical emergency or an unexpected transmission failure in your vehicle.
The process is designed to be incredibly streamlined. It bypasses the lengthy paperwork and long waiting periods typical of traditional banking institutions. One of the biggest perks is their “no hard credit pull” policy during the initial phase.
This means you can check your rate without worrying about your score taking a hit. This is a critical advantage for those who are already worried about their credit. You can shop for the best rate with zero risk to your existing score. It is a low-pressure way to see if you qualify for up to $35,000.
Pros:
- Extremely fast 24-hour funding
- No credit impact to check rates
- High customer rating
Cons:
- Maximum loan amount may be lower than banks
- Online-centric may lack personal connection
4. Sunward
Sunward provides a modern way to explore your options through their instant pre-qualification tool. You can find out where you stand regarding personal loans or credit cards in just a few minutes. This is particularly useful for individuals managing multiple financial obligations.
You can see how a new line of credit would fit into your monthly budget without committing to a formal application immediately. They also offer specialized products like the CC Flow Line of Credit, which can provide limits between $250 and $3,500.
This can be a great tool for managing smaller, day-to-day expenses without taking on massive long-term debt. If you have a recurring monthly expense that is slightly higher than your income, a small line of credit can bridge that gap temporarily without the heavy weight of a long-term personal loan.
Pros:
- Rapid pre-qualification process
- Flexible line of credit options
- No credit score impact for estimates
Cons:
- Line of credit limits can be quite low
- Interest rates vary by membership
5. Union Bank
Union Bank maintains a strong presence across Arkansas with several convenient locations, including Mena and Clarksville. This makes them an excellent choice for those who prefer to sit down with a human being to discuss loan options. You can talk through your needs face-to-face.
In many cases, being able to bring physical proof of income—like pay stubs or tax returns—directly to a banker can help expedite the approval process. This is especially helpful for those with unconventional income streams. They offer a wide array of services ranging from personal checking to vehicle loans.
This makes them a “one-stop shop” for residents who want to manage their entire financial life under one roof. Having your checking account and your loan at the same institution can sometimes simplify the repayment process. It gives you a clearer view of your overall financial health through their integrated banking tools.
Pros:
- Multiple physical locations for in-person help
- Comprehensive range of banking products
- Established and stable institution
Cons:
- Physical branch visits may be required for some services
- May have more rigid credit requirements
6. Prosper
Prosper is a major player in the online lending space, offering significant loan amounts up to $50,000. They are well-known for their efficient digital process. They have received high marks for their service quality in recent years. Because they operate as a peer-to-peer lending platform, they often have different risk appetites than traditional banks.
This can lead to more flexible terms for those with varying credit profiles. They offer flexible terms, including 6-year options, which can help make monthly payments more manageable. If you are borrowing $10,000 to consolidate debt, a 6-year term might lower your monthly obligation significantly compared to a 3-year term.
This provides much-needed breathing room in your monthly budget. However, unlike some other options on this list, your credit score will be impacted when you apply for a loan here. The formal application requires a hard credit inquiry.
Pros:
- High maximum loan amounts
- Flexible 6-year repayment terms
- Highly rated customer experience
Cons:
- Application will impact your credit score
- Strictly online-based interaction
How to Prepare Your Application for Success
When you are applying for a loan—especially if your credit isn’t perfect—the way you present your financial life can make a significant difference. Lenders want to see stability. Even if your credit score is low, showing a consistent history of income and a clear purpose for the loan can tip the scales in your favor.
First, gather all your documentation before you start the application. This includes recent pay stubs, W-2 forms, and perhaps a recent utility bill to verify your Arkansas residency. Having these ready prevents delays and shows the lender that you are organized and serious about your financial responsibilities.
If you are self-employed, have your last two years of tax returns readily available. This is often a mandatory requirement for non-traditional income streams. Second, be honest about your debt-to-income ratio (DTI). DTI is the percentage of your monthly gross income that goes toward paying debts. Lenders use this to determine if you can afford to take on even more debt.
If you have high credit card balances, consider paying down even a small amount before applying. This can slightly improve your score and your DTI. This makes you a more attractive candidate to lenders like Prosper or Bank of Little Rock. Third, review your credit report for errors. A common mistake is not realizing there is a late payment from three years ago that is still dragging your score down.
Many errors are fixable. If you find a mistake, dispute it with the credit bureau immediately. A single error can be the difference between a “qualified” and “denied” status when applying for a high-limit loan.
Understanding the Fine Print: APR vs. Interest Rate
One of the most dangerous mistakes a borrower can make is focusing solely on the interest rate. While the interest rate tells you the cost of borrowing the principal amount, it does not tell the whole story. To truly understand what a loan will cost you, you must look at the Annual Percentage Rate (APR).
The APR includes the interest rate plus any other fees required to get the loan, such as origination fees, documentation fees, or mortgage insurance. Consider this comparison:
| Feature | Interest Rate | APR |
|---|---|---|
| Definition | The percentage charged for the principal borrowed. | The total yearly cost of the loan, including interest and fees. |
| Example Use Case | Helps you understand the monthly interest charge. | Helps you compare two different lenders accurately. |
| Impact on Cost | Only affects the interest portion of your payment. | Reflects the “real” cost of the loan. |
For example, Lender A might offer a 10% interest rate with a $500 origination fee, while Lender B offers a 11% interest rate with zero fees. On the surface, Lender A looks cheaper. However, when you calculate the APR, Lender B might actually be the more affordable option over the life of the loan.
Always compare the APR when shopping between companies like JetzLoan and Prosper to ensure you are making an informed decision. Before you sign on the dotted line, it is vital to understand the total cost of borrowing. A loan might look attractive because of its monthly payment, but the total interest paid over the life of the loan could be staggering.
Avoid the temptation to jump at the first offer that comes your way. Comparison shopping is your best defense against high interest rates. Use the pre-qualification tools offered by many of these lenders to see what you qualify for without damaging your credit score.
Another common mistake is borrowing more than you strictly need. It is easy to get caught up in the excitement of a large sum of money, but every extra dollar you borrow is a dollar you have to pay back with interest. Stick to your budget and your original purpose for the funds.
Finally, remember that your relationship with a lender is a marathon, not a sprint. Repaying your loan on time is the most effective way to repair your credit. Once you have successfully navigated a small loan, you will find that the doors to better financial opportunities swing open much wider.