
The 5 Best Flooring Financing Options for Home Renovations in 2026
Last updated: 2026-11-10
Walking into a showroom and falling in love with a rich, walnut hardwood can feel like a dream until the total estimate hits your inbox. Suddenly, that beautiful floor feels like a mountain of debt rather than a home upgrade. This is where specialized financing steps in to bridge the gap between your vision and your bank balance.
Choosing the right lender is not just about the lowest interest rate. It involves looking at how quickly you can get the cash, how your credit score is treated during the application, and whether the terms fit your long-term budget. For instance, a low-interest loan might seem attractive, but if it requires a three-week approval process, your contractor might move on to another job before your materials even arrive. This guide breaks down the top contenders to help you navigate these financial waters.
- Acorn Finance
- FastLendGo
- Synchrony
- Affirm
- World of Floors
How We Evaluated These Flooring Lenders
The selection process focuses on accessibility and speed. Since home renovation projects often depend on contractor schedules, a lender that drags its feet can stall a whole project. We looked for providers that offer quick decisions and, where possible, soft credit pulls to protect your score during the initial inquiry phase. A “soft pull” allows you to gauge your eligibility without the 5 to 10-point dip often associated with a “hard pull” inquiry.
We also weighed the necessity of flexibility. Some homeowners need a lump sum to pay a contractor upfront to secure a spot on their calendar, while others prefer the “buy now, pay later” model for smaller upgrades like a single room of laminate. The goal is to match the lender’s structure to the specific scale of the flooring project. We analyzed lenders based on three key pillars: speed of disbursement, ease of application, and the clarity of their terms.
| Lender Name | Typical Loan Amounts | Credit Requirements | Speed of Funding | Key Feature | |
|---|---|---|---|---|---|
| Acorn Finance | See site | Good & Bad Credit | Fast | $0 dealer fees | |
| FastLendGo | $500 – $5,000+ | Bad to Great Credit | Quick access | Personal loan focus | |
| Synchrony | See site | See site | See site | Seconds | Marketplace variety |
| Affirm | See site | See site | Instant decision | No hidden fees | |
| World of Floors | See site | Approved credit | See site | 0% interest options |
Understanding the Different Types of Flooring Financing
Before diving into specific lenders, it is crucial to understand that not all flooring financing is created equal. Depending on your project scope, you will likely encounter one of three main categories of credit:
- Unsecured Personal Loans: These are fixed-term loans where the money is deposited directly into your bank account. You can use it for anything, including paying a contractor, buying materials, or even covering unexpected subfloor repairs. These are ideal for medium-to-large projects where you need a single lump sum.
- Store Credit/Retail Financing: These are often revolving lines of credit offered by the showroom itself. They are excellent for “zero interest if paid in full within X months” promotions, but they carry high risks; if you miss a single payment or fail to pay the full balance by the deadline, you may be charged interest retroactively from the original purchase date.
- Buy Now, Pay Later (BNPL): This is best for smaller, modular upgrades. If you just want to replace the luxury vinyl plank in your guest bathroom, BNPL allows you to split that specific cost into predictable, smaller installments without the complexity of a full-scale construction loan.
Top Rated Flooring Financing Rankings
1. Acorn Finance
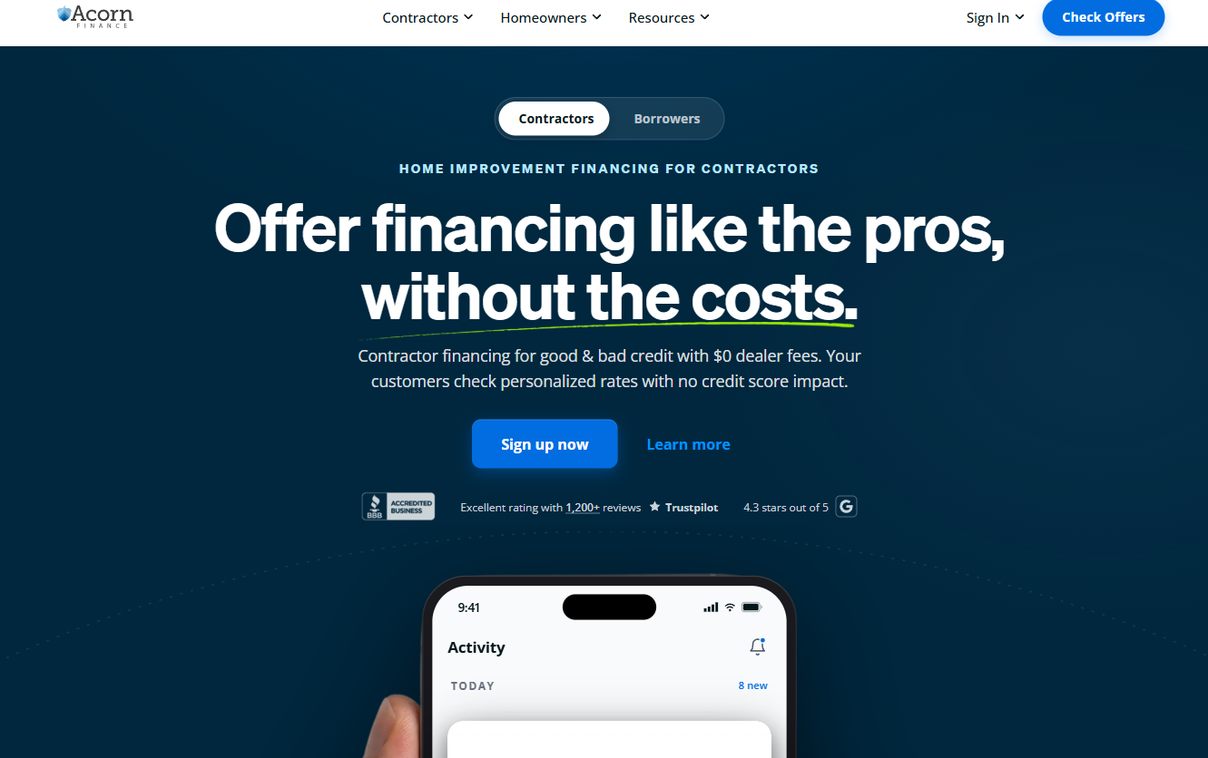
Acorn Finance operates like a specialized marketplace designed specifically for home improvement. Instead of jumping between dozens of banks, you can see personalized rates through a single platform. It is a lifeline for those who need to match their financing to the specific needs of a contractor-led project. Because they act as a middleman between you and various lenders, they can often find a match that a single bank might overlook.
This option is particularly suited for homeowners who are wary of the “hard inquiry” trap. You can check your rates without impacting your credit score, which is a massive relief when you are still in the planning stages and comparing different flooring types like tile versus hardwood. It covers everything from simple carpet swaps to massive deck installations or complete basement refinishing.
Pros:
- $0 dealer fees for contractors
- Personalized rates with no credit score impact during checking
- Options available for both good and bad credit
Cons:
- The marketplace model means rates vary significantly between different lenders
2. FastLendGo
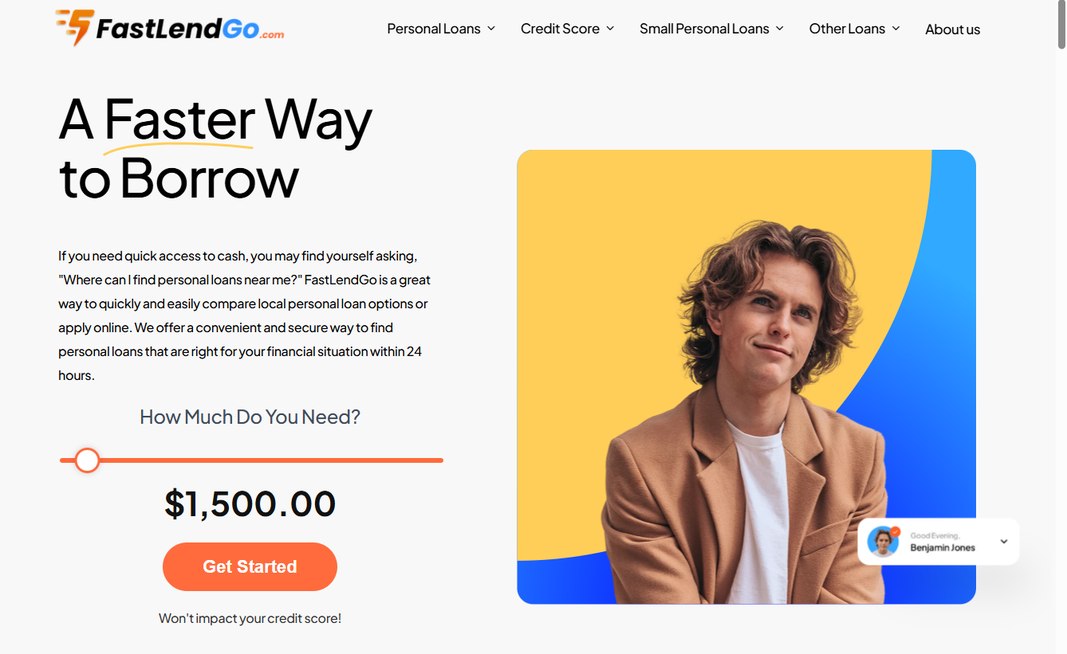
FastLendGo is the go-to option for those who need cash in hand without the traditional red tape of a mortgage or a home equity line of credit (HELOC). If you are looking for a personal loan to cover a specific repair, such as a sudden bathroom floor replacement due to water damage, this provider focuses on speed and accessibility. You won’t have to wait weeks for an appraisal or home inspection; the focus is on your personal creditworthiness and immediate need. (fastlendgo.com)
They cater to a wide spectrum of financial backgrounds, offering solutions for people with bad credit up to those with great credit. Whether you need a tiny $500 boost to cover the cost of high-end grout and adhesive, or a larger sum for a motorcycle or auto repair that happened to overlap with your home renovation schedule, the platform is built for quick access to cash.
Pros:
- Covers a wide range of loan sizes from $500 upward
- Designed for quick access to cash
- Accepts various credit levels including bad credit
Cons:
- Focuses on personal loans which may have different terms than specialized construction loans
3. Synchrony
Synchrony is a heavy hitter in the retail financing world, acting as the backbone for many major home brands and specialized flooring showrooms. If you are shopping at a specific furniture or home goods store, you will likely encounter their credit options right at the checkout counter. They are the industry standard for retail-specific credit lines.
Their strength lies in their massive marketplace and the ability to get a decision in seconds. For the shopper who wants to walk into a store, pick out a rug or a piece of furniture, and leave with a plan immediately, Synchrony is hard to beat. Their application process is streamlined to work seamlessly with point-of-sale systems in high-end showrooms.
Pros:
- Extremely fast decision-making process
- Wide variety of brand-specific financing options
- Secure and established financial institution
Cons:
- Terms are often tied strictly to specific retailers or brands
4. Affirm
Affirm has mastered the “Buy Now, Pay Later” movement, making it incredibly easy to manage smaller, high-impact flooring upgrades. It is perfect for the modern shopper who wants to see exactly what they will pay in interest—or lack thereof—before they commit. This transparency is a stark contrast to traditional credit cards where the interest is often obscured in fine print.
There is a certain peace of mind that comes with knowing there are no hidden fees. You see your total cost upfront, including any interest or fees, and the payments stay consistent, which prevents the “sticker shock” that often plagues home renovation budgets mid-project. It is particularly useful when purchasing materials from online flooring retailers where you can’t physically see the texture until it arrives.
Pros:
- No hidden fees or unexpected costs
- Instant decisions during the checkout process
- Transparent interest rates shown upfront
Cons:
- Best suited for smaller, retail-based purchases rather than large-scale construction
5. World of Floors
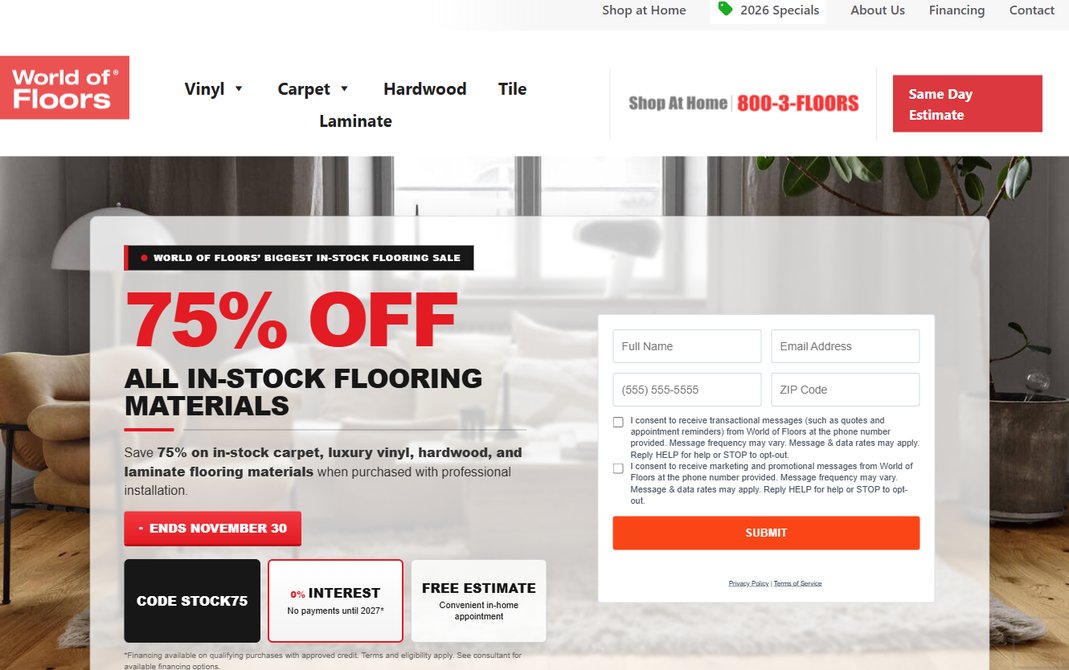
World of Floors offers a more direct, localized experience, especially for those in the Michigan area. They combine the product and the financing into one seamless experience, often including professional installation as part of the package. This removes the headache of having to source a separate contractor and then try to find a loan to pay them separately.
They are particularly attractive for those looking for aggressive promotional deals. With options like 0% interest and no payments until 2027 on certain qualifying purchases, they provide a way to get your floors replaced now while delaying the financial impact. This can be a massive advantage for families who are currently saving for other major expenses like education or a down payment on a second property.
Pros:
- Potential for 0% interest promotional periods
- Offers professional installation alongside financing
- Significant savings on in-stock materials
Cons:
- Financing is subject to approved credit and specific qualifying terms
How to Choose Your Flooring Loan
Before you sign anything, you must determine the scale of your project. If you are replacing the flooring in a single bedroom, a “Buy Now, Pay Later” service like Affirm might be the simplest path. However, if you are gutting an entire house, including subfloor replacement, stairs, and baseboards, you will likely need a more substantial loan structure from a provider like Acorn Finance. A single-room solution will simply not cover the logistical costs of a full-house renovation.
Watch out for the “hidden” costs of borrowing. Always ask if there are dealer fees being added to your quote by the contractor to cover the cost of the financing. It is common for some contractors to add a 3-5% surcharge to the total price if you choose a specific financing option, effectively making the “interest-free” loan quite expensive. Additionally, verify whether a credit inquiry will be a “soft pull” or a “hard pull.” A soft pull allows you to shop around for the best rate without damaging your credit score, while a hard pull is typically required once you move to the final signing phase.
Finally, never borrow more than the project’s estimated cost. It is easy to get swept up in the excitement of high-end materials, like wide-plank engineered oak or natural stone, but an overextended loan can turn a beautiful renovation into a long-term financial headache. Always include a 10-15% buffer in your budget for unexpected subfloor issues, uneven joists, or installation surprises that only become visible once the old carpet is ripped up. If your budget is $10,000, try to secure financing for $11,500 to ensure you aren’t left with half-finished floors due to a lack of funds.