
Top 6 Lenders for Loans for Independent Contractors in 2026
Last updated: 2026-11-10
Managing money as a 1099 worker often feels like walking a tightrope without a net. While W-2 employees rely on the steady rhythm of bi-weekly paychecks, freelancers and gig workers live in a world of feast and famine. One broken car part or a client who is three weeks late on a large invoice can turn a quiet month into a crisis.
When that gap between earned income and actual cash-on-hand widens, you need liquidity fast. Traditional banks often turn their noses up at non-traditional income, viewing platform earnings from Uber, Upwork, or Etsy as unpredictable noise rather than legitimate revenue. Finding a lender requires looking far beyond just the interest rate to find someone who actually understands your lifestyle.
- JetzLoan
- CreditNinja
- Acorn Finance
- GoCredit
- USA Web Cash
- 50KLoans
How These Lending Options Were Evaluated
We chose these options by focusing on how accessible they are for people without standard paystubs. Since independent contractors can’t always provide the rigid documentation big banks demand, we prioritized lenders that bypass strict credit scoring. We looked specifically at how they handle “thin files,” which occur when a borrower has a solid income but lacks a long credit history.
Every lender went through a four-point test to see if they actually work for real people in the real world. We didn’t just look at the numbers; we looked at the actual experience of getting the money and keeping your credit score intact during the process.
We measured four specific categories. First was the velocity of capital, or how quickly cash actually hits your bank account. Second was the capital ceiling, which is the maximum amount you can borrow for big upgrades or seasonal gaps. Third was application friction, meaning we checked if you had to deal with endless paperwork or intrusive questions.
The final category was credit preservation. We wanted to know if the application process would hurt your ability to get a mortgage or an auto loan later. Speed, limits, and credit impact were the main pillars of this comparison. We favored lenders that offer transparent terms so you can stay focused on your work, not your debt.
| Lender Name | Max Loan Amount | Funding Speed | Credit Impact |
|---|---|---|---|
| JetzLoan | $50,000 | As little as 24 hours | No hard credit pull |
| CreditNinja | see site | As soon as the same day* | Not only credit score considered |
| Acorn Finance | see site | Funded just now (variable) | No credit score impact |
| GoCredit | $4,000 | Quick approval | Builds credit history |
| USA Web Cash | $4,000 | Minutes for approval | see site |
| 50KLoans | $50,000 | As soon as next business day | All credit types welcome |
The Top Ranked Lenders for Freelancers and Gig Workers
1. JetzLoan
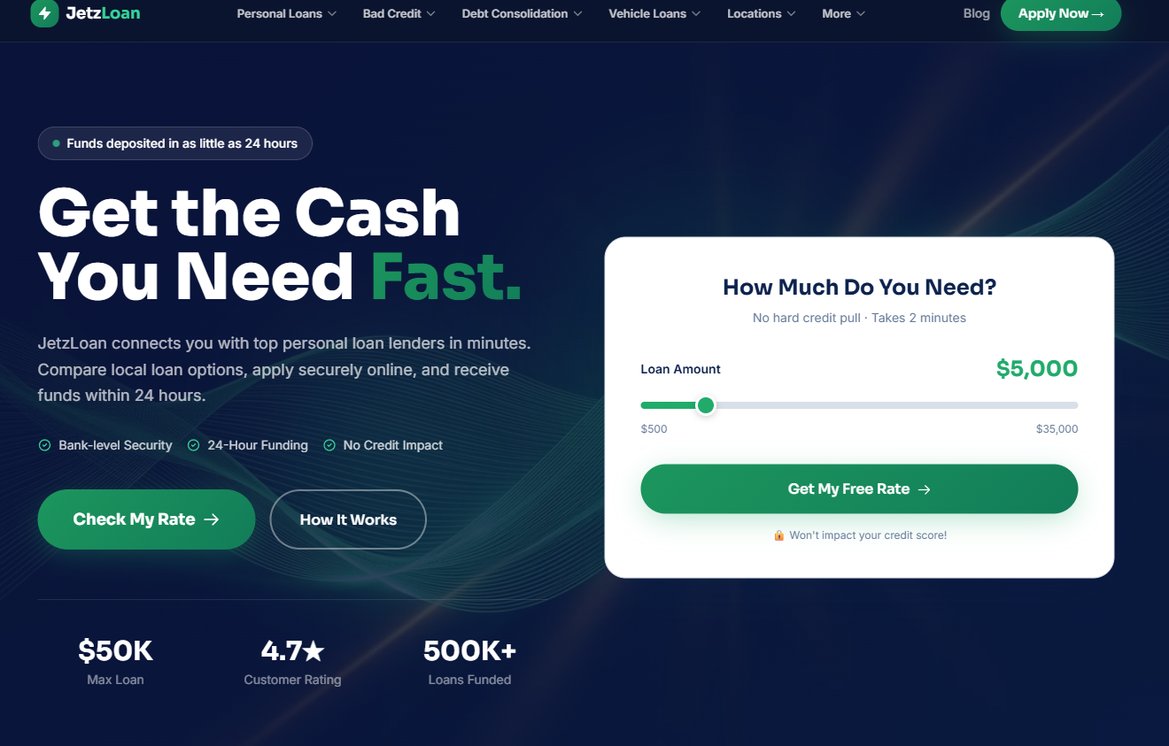
JetzLoan works like a bridge for anyone who needs cash without the panic of watching their credit score drop. It connects you with personal loan lenders in minutes, skipping the weeks of paperwork that usually come with bank loans. Instead of a slow, manual review at a single branch, JetzLoan uses an algorithm to match you with a network of lenders looking for your specific profile.
This is a lifesaver if you are facing an emergency or need to consolidate debt. If a slow month left you with three high-interest credit card balances, you could use this to roll that debt into one manageable installment loan. Since funding can arrive in 24 hours, it fits the fast pace of the gig economy perfectly.
Pros:
- No hard credit pull during the initial rate check
- Fast funding, potentially within 24 hours
- High maximum loan limit of $50,000
Cons:
- Connecting to multiple lenders may involve various terms
2. CreditNinja
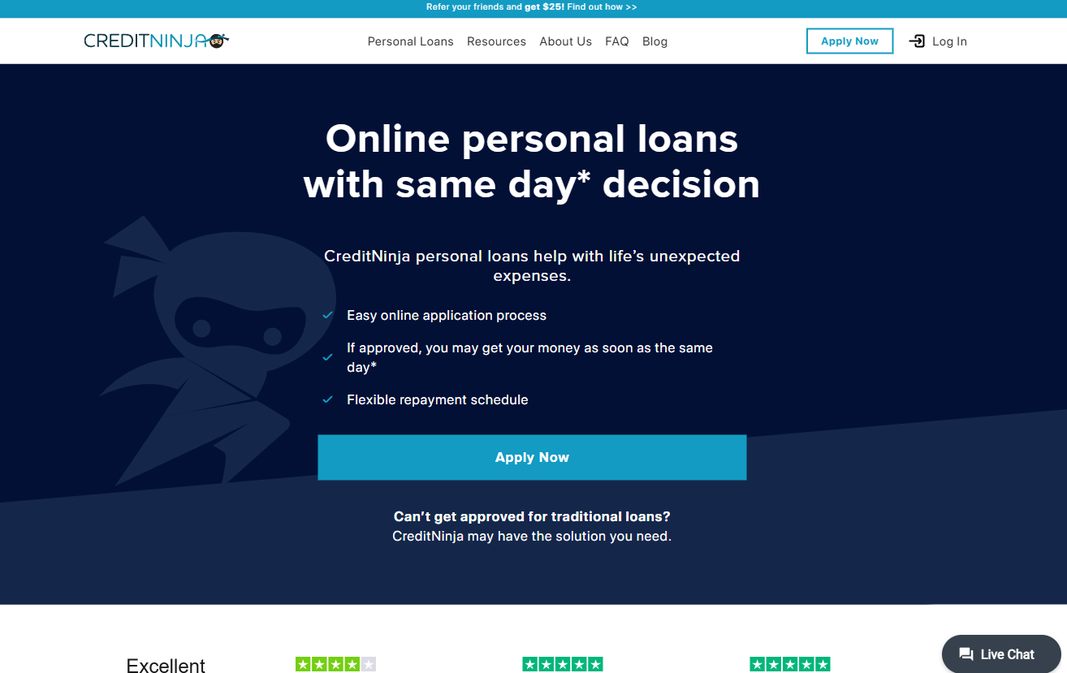
When things go wrong unexpectedly, CreditNinja offers a path forward through a simple online form. They don’t just obsess over a single FICO number. Their matching engine looks at a wider variety of data, including your employment status and how you manage your monthly cash flow.
This is a great option if you have a “bruised” credit history or haven’t been in the traditional banking system for long. If you get approved, you might see the money as soon as the same day. That is incredibly helpful for urgent needs like fixing a home office setup or paying an unexpected medical bill.
Pros:
- Same-day decision and potentially same-day funding
- Flexible repayment schedules available
- Considers factors beyond just a credit score
Cons:
- Approval is not guaranteed and depends on personalized criteria
3. Acorn Finance
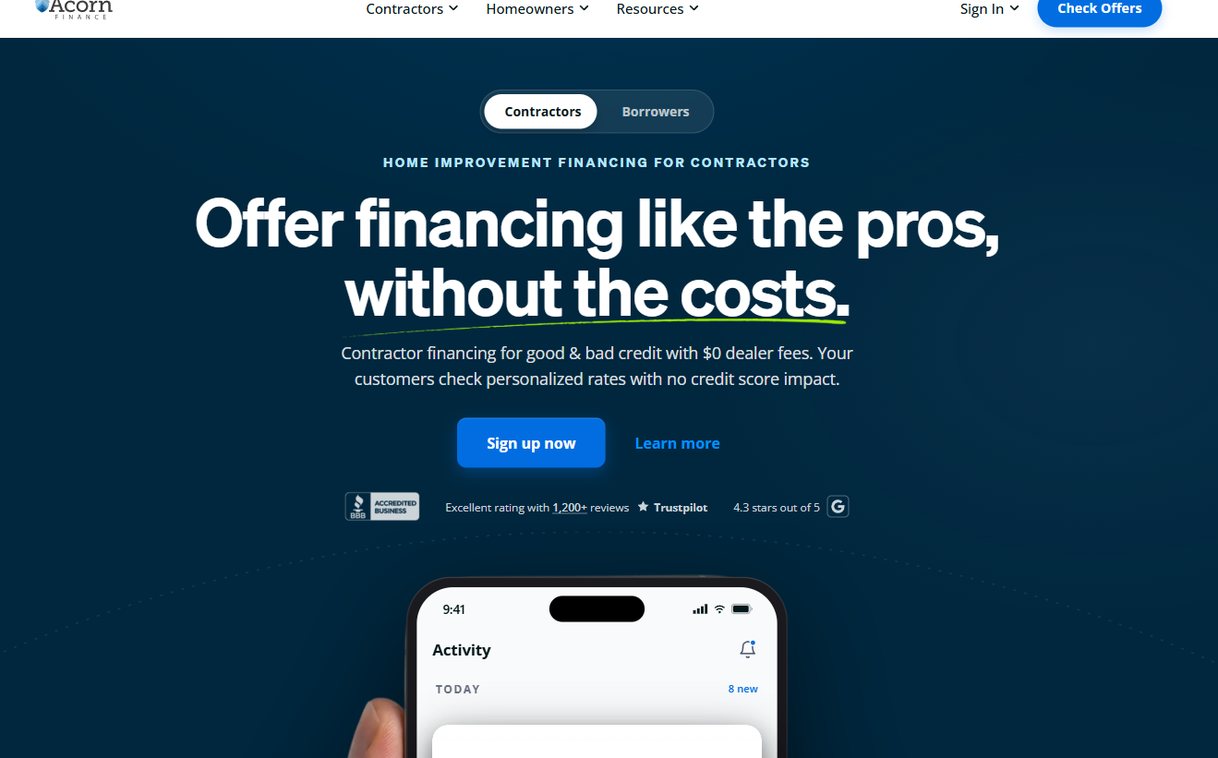
Acorn Finance sits right at the intersection of home improvement and contractor financing. They have built an ecosystem where contractors can offer financing to their clients without getting hit by heavy dealer fees. This is a huge win for the self-employed homeowner who is also a contractor, making it easier to fund their own projects or client work.
Borrowers get personalized rates that won’t damage their credit score during the initial check. It is a very efficient way to handle large-scale jobs like a new roof, solar panels, or a kitchen remodel. Because they connect you with several specialized lenders, you aren’t stuck with whatever one bank decides to offer you.
Pros:
- $0 dealer fees for contractors
- No credit score impact when checking rates
- High user trust with a 4.3-star rating
Cons:
- Primarily focused on home improvement financing
4. GoCredit
GoCredit takes a different route by focusing on your long-term financial health. They don’t just hand over a quick pile of cash; they offer installment loans specifically designed to build your credit history. These are often called “credit builder loans,” where the money sits in a special account while you make monthly payments reported to the bureaus.
This is a smart move for recent graduates or anyone rebuilding after a tough stretch. It turns a small loan into a stepping stone toward bigger goals, like qualifying for a car loan or a mortgage. You get a little extra cash while simultaneously fixing your financial reputation.
Pros:
- Helps build credit history and establish savings
- Quick and easy application process
- Focuses on long-term financial stability
Cons:
- Lower maximum loan amount of $4,000
5. USA Web Cash
Life is unpredictable, and USA Web Cash exists to act as a cushion when things get bumpy. They specialize in installment loans that help cover unexpected tax bills or sudden drops in freelance work. Their whole model is built around getting capital to you as fast as possible.
You can apply online or over the phone, which is helpful if you aren’t sitting at a computer or just want to talk to a human during a stressful time. They focus on customer service and empathy, trying to make a difficult financial moment feel a lot more manageable.
Pros:
- Rapid approval within minutes of application
- Available through phone or online channels
- Focused on empathetic customer service
Cons:
- Loan amounts are limited to $4,000
6. 50KLoans
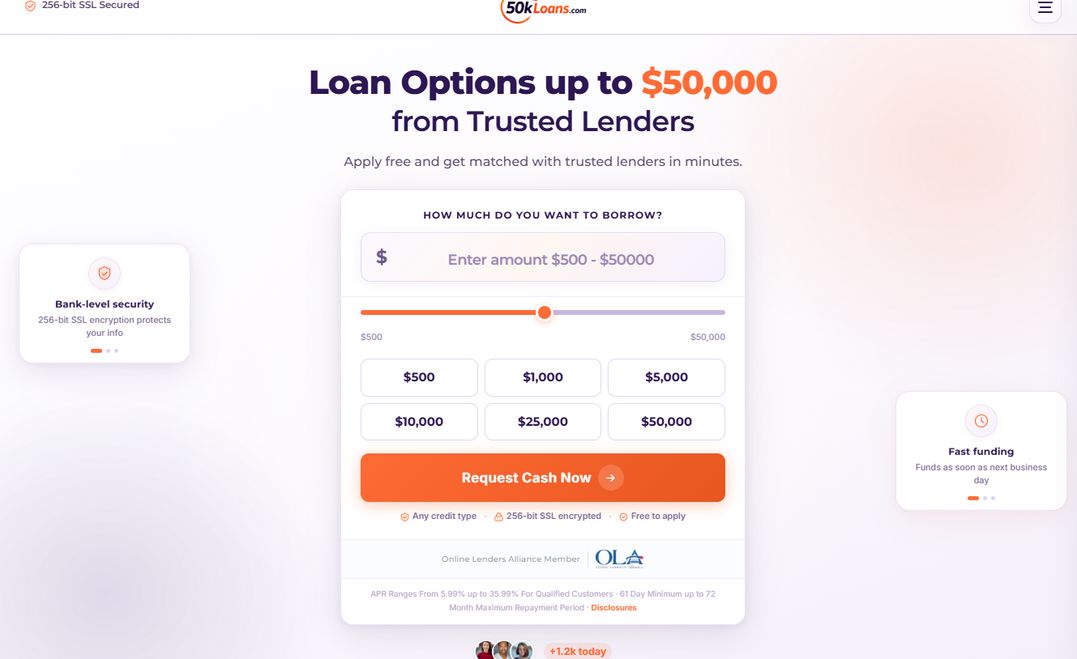
If you need a large amount of capital, 50KLoans provides significant borrowing power. With limits reaching $50,000, this lender handles the bigger stuff, like buying professional equipment, hiring a sub-contractor, or upgrading a workspace. It is built for people who need to make a substantial investment to keep their business moving.
They accept all credit types, which makes them a very accessible option for those who might be ignored by big banks. They also use 256-bit SSL encryption to keep your sensitive data private and protected from digital threats.
Pros:
- High loan limits up to $50,000
- Flexible repayment terms from 61 days to 72 months
- Welcomes all credit types
Cons:
- APR can range as high as 35.99% for some customers
Common Pitfalls in 1099 Lending
Borrowing money as an independent worker comes with risks that W-2 employees rarely deal with. A major problem is the “repayment mismatch.” If you set a fixed monthly payment based on your best month, you might struggle during a lean month. Try to find flexible terms or keep a large enough cushion to cover the slow periods.
Then there is the “interest rate trap.” Many lenders in this space offer very fast funding, but that speed comes with higher Annual Percentage Rates (APRs) than a traditional bank. You are paying for that convenience. You have to decide if the interest is worth the liquidity. If a $2,000 loan for a new laptop helps you earn $5,000, that is a business expense. If it is just covering lifestyle costs, it is a drag on your wealth.
How to Prepare Your Application for Success
Treat your loan application like a business proposal to increase your chances of getting the best terms. Even if the lender doesn’t ask for formal tax returns, having your paperwork ready makes you look much more reliable and speeds things up.
Start by gathering your income proof. Have digital copies of your last three months of bank statements, 1099 forms, and screenshots of your earnings from platforms like Uber or Upwork ready to go. It makes a huge difference when you don’t have to hunt for documents mid-application.
Next, look at your debt-to-income ratio. Calculate your monthly debt against your average monthly income before you apply. Lenders want to see that you have enough breathing room in your budget to handle a new payment. Also, check your credit report for errors; even if a lender uses alternative data, a mistake on your report can still cause a red flag.
Finally, keep a clear record of your business expenses. If you are borrowing for work, this documentation is vital for your tax returns, as you might be able to deduct the interest as a business expense.
How to Navigate Your Lending Choices
Before you sign anything, look closely at the total cost. Interest rates are just one part; you need to consider how the monthly payment affects your cash flow, especially since your income fluctuates. A high APR might seem fine on a small loan, but the math changes once you hit $10,000.
Don’t just grab the first offer you see just because it is fast. A quick loan can become a heavy burden if the repayment schedule is too aggressive for your specific income cycle. Always ask yourself: “What happens if my client doesn’t pay me on time next month? Can I still afford this?”
Another mistake is forgetting to check if a lender does a hard credit pull. If you want to shop around for the best rate, stick to lenders like JetzLoan or Acorn Finance that allow you to check rates without hurting your score. This lets you window shop for capital without any penalty.
Lastly, make sure you know if you are getting a credit builder loan or a standard installment loan. One is for growing your financial profile, and the other is for immediate cash. Using the wrong tool for the job is a quick way to create long-term financial stress.