
Best Lenders for No Credit Check Home Improvement Loans in 2026
Last updated: 2026-11-10
Homeowners often find themselves staring at a leaking roof or a dated kitchen, wishing they could fix it instantly. The dream of a perfect remodel often hits a brick wall when the bank starts asking about credit scores. Finding a way to fund these projects without a massive impact on your financial profile is a common goal.
Whether it is an urgent structural repair that cannot wait, such as a cracked foundation, or an aesthetic upgrade like installing granite countertops, the method of financing can determine whether the project moves forward or sits in the “someday” category indefinitely. Sometimes, the delay isn’t the contractor, but the paperwork.
When searching for a way to renovate, the most important factors are speed, total loan amount, and how much the application process actually costs. Some lenders offer a soft pull to check rates, while others might require a full credit assessment later. Navigating these options requires a clear eye on the fine print and the actual cost of borrowing.
It is essential to distinguish between personal loans, which are typically unsecured, and home equity-based products, which use your property as a guarantee. This distinction dictates your risk level and your interest rate structure. Knowing which one you need before you walk into a bank can save you a lot of grief.
- PNC Bank
- JetzLoan
- Tower Loan
- Credit Union West
- BOK Financial
How These Home Improvement Funding Options Were Evaluated
The evaluation focused on lenders providing unsecured options or those offering “no impact” credit checks. This distinction is vital because a hard credit pull can temporarily dip a score, making it harder to refinance later. We looked for providers that allow users to see their potential terms without any immediate penalty to their standing.
We also scrutinized the “transparency factor”—how clearly a lender communicates its fee structure before you commit to a formal application. There is nothing worse than finding out there is a massive origination fee only after you have signed the dotted line. Transparency is the name of the game.
Speed of funding and the maximum amount available were also weighed heavily. A renovation project rarely waits for a month-long approval process. For instance, if a contractor requires a deposit to secure a window replacement, a three-week waiting period for a loan can cause you to lose your spot on the schedule.
Therefore, lenders that can move from application to cash within a few days received higher consideration in this specific ranking of specialized financing providers. We also analyzed the “use of funds” restrictions. Some lenders are highly restrictive, only allowing the money for specific home improvements, while others provide “blank check” personal loans that allow you to pay contractors directly or purchase materials yourself. This flexibility is a major deciding factor for DIY enthusiasts versus those hiring full-service firms.
| Lender Name | Max Loan Amount | Funding Speed | Credit Check Type |
|---|---|---|---|
| PNC Bank | $35,000 | see site | see site |
| JetzLoan | $50,000 | Within 24 hours | No hard credit pull |
| Tower Loan | see site | see site | see site |
| Credit Union West | see site | see site | see site |
| BOK Financial | see site | see site | see site |
Top Ranked Lenders for Your Next Project
1. PNC Bank
PNC Bank offers unsecured personal loans specifically designed for those looking to renovate or remodel their living spaces. These loans do not require any collateral, meaning your home is not at risk if you run into financial trouble. It is a straightforward approach for people who want to avoid the complexities of equity-based borrowing.
When you choose an unsecured route, you bypass the lengthy appraisal process required for mortgage-based products, which can save weeks of waiting. This option is ideal for homeowners who need a significant sum, up to $35,000, to tackle substantial upgrades. Because they are unsecured, the application process is generally smoother than a mortgage-backed loan.
It is a reliable choice for those who have a clear project in mind and need a traditional banking structure. For example, if you are looking to replace old flooring or upgrade your bathroom vanity, a $35,000 limit provides ample headroom for high-quality materials and labor.
Pros:
- Unsecured with no collateral required
- Loan amounts up to $35,000
- Available for various renovation projects
Cons:
- Not specifically marketed as a “no credit check” option
2. JetzLoan
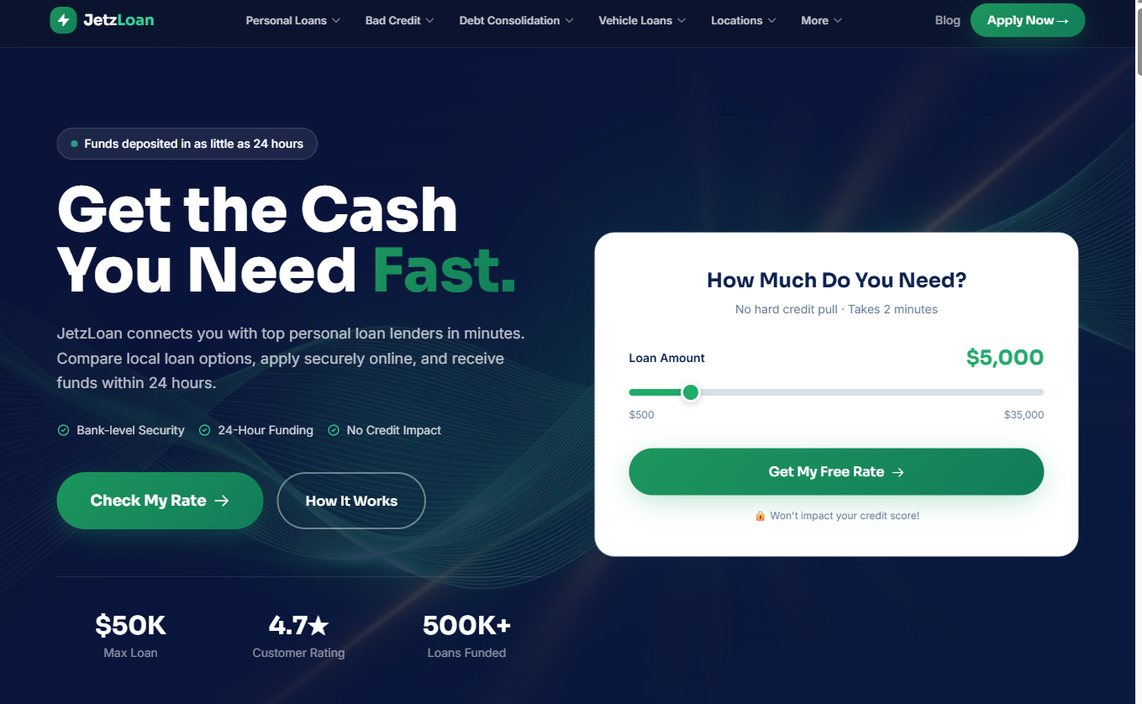
JetzLoan acts as a fast-moving bridge for those who need cash in a heartbeat. They connect borrowers with various personal loan lenders in just a few minutes. This is a high-speed solution for the homeowner who needs to buy materials before a contractor starts the work next week.
Instead of applying to one bank and waiting for a manual review, JetzLoan‘s digital interface streamlines the matching process, making it highly efficient for time-sensitive repairs. The standout feature here is the speed of funding, with money potentially hitting an account in as little as 24 hours.
They offer a way to check rates that won’t impact a credit score, which is a massive relief for those feeling nervous about their standing. This “pre-qualification” stage allows you to shop around for the best interest rate without the fear of seeing a sudden drop in your credit report. It is a modern, digital-first experience for urgent needs like emergency plumbing or roofing repairs.
Pros:
- Funds deposited in as little as 24 hours
- No hard credit pull to check rates
- High maximum loan amount of $50,000
Cons:
- Acts as a connector rather than the sole lender
3. Tower Loan
Tower Loan provides a wide variety of installment and personal loans that can be tailored to specific needs like home improvement. They are well-known for catering to a broad spectrum of borrowers, including those who might have concerns about their credit history. This makes them a frequent stop for people needing a second look when traditional banks might have issued a denial.
They understand that life events—like medical bills or temporary job gaps—can impact a credit score, and they provide alternatives. Their product list is extensive, covering everything from emergency loans to auto-secured options. This versatility means you can find a product that matches your specific situation, whether you are fixing a leak or remodeling a whole floor.
Because they offer various installment structures, you can often customize your repayment schedule to better fit your monthly budget, providing more breathing room in your cash flow. This flexibility can be a lifesaver when your income fluctuates throughout the year.
Pros:
- Wide variety of specialized loan types
- Covers many different states
- Options for those with bad credit concerns
Cons:
- Terms and rates are not explicitly listed for all products
4. Credit Union West
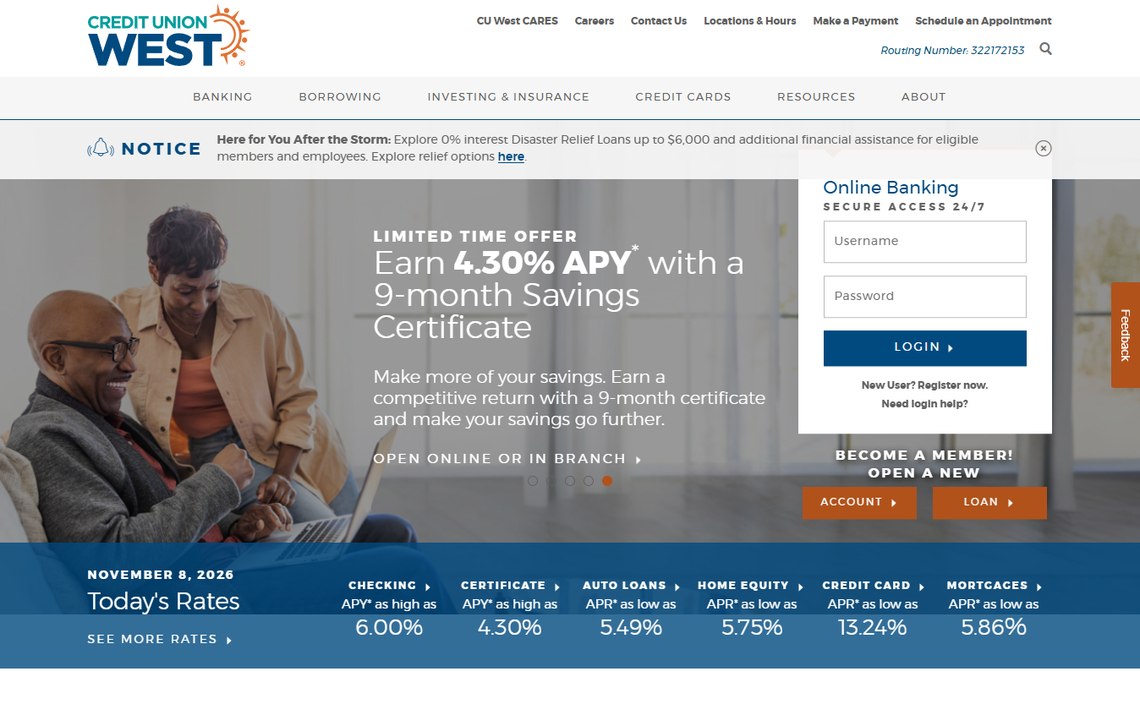
Credit Union West offers a community-focused approach to borrowing, which often feels more personal than dealing with giant national banks. They provide specialized assistance, such as disaster relief loans for members facing unexpected storms or natural calamities. This makes them a great choice for homeowners in specific regions like Arizona, where sudden weather events can cause immediate, costly damage to a property.
Their products are designed to help members navigate difficult times, offering relief options that might not be available at a standard commercial bank. It is a solid option for those who prefer the member-owned model of a credit union. Because credit unions are non-profit entities, they often return value to their members through better interest rates or lower fees.
They focus heavily on being there for the customer when life gets messy, treating you as a member rather than just an account number. This localized approach often results in a much more empathetic service experience during stressful times.
Pros:
- Disaster relief loan options available
- Member-focused service model
- Potential for 0% interest relief loans
Cons:
- Membership requirements may apply
5. BOK Financial
BOK Financial provides a more sophisticated suite of tools, including Home Equity Lines of Credit (HELOCs). These can be a powerful way to fund major renovations by tapping into the value you have already built in your property. Unlike a lump-sum personal loan, a HELOC works much like a credit card attached to your home’s equity.
You only draw what you need, when you need it, making it incredibly efficient for phased renovations where you might do the kitchen this year and the master bath next year. They offer competitive rates, such as a 6-month introductory APR on HELOCs, which can make the initial stages of a renovation very affordable.
This is a great choice for the strategic homeowner who wants to manage their cash flow over a longer period. While it requires more paperwork—including a home appraisal—and carries the risk of using your home as collateral, the interest rates are typically significantly lower than unsecured personal loans.
Pros:
- Competitive HELOC rates
- FDIC-insured and highly secure
- Diverse range of home and personal products
Cons:
- HELOCs require home equity as collateral
Comparing Unsecured vs. Secured Financing
When deciding between a personal loan (unsecured) and a HELOC (secured), you must weigh the trade-off between convenience and cost. Secured loans are essentially “cheaper” because the lender has the safety net of your house, which lowers their risk and, consequently, your interest rate. However, the stakes are much higher; if you cannot make the payments, the lender can foreclose on your home.
Unsecured loans, like those offered by PNC or JetzLoan, offer a “cleaner” break. If you hit a financial rough patch, your home is safe. The trade-off is a higher interest rate and a lower maximum loan amount. This makes unsecured loans the superior choice for smaller, mid-range projects (under $50,000) or for homeowners who do not have significant equity built up yet.
For massive structural additions or whole-house remodels, the secured route is usually the more economical long-term decision. It is a balance of risk and reward that every borrower must face before signing any papers.
| Feature | Unsecured Personal Loan | HELOC (Secured) |
|---|---|---|
| Interest Rates | Generally Higher | Generally Lower |
| Collateral Required | No | Yes (Your Home) |
| Approval Speed | Very Fast (Days) | Slower (Weeks/Months) |
| Risk Level | Lower (Property is safe) | Higher (Property is at risk) |
Navigating the Lending Landscape
Selecting the right lender is not just about finding the lowest number on a screen. It is about matching the loan’s structure to the actual timeline of your renovation. If you need a kitchen remodel next month, a 24-hour funding option is your best friend. If you are planning a massive addition, a HELOC might be smarter.
Consider the “phasing” of your work; if you are doing a renovation in stages, a revolving line of credit is far more efficient than taking out one large loan and paying interest on money you aren’t using yet. You don’t want to pay for a pile of lumber that’s sitting in your driveway for six months.
One common mistake is ignoring the total cost of borrowing in favor of a low monthly payment. A lender might offer a 10-year term that makes your monthly payment look small, but the cumulative interest paid over that decade could end up costing you more than the actual renovation itself. Always look at the total amount you will pay back over the life of the loan.
Additionally, always ensure you understand the difference between a soft pull and a hard pull. Protecting your credit score should be a top priority during the research phase, as a sudden drop in your score during the application process could disqualify you from the very rates you were targeting. Don’t let a quick search ruin your long-term borrowing power.