
The 6 Best Subprime Personal Loans for 2026: A Detailed Ranking
Last updated: 2026-11-10
Trying to manage credit when your score is struggling feels like walking through a thick fog. Finding a lender that won’t slam the door shut is a massive challenge for many. You might find yourself staring at a mounting pile of bills, wondering if your next paycheck will actually cover the gap. This financial anxiety often forces people into a survival mode where the only goal is keeping the lights on or the car running, even if it hurts long-term stability.
This ranking looks at lenders that cater to the subprime category. These options are meant for people needing quick cash for emergencies, like a sudden car repair, medical bills, or unexpected household maintenance. Choosing a partner requires looking past the surface to see actual speed, total cost, and repayment flexibility. You shouldn’t just look for money; you need money that fits the specific rhythm of your cash flow.
- 1F Cash Advance
- SoFi
- FastLendGo
- OneMain Financial
- InstaLoan
- Wisetack
How These Subprime Lenders Were Evaluated
Our evaluation prioritized accessibility and speed for those with less-than-perfect credit. A lender’s ability to provide funds quickly, sometimes within the same day, is a critical metric for someone facing an immediate crisis. Speed often dictates whether a borrower can avoid late fees, prevent utility shut-offs, or sidestep a missed rent payment that could trigger an eviction notice. We analyzed how quickly a user could move from “application submitted” to “funds in bank account.”
We also weighed the diversity of loan products heavily. A lender that offers everything from small payday products for short-term gaps to larger installment loans provides more utility to a varied audience. A single-product lender might help you today but leave you stranded when a larger expense arises. We looked for transparency regarding loan amounts, funding timelines, and specific borrower needs. We favored lenders that clearly state their requirements instead of hiding terms behind a “get a quote” button that leads to endless marketing calls.
| Lender Name | Loan Amounts | Repayment Terms | Funding Speed | Credit Requirement |
|---|---|---|---|---|
| 1F Cash Advance | See site | Short-term | Same day | No credit check |
| SoFi | See site | See site | Same day | See site |
| FastLendGo | $500 – $5,000 | See site | See site | See site |
| OneMain Financial | $1,500 – $35,000 | 24 – 60 months | As fast as 1 hour | See site |
| InstaLoan | See site | See site | Same day | See site |
| Wisetack | See site | Monthly payments | See site | See site |
Top Rated Subprime Financing Options
1. 1F Cash Advance
Finding yourself in a tight financial spot is incredibly stressful. Whether it is an unexpected car repair or a utility payment, having access to quick funds is often a necessity. This lender specializes in helping individuals bridge the gap between paychecks. Their model is built around the reality that life happens in the middle of a pay cycle, and you simply cannot wait until Friday to fix a leaking pipe.
The most common product is the payday loan, which you repay when you receive your next paycheck. These are ideal for minor emergencies where you just need a small boost to keep things running until the next deposit arrives. Because they focus on short-term liquidity, the application is usually streamlined to minimize the time spent on paperwork.
Pros:
- Offers same-day loans with instant approval.
- No credit check required for certain products.
- Designed specifically for those with poor credit.
Cons:
- Short-term nature requires a quick repayment plan.
- The high velocity of repayment can create a “treadmill effect” if not managed carefully.
2. SoFi
SoFi operates as a comprehensive financial ecosystem, offering everything from banking to investments. While they are a major player, they are known for providing money quickly when you are in a pinch. They are a powerhouse in the modern digital lending world, utilizing sophisticated algorithms to assess risk without the need for traditional, slow-moving manual reviews.
If you need money as soon as possible, this is a strong contender to investigate. The lender has a reputation for speed, often approving and funding loans within the same day, making them a reliable choice for urgent needs. Because they are a full-service financial institution, their digital interface is often much smoother and more intuitive than specialized lenders who focus solely on high-interest products.
Pros:
- Extremely fast funding, potentially same-day.
- Broad suite of financial services available.
- Highly efficient digital application process.
Cons:
- May have stricter requirements than specialized payday lenders.
- Generally requires a better credit profile than the “no credit check” alternatives.
3. FastLendGo
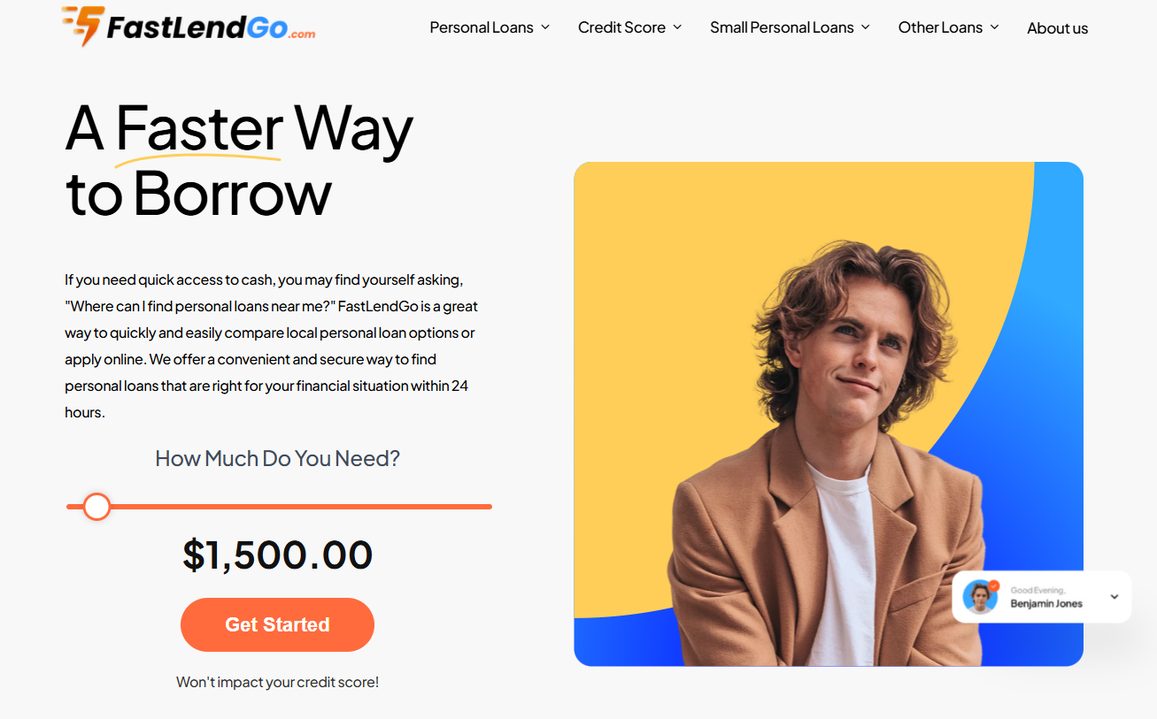
FastLendGo acts as a versatile partner for various personal financing solutions. They cater to a wide spectrum of needs, ranging from small $500 loans to larger $5,000 personal loans. It is a flexible option for those who aren’t sure exactly how much they need, as they allow you to scale your request based on the immediate crisis at hand. (fastlendgo.com)
The platform is particularly useful for comparing local options online. They offer specialized financing for specific needs, such as auto repairs, motorcycle loans, or even dental and roof financing, making them a niche but powerful tool. This specialization is vital; borrowing $1,000 for a car repair is a very different financial decision than borrowing $1,000 for general debt consolidation.
Pros:
- Wide range of loan amounts from $500 to $5,000.
- Specialized loans for specific emergencies like auto repair.
- Options for various credit tiers.
Cons:
- The variety of options might be overwhelming for some.
- Requires careful selection to ensure you aren’t over-borrowing.
4. OneMain Financial
OneMain Financial is a heavy hitter when it comes to larger sums of money. They offer personal loans ranging from $1,500 up to $35,000, which is significant for someone needing to consolidate debt or handle a major life event like a medical emergency or home repair. Their rates start at 11.99% APR, which is quite competitive for the subprime market.
They provide a human touch that many digital-only lenders lack. With over 1,300 branches, you can speak to a real person if you run into trouble. This is particularly important for subprime borrowers who may have complex financial histories that a computer algorithm might struggle to interpret. Funding can be incredibly fast, sometimes occurring just one hour after the loan is signed, especially when utilizing their branch network.
Pros:
- High loan amounts up to $35,000.
- Very fast funding, potentially within one hour.
- Access to physical branches for in-person help.
Cons:
- Terms and rates may vary significantly based on credit.
- The application process can be more intensive than “instant” online lenders.
5. InstaLoan
When the clock is ticking, InstaLoan focuses on title-secured loans to get you cash quickly. Their primary goal is to provide funds the same day you are approved. This is a lifeline for those who have assets—specifically a vehicle—and need immediate liquidity to prevent a catastrophe.
They have been a trusted lender since 2011, which provides a sense of stability in a market often filled with fly-by-night operations. They emphasize that you are more than just a credit score, attempting to look at your overall ability to repay the debt, including your vehicle’s equity and your income stability.
Pros:
- Same-day funding upon approval.
- Long-standing reputation in the industry.
- Focuses on factors beyond just the FICO score.
Cons:
- Title-secured loans involve using assets as collateral.
- Risk of losing your vehicle if you default on the loan.
6. Wisetack
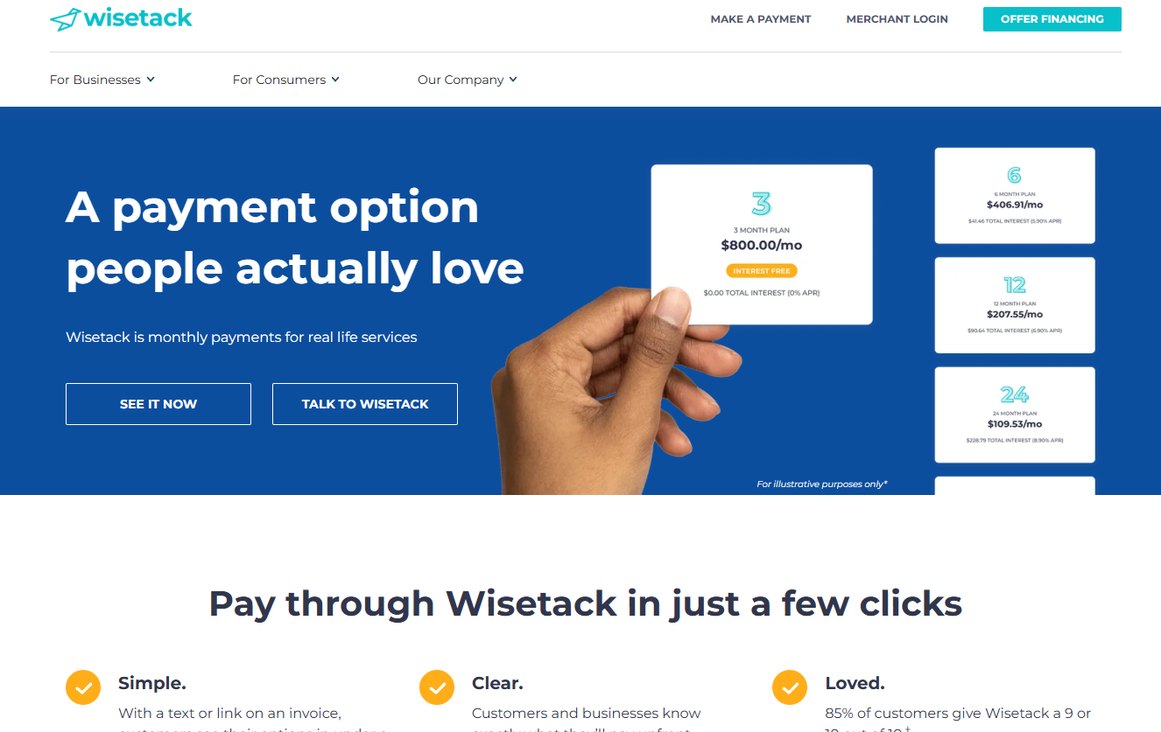
Wisetack takes a different approach by focusing on customer financing for home service businesses. Instead of you going to them, you often encounter them through a text or link on an invoice from a professional you have hired. This “point-of-sale” financing is becoming the standard for high-ticket service industries.
It is a seamless experience that allows customers to see their options in under a minute. This makes it a fantastic option for financing sudden home repairs like plumbing, electrical work, or HVAC replacement through a trusted contractor. Because the lender works directly with the merchant, the connection between the debt and the service provided is very clear.
Pros:
- Extremely easy to use via text or invoice link.
- High customer satisfaction ratings.
- Transparent upfront costs for both parties.
Cons:
- Only available through participating merchants.
- You cannot apply for Wisetack independently for general cash needs.
Understanding the Cost of Subprime Borrowing
To make an informed decision, you must understand the difference between Annual Percentage Rate (APR) and a simple monthly interest rate. In the subprime market, lenders often highlight the monthly interest rate because it sounds much smaller. For example, a 5% monthly rate might sound manageable, but when calculated annually, that is 60% APR. Always ask for the APR to understand the true cost of the debt over the life of the loan.
There are several types of fees that can sneak into your loan agreement:
- Origination Fees: A fee charged by the lender for processing the loan, often deducted directly from the principal.
- Prepayment Penalties: Fees charged if you try to pay off the loan early. This is a major red flag if you plan to use a tax refund to clear your debt.
- Late Fees: Charges applied if a payment is missed, which can quickly compound and lead to a cycle of debt.
Steps to Secure the Best Terms in a Tight Spot
If you find yourself needing to borrow quickly, following these steps can help you secure more favorable terms and avoid common pitfalls:
- Determine your exact amount: Do not borrow “as much as possible.” Borrow exactly what you need to cover the specific emergency. Borrowing extra to cover other debts is a common mistake that leads to over-extension.
- Verify the lender’s legitimacy: Check reviews on third-party sites and ensure the lender is licensed to operate in your specific state.
- Prepare your documentation: To speed up the process, have your recent pay stubs, utility bills (for proof of residence), and identification ready to upload immediately.
- Read the repayment schedule: Look specifically at the “Total of Payments” figure. This tells you exactly how much you will have paid back by the end of the term, including all interest.
- Set up autopay: Once the loan is secured, set up automatic payments if possible. This ensures you never face a late fee due to a simple oversight.
Navigating Your Borrowing Choices
Choosing a lender is not a one-size-fits-all endeavor. Before you sign any paperwork, you must determine if you need a small, quick bridge to the next payday or a large, long-term installment loan. A mistake in this stage can lead to a cycle of debt that is difficult to escape. If your emergency is a $300 car repair, a long-term installment loan with a 24-month term is likely an unwise choice due to the excessive interest accrued over time.
One common pitfall is ignoring the fine print regarding interest rates and fees. Subprime loans often carry higher costs because the lender is taking a greater risk. Always ensure you have a clear plan to repay the principal and interest before you commit to the terms. If you cannot see a way to pay the loan back using your current income, you should look for alternative assistance, such as local community programs or non-profit credit counseling.
Another mistake to avoid is rushing the application process. While speed is vital, taking ten extra minutes to understand the repayment schedule can save you hundreds of dollars in the long run. Always compare the total cost of the loan, not just the monthly payment. A lower monthly payment often means a longer term, which significantly increases the total amount of interest you will pay over the life of the debt.