
The 6 Best Lenders for Bad Credit Loans in Iowa: 2026 Rankings
Last updated: 2026-11-10
Trying to manage money in Iowa can feel like driving through a heavy cornfield fog without any headlights. When your credit score takes a hit, finding a lender that won’t turn you away requires more than a quick Google search. You need to know exactly who is actually providing the funds to bridge your gap.
Maybe you are dealing with a sudden car repair in Des Moines or an unexpected medical bill in Cedar Rapids. Perhaps it is just a seasonal gap in cash flow in a rural county. The options available to you vary significantly in terms of cost, speed, and the long-term impact on your wallet.
Picking the right match involves more than just staring at an interest rate. You have to understand how fast the money arrives, what the minimum requirements are, and if the terms actually fit your monthly budget. A lender offering a 24-hour turnaround might charge a much higher Annual Percentage Rate (APR) than a traditional bank that takes two weeks to process an application.
This list highlights the most reliable options for Iowans facing credit hurdles this year. We have categorized them to help you match your specific financial situation with the most appropriate tool.
- Addition Financial
- GreendayOnline
- FastLendGo
- PaydayChampion
- Mariner Finance
- Lendersa
How These Iowa Lenders Were Evaluated
We picked the top candidates by looking at specific services and how accessible they are for people with imperfect credit histories. Every option was vetted based on the loan amounts offered and the speed of the application. We also looked at the specific types of credit profiles they are willing to accept from applicants.
We didn’t just look for who says “yes.” We looked at how they say “yes” and what the subsequent cost of that agreement looks like for the borrower. Our goal was to provide a clear snapshot of the market.
We checked whether a lender specializes in small, short-term emergency cash or larger, more structured personal loans. This ensures that an Iowan looking for a quick $500 fix sees different results than someone seeking a $20,000 debt consolidation tool. We evaluated the digital experience—specifically, how many steps are required from the moment you click “apply” to the moment funds hit your bank account—as well as the transparency of their fees regarding late payments or early repayment penalties.
| Lender Name | Loan Amounts | Credit Requirements | Funding Speed |
|---|---|---|---|
| Addition Financial | Up to $5,000 | See site | See site |
| GreendayOnline | $100 – $5,000 | Bad Credit Welcome | Same day |
| FastLendGo | $500 – $5,000+ | Bad/Fair/Good Credit | Quick access |
| PaydayChampion | $100 – $5,000+ | No Credit Checks | Minutes to apply |
| Mariner Finance | Up to $25,000 | Personalized offers | Under 5 minutes |
| Lendersa | See site | Bad or Good Credit | Fast closing |
Top-Rated Lenders for Bad Credit in Iowa
1. Addition Financial
Addition Financial operates as a credit union, which offers a different flavor of banking than traditional commercial lenders. They provide a variety of financial products including checking accounts and savings options alongside their lending services. It is a solid choice for those looking for a community-focused banking relationship where the primary goal is member benefit rather than maximizing shareholder profit.
Because credit unions are member-owned, their interest rates and fee structures can often be more competitive than those of large national banks. This institution is ideal for members who want more than just a one-time loan. They offer a path toward building a long-term relationship through various savings and investment tools.
If you are looking to grow your business or save for the future, this is a versatile option. For example, using a credit union to build a positive history through a small, well-managed loan can eventually open doors to mortgage products or auto loans that were previously out of reach. It is a “slow and steady” approach to financial health.
Pros:- Offers diverse financial products like savings and checking.
- Membership-based structure.
- Opportunities for financial education.
- Requires membership to access specific benefits.
2. GreendayOnline
When the unexpected happens, GreendayOnline acts like a quick safety net. They specialize in small payday loans designed to get you through an emergency. Their online process is streamlined, making it easy to secure cash when you cannot afford to wait for a traditional bank’s approval.
This is particularly useful for “bridge” scenarios. These are situations where you have a guaranteed paycheck coming in next week, but you need to pay a utility bill or a repairman today to avoid late fees or service interruptions. This lender is a perfect fit for anyone needing a quick injection of cash ranging from $100 to $5,000.
They don’t let a low credit score stand in the way of your progress. The focus here is on speed and ease of use for those in urgent situations. However, it is crucial to understand the lifecycle of these loans. Because they are designed for short-term liquidity, the repayment schedule is much tighter than a standard personal loan. You must have a clear plan to repay the funds when your next paycheck arrives.
Pros:- No hard credit checks required.
- Fast approval decisions.
- Funds can be sent as soon as the same day.
- Short-term nature of payday loans can lead to high costs.
3. FastLendGo
FastLendGo acts as a bridge for various personal financing needs. They offer a wide spectrum of products, from small $500 loans to larger $5,000 installments. They cater to a massive range of credit profiles. Whether your score is great or struggling, there is a path forward. This versatility is their greatest strength; they don’t force a “one size fits all” solution onto every applicant.
This is a highly flexible option for Iowans with specific needs, such as auto repairs or dental financing. If you need to compare local options quickly, their digital platform makes the process feel much less daunting. For example, if you are facing an unexpected transmission failure that costs $1,200, FastLendGo can provide a structured installment loan.
Spreading that cost over several months makes it much more manageable than a single lump-sum payment from a credit card. It is a practical way to handle an expensive, sudden necessity without draining your savings all at once.
Pros:- Covers a wide range of loan amounts.
- Accepts bad, fair, and good credit.
- Specialized options for specific needs like dental or auto.
- The wide variety of options requires careful selection.
4. PaydayChampion
PaydayChampion is built for the “right now” moments of life. They focus heavily on short-term installment loans that help people tackle immediate emergencies. With an emphasis on “guaranteed approval” for those with poor credit, they aim to remove the stress of the application process.
This is designed for the consumer who is less concerned with the long-term interest rate and more concerned with the immediate availability of funds to prevent a crisis. This lender is best suited for individuals who need a small amount of cash, typically between $100 and $1,000, to cover a specific bill.
Their application process is designed to be completed in mere minutes. This is essential when time is of the essence. For example, if an unexpected school fee or a grocery shortage arises, PaydayChampion provides a rapid-response solution that avoids the lengthy paperwork associated with traditional lending institutions.
Pros:- Simplified application process.
- Focus on no credit check options.
- Quick application timeframe.
- Loans are primarily short-term and intended for emergencies.
5. Mariner Finance
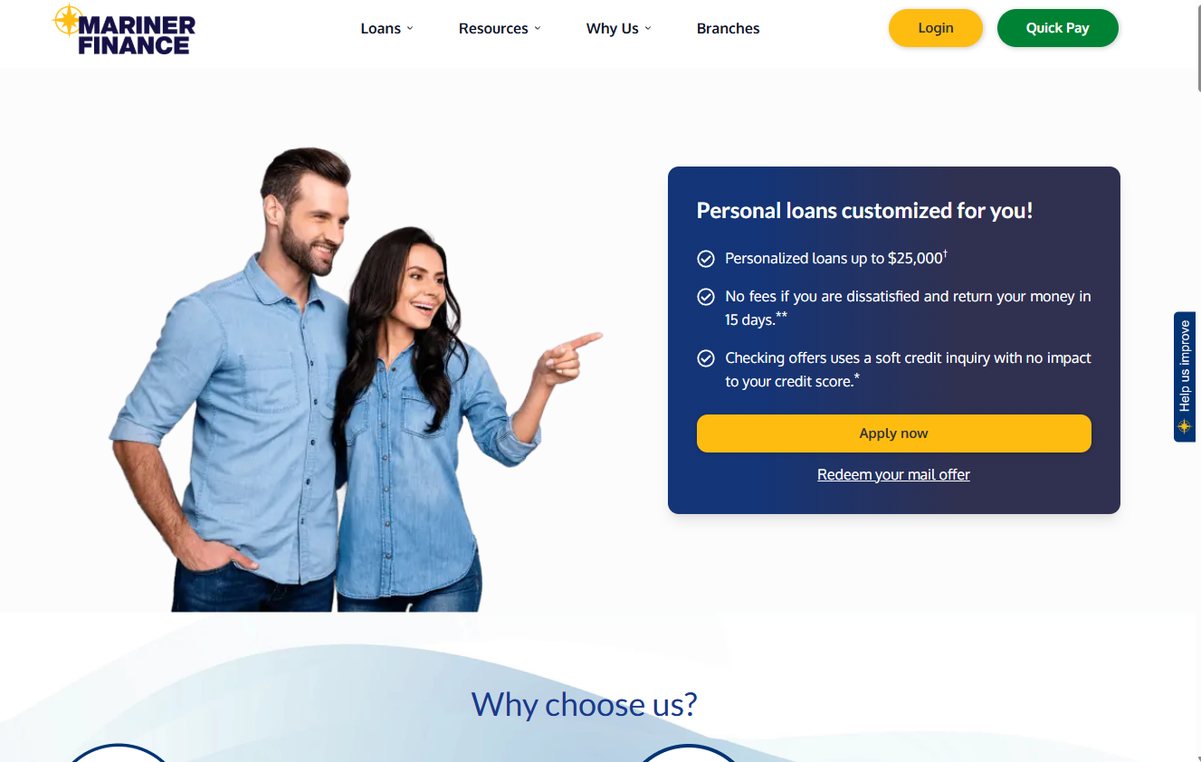
Mariner Finance offers a more substantial approach to personal lending. With loans reaching up to $25,000, they are a powerhouse for those looking to consolidate debt or manage larger expenses. Their personalized approach means they look at your specific needs rather than just a number. Instead of a binary “yes/no” based on a FICO score, they evaluate your overall ability to repay.
This often includes reviewing your income stability and existing debt-to-income ratio. They offer a unique satisfaction guarantee where you can return funds within 15 days without fees if you are dissatisfied. This is a great safety net for those who want to test a loan’s suitability before committing fully to the repayment schedule.
This is particularly useful for debt consolidation. If you take a $10,000 loan to pay off high-interest credit cards but realize after a week that the monthly payment is too steep for your budget, the 15-day window provides a crucial exit ramp.
Pros:- Higher loan amounts up to $25,000.
- 15-day satisfaction guarantee.
- Soft credit inquiry for checking offers.
- Higher loan amounts may come with more complex terms.
6. Lendersa
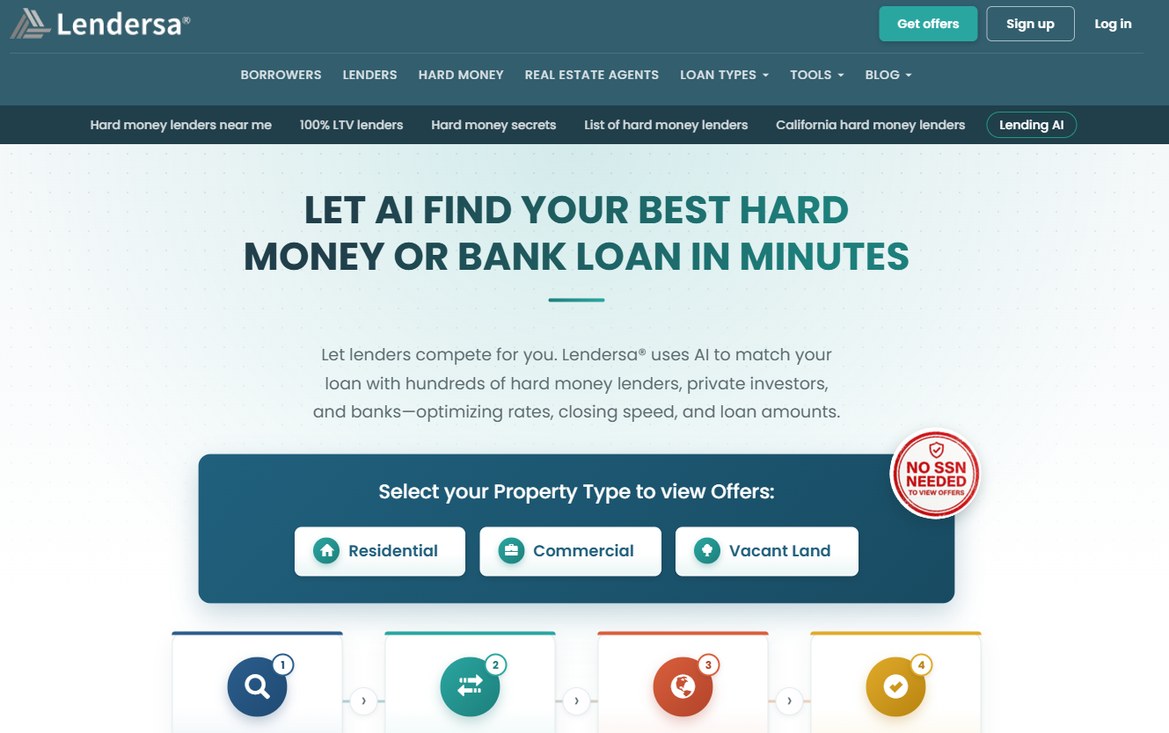
Lendersa takes a modern approach by using technology to match borrowers with the right lenders. They focus on hard money and conventional loans, making them a specialized player in the market. They are particularly useful for real estate-related or complex financing needs.
By using tech to scan a vast network of lenders, they can find matches that a human loan officer might overlook, particularly for non-traditional credit scenarios. If you are looking for speed in a competitive market, such as a real estate auction, Lendersa is a strong contender. They aim to close deals in days rather than months.
This can be a lifesaver for investors or those needing bridge loans. It is a tool for those who understand how to use leverage to their advantage in real estate or business ventures.
Pros:- Uses AI to optimize rates and speed.
- Designed for fast closing.
- Handles both hard money and bank loans.
- Specialized focus may not suit simple personal spending needs.
Comparing Loan Types: What is Right for You?
Understanding the difference between loan types is essential before you submit an application. Choosing the wrong type can lead to a “debt spiral” where you are constantly borrowing to pay off previous loans. Use the following breakdown to guide your decision.
| Loan Type | Best Use Case | Speed | Cost Profile |
|---|---|---|---|
| Payday/Short-Term | Immediate emergencies (under $500) | Instant to Same-Day | Highest APR; intended for very short durations. |
| Installment Loan | Planned expenses (car repairs, medical) | 1–3 Days | Moderate; fixed monthly payments. |
| Debt Consolidation | Paying off multiple high-interest cards | 3–7 Days | Varies; aims to lower total monthly interest. |
| Hard Money | Real estate or business investment | Days to Weeks | High; based on asset value rather than just credit. |
Smart Borrowing: A Step-by-Step Checklist
Before you commit to a loan, follow these steps to ensure you are making a sound financial decision:
- Determine the exact amount needed: Do not round up. If the mechanic says $842, do not take a loan for $1,000. Every extra dollar borrowed is a dollar that will accrue interest.
- Verify your repayment ability: Look at your budget for the next three months. If your income fluctuates, such as seasonal work, can you still afford the minimum payment during a slow month?
- Compare the APR, not just the monthly payment: A $50 monthly payment sounds easy, but if it lasts for 36 months on a $500 loan, you are paying much more than you think. The APR tells you the true cost of the money.
- Read the “Prepayment Penalty” clause: If you get a bonus or a tax refund and want to pay the loan off early, does the lender charge you a fee for that? Avoid lenders that penalize you for being responsible.
- Check for “Automatic Debit” requirements: Many quick-access lenders require you to set up automatic withdrawals from your bank account. Ensure you have the authority to manage these to avoid overdraft fees.
How to Navigate Your Loan Options
Before signing any paperwork, take a moment to breathe and look at the fine print. It is easy to get caught up in the excitement of a quick approval, but the real work begins when the repayment starts. Always ask about the total cost of borrowing, not just the monthly payment. If a lender is hesitant to provide a written summary of the total amount you will have paid back by the end of the loan term, walk away.
Avoid the trap of borrowing more than you can realistically pay back. It is a common mistake to take a larger loan than necessary just because it is available. For example, if you are consolidating $3,000 in debt, do not take a $5,000 loan “just in case” you need more later. This adds unnecessary interest to your debt load. Instead, match the loan amount strictly to the emergency or need at hand to keep your financial future bright.
Check the interest rates and fees carefully. What looks like a small monthly payment can quickly snowball if there are hidden costs or high APRs. Being diligent now will save you from a massive headache down the road in the Iowa financial market. Remember, a loan is a tool—used correctly, it can help you move forward; used incorrectly, it can become a weight that holds you back for years.